


Ashland (ASH), What Is Behind The Fresh Attention?
Ashland (ASH) just pushed deeper into agricultural chemicals with the global launch of its agrimer eco-disperse OD TVO polymeric dispersant, a nature-based crop protection ingredient aimed at performance, sustainability and compliance with tougher regulation.
Ashland’s launch of agrimer eco-disperse OD TVO lands after a mixed trading stretch, with the share price down 9.3% over 30 days but still showing a 14.6% year-to-date share price return and a 45.3% total shareholder return over the past year. This suggests that longer term momentum remains intact even as shorter term sentiment cools.
Scan beyond Ashland and find other specialty chemicals players leaning into environmentally focused product pipelines with the curated list of 19 high quality undiscovered gems.
Bulls see Ashland’s eco-focused additives and recent share gains as support for a richer multiple. Bears point to mixed longer term returns and cyclical exposure. Which story do the numbers lean toward as valuation comes into focus?
Most Popular Narrative: 14% Undervalued
Ashland’s most followed narrative pegs fair value at $80.18, which sits above the recent $68.61 close and suggests investors are being asked to weigh a discounted price against a quality skew toward specialty ingredients.
The global shift toward sustainable and bio-based materials, driven by regulatory requirements and consumer preference, continues to gain momentum, benefiting Ashland's specialty chemicals portfolio that is now more focused on high-value, sustainable, and compliant solutions; this is expected to support top-line revenue growth and margin resilience over the long term.
See why 2 investors see Ashland as 14% undervalued.
Result: Fair Value of $80.18 (UNDERVALUED)
Still, the Ashland narrative frays quickly if demand softness in Specialty Additives persists, or if consumer shifts affect its Personal Care and Life Sciences exposure.
Find out about the key risks to this Ashland narrative.
Another View on Ashland’s Valuation
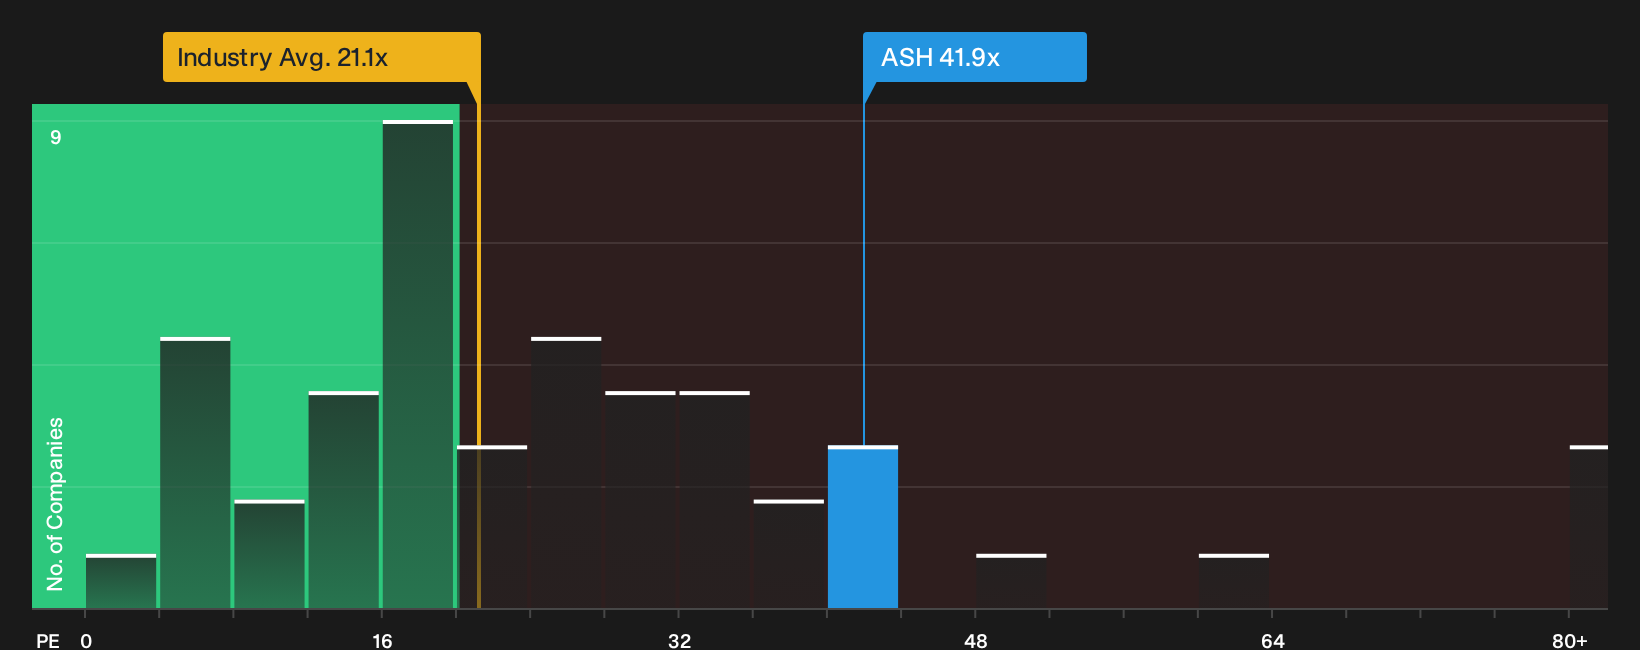
On the other side of the ledger, Ashland looks expensive when the price tag is compared with earnings today. The stock trades on a P/E of 41.9x versus 21.7x for the wider US Chemicals group, while the fair ratio is estimated at 25.2x, which points to meaningful valuation risk if sentiment cools.
For investors weighing whether the current premium is justified by the story around eco-focused growth and margin expansion, the key question is how long the market will tolerate paying well above that fair ratio if execution or demand weaken.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Ashland’s valuation and growth story make this a stock you need to inspect for yourself, using the same numbers underpinning both bullish and cautious views. To pressure test your own thesis against the key positives and concerns the market is watching, review the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Ashland?
If Ashland has you thinking harder about price, quality and risk, do not stop with one ticker. Put a wider watchlist to work for you.
- Target potential value opportunities early by scanning the 28 high quality undervalued stocks that combine stronger fundamentals with more modest valuation multiples.
- Prioritize resilience over drama by zeroing in on the 31 resilient stocks with low risk scores that may better fit a capital preservation mindset.
- Strengthen your core holdings by filtering for companies in the list of solid balance sheet and fundamentals (25 results) so financial footing supports your long term thesis.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com