


3 Cash Rich US Stocks Built For Higher Rates
US Treasury yields are pressing higher, borrowing costs keep grinding up, and plenty of investors are wondering whether to stay all-in on growth stories or look for sturdier cash machines. When money gets more expensive, balance sheets and free cash flow suddenly matter a lot more, which can leave some portfolios exposed. This article highlights three large-cap companies with strong cash positions that appear closely aligned with this changing rate environment.
The three stocks that follow are just a starter pack, while the full screen on Simply Wall St surfaced 14 more large caps with similar balance sheet strength and valuation appeal that are not covered here. To go straight to the wider opportunity set, analyze, filter, and identify your own highest conviction ideas with the High-Quality, Cash-Rich Large-Cap Value Stocks screener.
Global Industrial (GIC)
Overview: Global Industrial Company is a US based distributor supplying a wide range of industrial and MRO products to businesses and institutions.
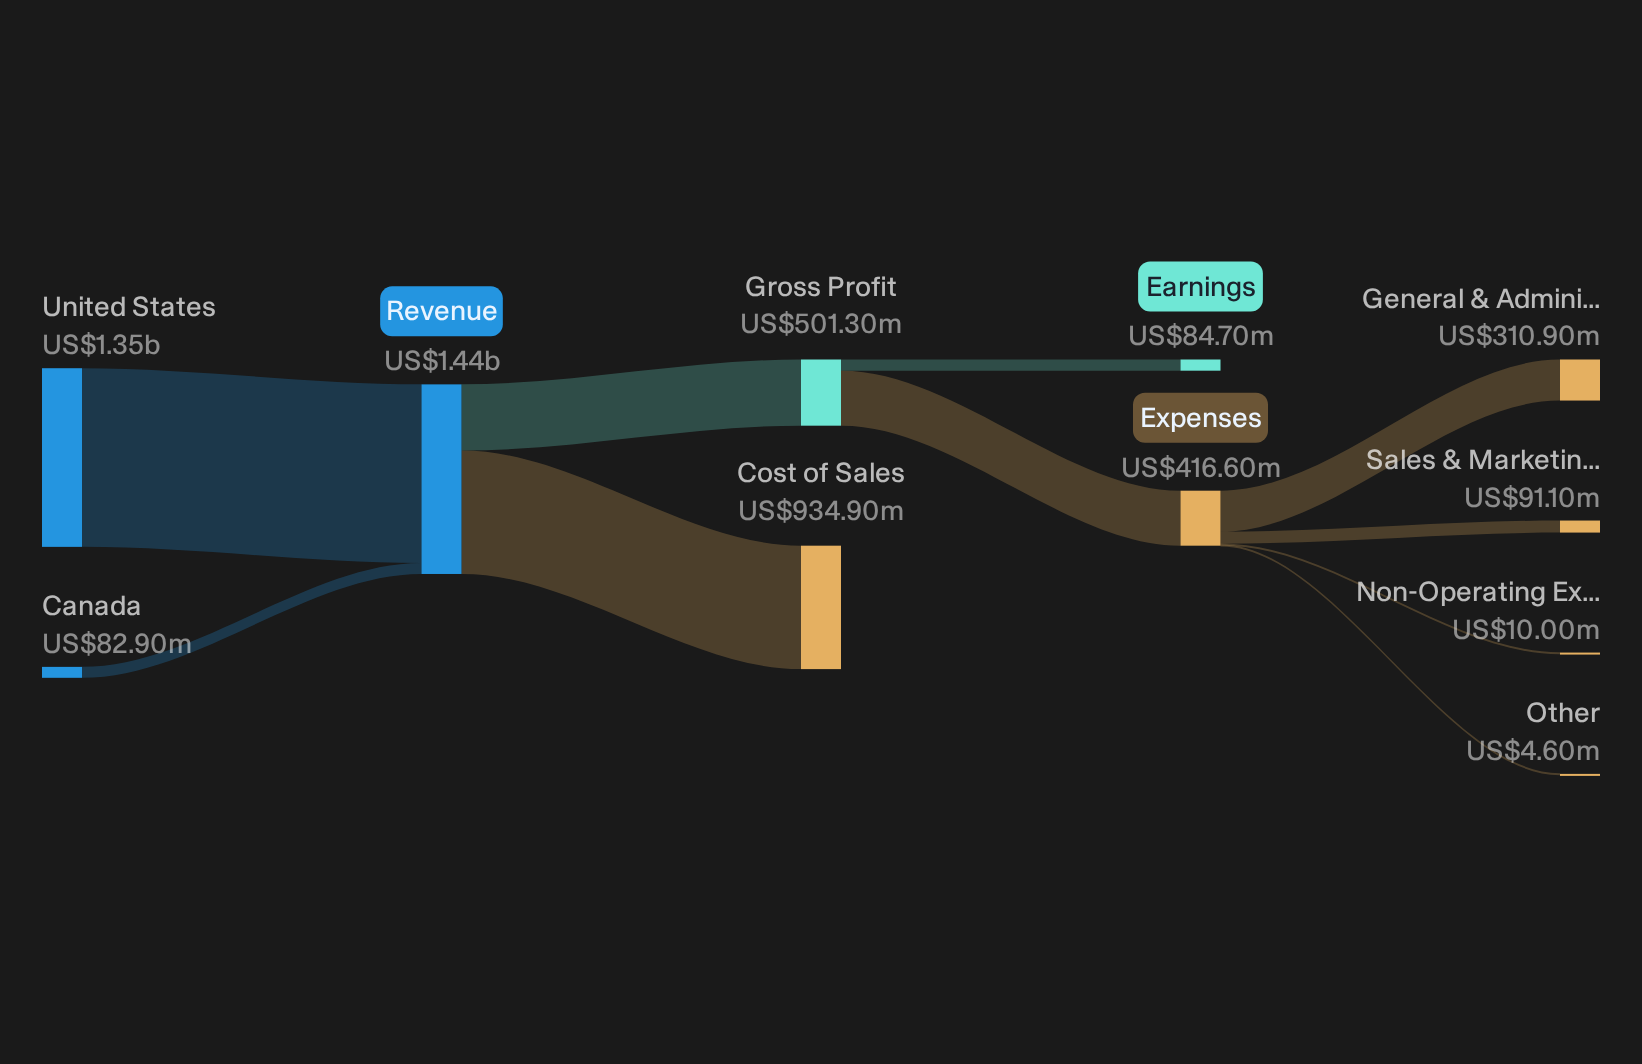
Operations: Global Industrial generates all its revenue from the Industrial Products Group, with US$1.44b in sales, primarily from the United States and Canada.
Market Cap: US$1.60b
Global Industrial fits this high-quality, cash-rich value theme because it combines an asset-light distribution model with steady demand for essential MRO supplies. This can appeal to investors looking for cash generation as borrowing costs climb.
"The company is intentionally shifting its go-to-market strategy to focus on higher-value strategic accounts, increasing customer specialization, and deepening relationships, which is likely to boost revenue growth and enhance gross margins through improved customer retention and share of wallet gains."
What really matters now is how one unresolved pressure on future margins plays out alongside that shift toward larger, stickier customers.
That margin question is exactly what the full narrative for Global Industrial unpacks, including how pricing power, mix shift, and cash returns could evolve if the rate backdrop remains challenging for an extended period.
Argan (AGX)
Overview: Argan builds large power generation and related infrastructure projects under long-term contracts, which can suit a high-quality, cash-rich value profile.
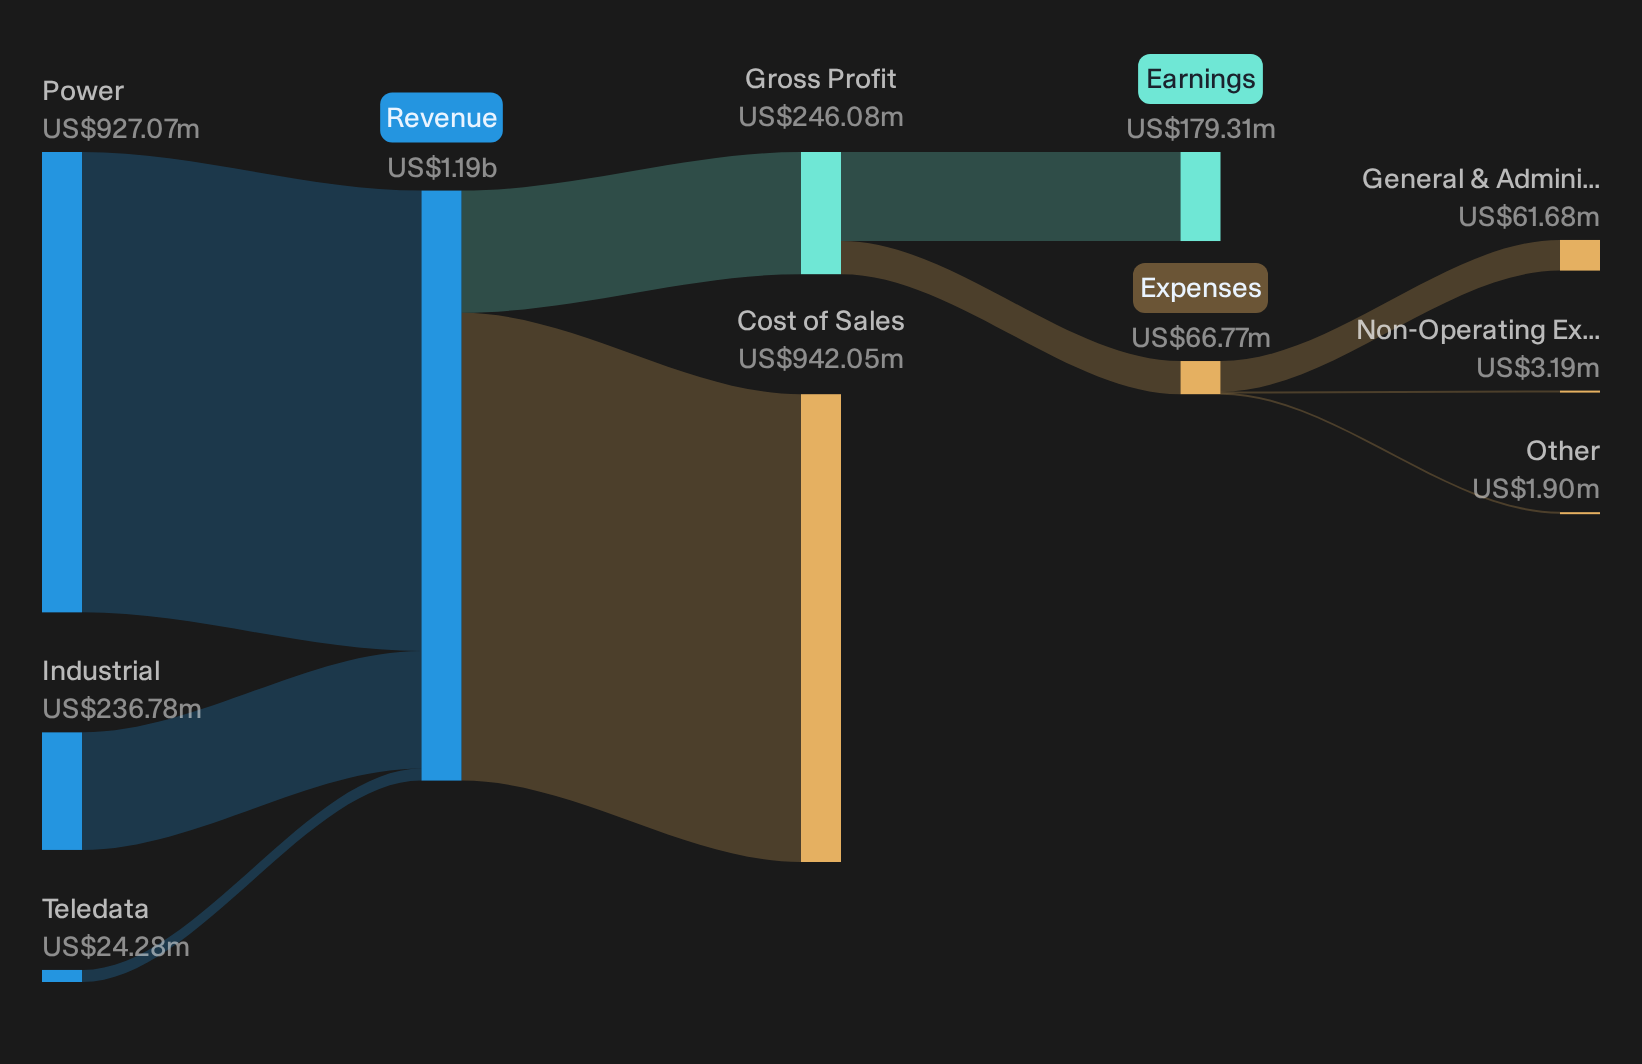
Operations: Argan earns most of its US$1.19b revenue from Power projects at about US$927 million, with Industrial and Teledata providing smaller contributions.
Market Cap: US$5.3b
Argan fits this higher-rate playbook because it focuses on essential energy infrastructure, relies on contracted project cash flows, and keeps a disciplined balance sheet at the center of its expansion plans.
"The aging North American power infrastructure and rising electricity demand, driven by widespread electrification and the proliferation of AI data centers, are resulting in record project backlog and robust pipeline visibility for Argan."
What really matters next is how one constraint on turning that backlog into timely, high-margin revenue unfolds over the coming years.
That execution risk is exactly what the full narrative for Argan unpacks, revealing how Argan could turn an accelerating project backlog into durable cash generation while managing contract and cost pressures.
Fastenal (FAST)
Overview: Fastenal is a large distributor of fasteners and industrial supplies that keeps factories, construction sites, and maintenance operations stocked worldwide.
Operations: Fastenal generates about US$7.24b from US operations and a further US$1.51b from Canada, Mexico, and other international markets.
Market Cap: US$56.8b
Fastenal fits this high-quality, cash-rich large-cap value screen because it mixes recurring industrial demand with a conservative balance sheet and strong cash generation. These factors can matter more as borrowing costs climb.
"The company is treating its digital footprint and Fastenal Managed Inventory platforms, which together now touch over 60% and roughly 45% of sales, as a scalable infrastructure that can support higher throughput per branch and salesperson and therefore lift earnings power as volumes rise without a matching increase in SG&A."
What really matters next is how one unresolved pressure on gross margin interacts with that higher-throughput model to shape long term earnings power.
That margin tension is exactly what the full narrative for Fastenal unpacks, revealing where Fastenal’s throughput model could be quietly accelerating earnings power or masking brewing pressure points.

Curious About What You Might Be Missing?
Fresh ideas do not sit still. While potential breakouts build momentum and laggards keep dropping, information advantage decays fast. Scan these under the radar lists now and review them early.
- Target dependable income streams by reviewing 7 dividend fortresses, curated for investors who want payouts that can help anchor a portfolio when prices start flying around.
- Hunt for overlooked quality by scanning the 19 high quality undiscovered gems, built to surface fundamentally strong businesses that many investors have not caught onto yet.
- Position around the future of AI infrastructure by checking the 90 AI infrastructure stocks, where potential beneficiaries of rising compute demand are grouped before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com