


How Investors Are Reacting To Curtiss Wright Stock Earnings Outlook
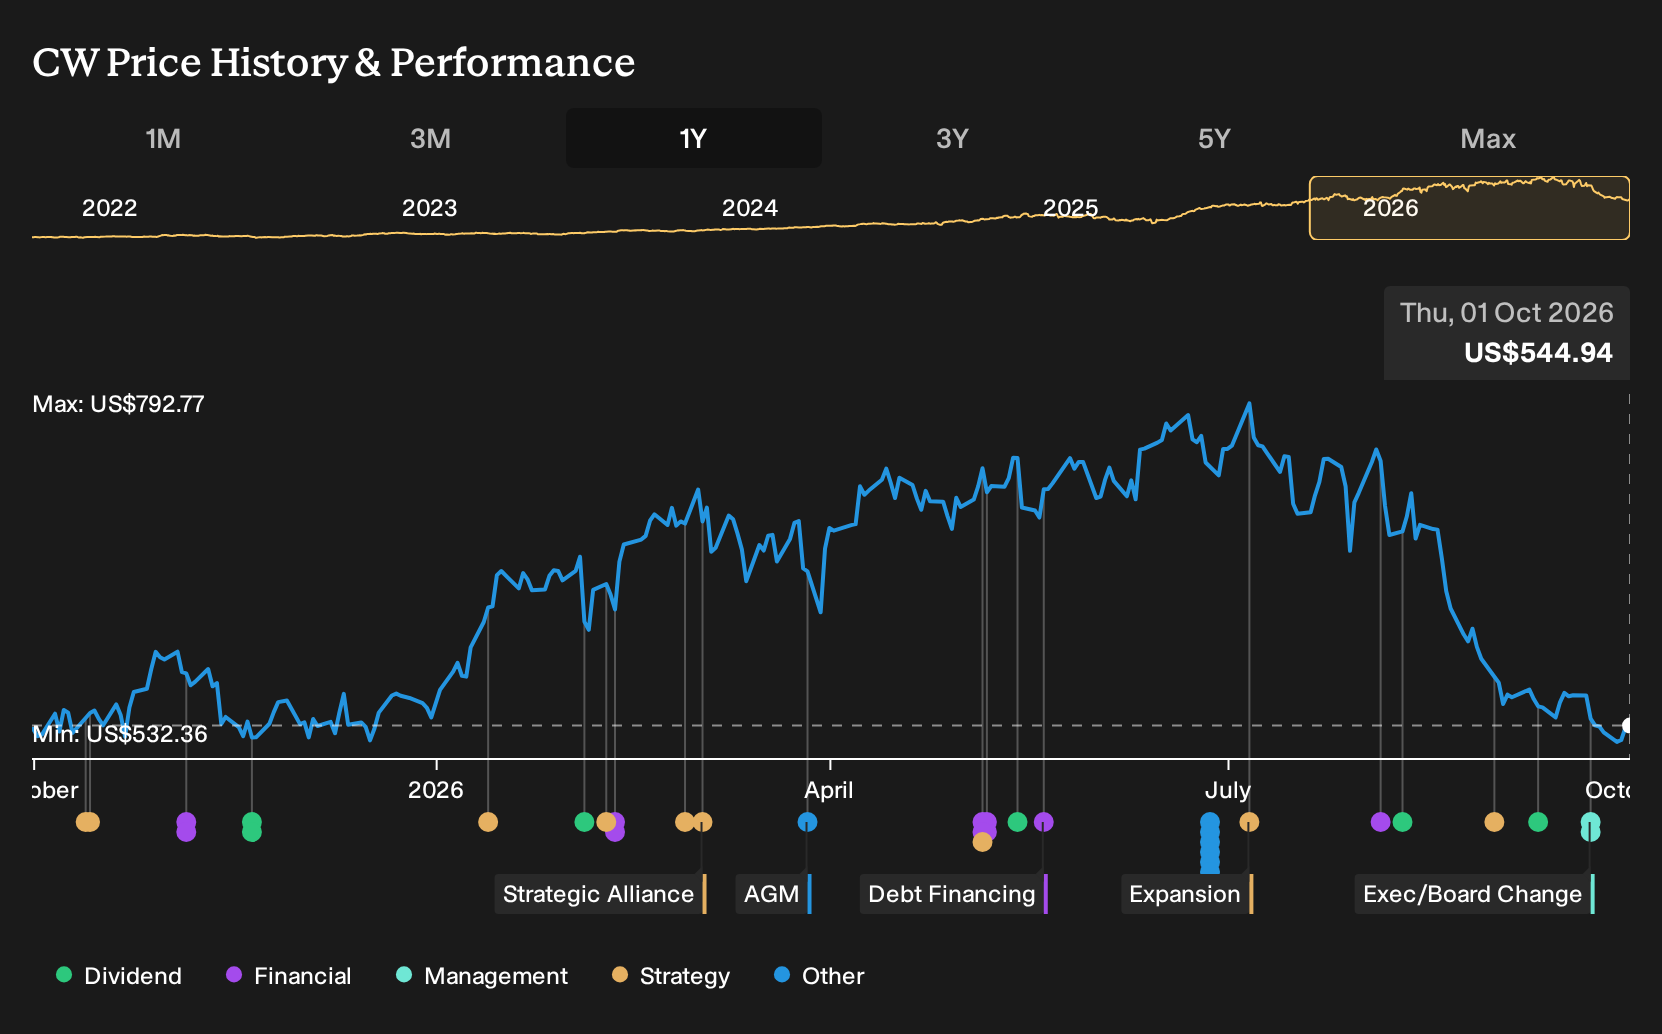
- Curtiss-Wright announced that Chief Operating Officer Kevin M. Rayment will succeed Lynn M. Bamford as CEO and President, and join the Board on January 1, 2027. Bamford will become Executive Chair after a long tenure that included record results, portfolio reshaping, and $1.7 billion returned to shareholders.
- The leadership change comes against a backdrop of solid recent execution at Curtiss-Wright, with revenue, earnings per share, and free cash flow margin all improving. This gives the incoming CEO a business with greater financial flexibility and a clearer focus on Aerospace & Defense and Commercial markets.
- This article will examine how Curtiss-Wright’s investment narrative is shaped by this leadership transition and its stronger free cash flow profile.
Scan how Curtiss-Wright’s leadership shift and free cash flow story compares with other high quality companies by reviewing our hand picked 19 high quality undiscovered gems in similar industrial and defense niches.
What Is Curtiss-Wright's Investment Narrative?
The Curtiss-Wright story is really about consistent execution in complex, high-spec markets and the cash that falls out of that model. Aerospace & Defense, naval programs and industrial customers tend to be sticky once you are qualified on a platform, which can support steady orders and pricing power when you deliver on time. Free cash flow margins have moved higher over five years, giving the business more room to fund acquisitions, share repurchases and dividends without stretching the balance sheet.
Against that backdrop, the planned handover from Lynn Bamford to Kevin Rayment in 2027 looks more like continuity than upheaval. Rayment has been COO since 2021 and has already been involved in operations and capital allocation decisions that shaped Curtiss-Wright into its current mix. Short term catalysts around program wins, electronics demand and naval and nuclear projects still hinge on contract timing and execution, not on this leadership change. The main watchpoints remain capital intensity, valuation at a 37.2x P/E and reliance on external borrowing.
Even so, there is one structural weak spot in the Curtiss-Wright story that becomes harder to ignore once you look closely at ...
There's only one way to know the right time to buy, sell or hold Curtiss-Wright. Head to Simply Wall St's company report for the latest analysis of Curtiss-Wright's Fair Value.
Exploring Other Perspectives
For Curtiss-Wright, the big swing factor in the more optimistic narrative is nuclear. The most bullish analysts were penciling in revenue of about US$4.8b and earnings of US$780.0m by 2029, well above consensus. Those views were formed before this CEO transition, so you should expect opinions to shift as succession plans progress.
Explore 4 other Curtiss-Wright fair value estimates, including one that suggests there may be as much as 60% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Curtiss-Wright research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Curtiss-Wright. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Curtiss-Wright's overall financial health at a glance.
Looking For More Investment Ideas Beyond Curtiss-Wright?
If the Curtiss-Wright story has sharpened your thinking on quality, balance sheets and cash generation, use that same lens to scan a wider opportunity set with the Simply Wall St Screener.
- For investors who want potential value combined with resilient fundamentals, review a curated 28 high quality undervalued stocks that already pass strict quality and balance sheet checks.
- If capital preservation sits high on your priority list, focus on a targeted 31 resilient stocks with low risk scores that score well on financial strength and earnings stability.
- When you care most about financial resilience before anything else, start with a list of solid balance sheet and fundamentals (25 results) and then layer on your own return and sector preferences.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com