


Can Carvana (CVNA) Look Cheap On Its Minneapolis Same Day Delivery Launch?
Carvana’s Minneapolis same day launch puts logistics in focus
Carvana (CVNA) has rolled out same day vehicle delivery and pickup in the Minneapolis area, tying the new service directly to its existing logistics and reconditioning network across more than 20 states.
Carvana’s share price has eased in recent months, with a 30 day share price return of down 12.66% and a year to date share price return of down 21.25%, even though the 3 year total shareholder return is very large at roughly 8x. This pullback comes as the Minneapolis same day launch and an upcoming third quarter 2026 earnings release on October 28 keep attention on how the business model and logistics build out might be reshaping both growth expectations and perceived risk.
Scan other logistics-driven retail plays that show similar momentum traits using the curated list of list of solid balance sheet and fundamentals (25 results).
Bulls point to Carvana’s logistics build out and strong multi year shareholder gains, while bears focus on the recent share price slide and execution risk. Which story do the current valuation markers suggest is more likely?
Most Popular Narrative: 24% Undervalued
Carvana’s most followed thesis pegs fair value at $82.98, well above the last close at $63.04. This puts the Minneapolis logistics push into a broader story about scale, unit economics and funding costs.
The shift to a stronger balance sheet, with net debt to trailing 12 month adjusted EBITDA at 1.0x and refinancing of higher cost secured notes into a lower rate term loan that cuts annual interest by about US$45 million, creates room for Carvana to reinvest in growth drivers such as advertising and lower APRs, which can influence future revenue and earnings.
See why 56 investors see Carvana as 24% undervalued.
Result: Fair Value of $82.98 (UNDERVALUED)
Still, the Carvana story can break if slower inventory growth versus sales and weaker gross profit per unit persist and start to weigh more heavily on earnings power.
Find out about the key risks to this Carvana narrative.
Another View: Carvana’s Rich P/E Signals Less Cushion
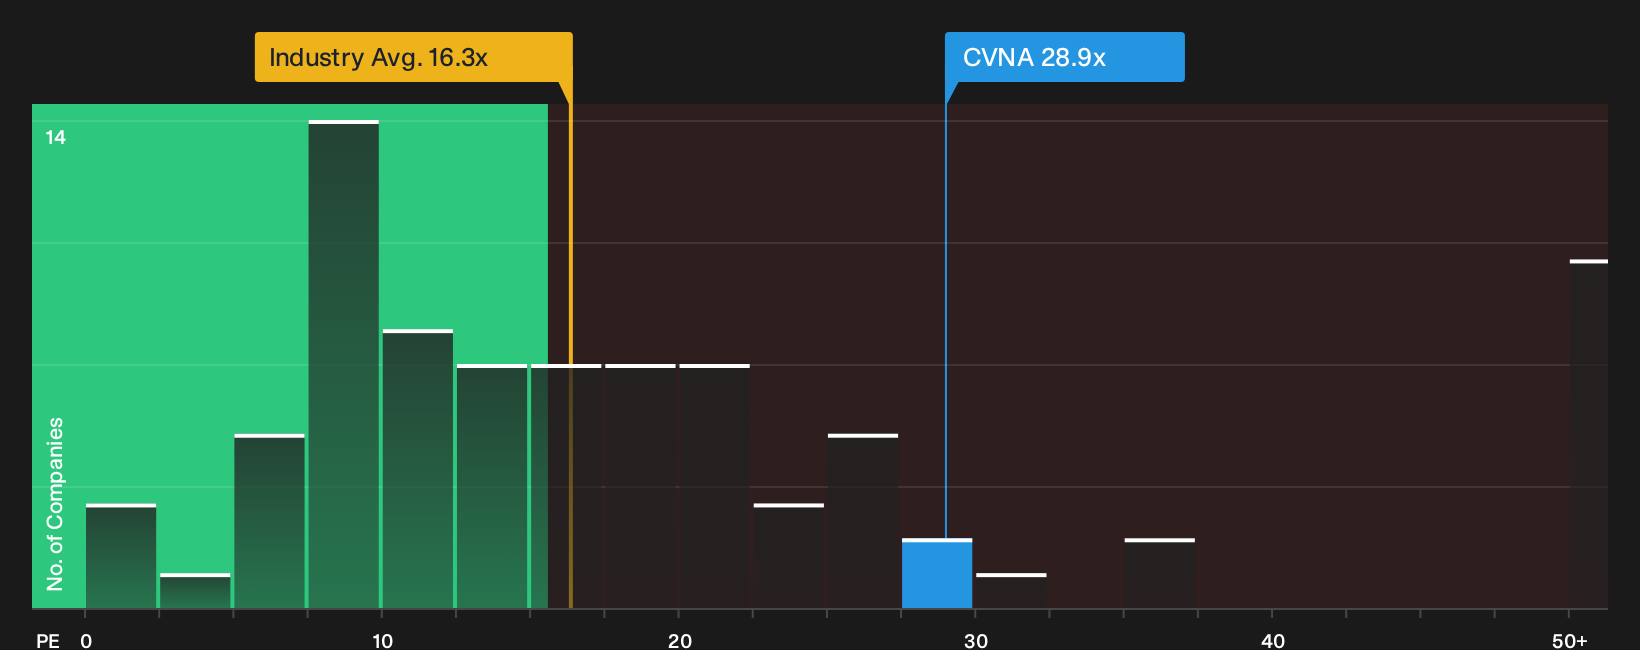
The earlier fair value of $82.98 paints Carvana as undervalued, but the plain P/E picture looks tougher. At 28.9x earnings, the stock trades well above the US Specialty Retail group on 16.3x and the peer average on 16.9x. It also sits higher than the 24.4x fair ratio that the market could move toward over time. If sentiment cools or growth assumptions soften, that gap reduces room for error more than the headline fair value story suggests.
For investors weighing this against the logistics and earnings momentum, the question is simple: Is the current premium multiple a price you are comfortable paying for that narrative, or does it tilt the risk reward balance too far toward optimism?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals run through this Carvana story, so move quickly, review the underlying numbers and judge the balance of risks and rewards yourself by checking 2 key rewards and 1 important warning sign.
Looking for more Carvana investment ideas?
If Carvana has sharpened your focus on pricing and risk, do not stop at one ticker. Use the Simply Wall Street Screener now to uncover fresh opportunities, compare quality, and pressure test your thesis before the market moves first.
- Target resilient income by reviewing companies that feature the 7 dividend fortresses and see how steady cash returns fit into your portfolio mix.
- Hunt for stronger value by scanning the 28 high quality undervalued stocks to line up stocks where quality and price appear to work in your favor.
- Reduce potential downside by shortlisting the 31 resilient stocks with low risk scores to focus on businesses with more robust fundamentals and calmer risk profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com