


Is CoStar Group (CSGP) Below Fair Value Following Its Index Removal?
Index removal puts CoStar Group in sharper focus
CoStar Group (CSGP) is back on many investors’ watchlists after its recent removal from the FTSE All-World Index. This type of move often triggers portfolio rebalancing and fresh scrutiny.
The stock has already been under pressure, with the share price down about 15% over the past month and roughly 58% for the year to date as of 30 September 2026. That slump has unfolded alongside muted bookings and competitive pressures highlighted in recent analysis.
Recent headlines around CoStar Group mix index removal with ongoing business updates. The index exit in mid September appears to have added to existing concern, with the share price down sharply year to date while long term total shareholder returns have also been weak.
Momentum has been fading over recent months as the 30 day share price return declined 13.3% and the 90 day move fell 7.6%, even though the latest 1 day gain of 1.2% hints at pockets of bargain hunting around the current US$27.72 level.
Alongside this, the 1 year total shareholder return declined 67.0% and the 3 and 5 year total shareholder returns fell 65.1% and 68.2% respectively. This points to a long running reset in expectations as investors weigh muted bookings, competitive pressure and fresh index related selling against ongoing client wins in areas like Canada and regular investor outreach at conferences.
Compare CoStar Group's reset with other potential rebound ideas by scanning our hand picked 28 high quality undervalued stocks, which currently score well on both quality and pricing pressure.
For CoStar Group, bulls point to fresh adoption in Canada and a sizeable estimated discount to fair value, while bears focus on index driven selling and long running share price losses. Which story fits the numbers that follow?
Most Popular Narrative: 26% Undervalued
CoStar Group last closed at $27.72, while the most followed narrative anchors fair value at $37.30. This implies a sizeable discount and puts execution on its multi platform plan under the microscope.
The key thing that has to go right is that CoStar Group turns Homes.com, Apartments.com, Zonda, international portals and AI products into a durable, profitable multi-vertical platform, despite muted bookings, lower revenue guidance and competitive pressure in multifamily advertising.
The current valuation of CoStar Group implies that the market is discounting execution risk around revenue growth, Homes.com scalability and AI disruption more heavily than the recent uplift in margins and record adjusted EBITDA guidance.
See why 27 investors see CoStar Group as 26% undervalued.
Result: Fair Value of $37.30 (UNDERVALUED)
Still, the CoStar Group story could be knocked off course if muted bookings persist or if discounting pressure in multifamily advertising continues to squeeze Apartments.com economics.
Find out about the key risks to this CoStar Group narrative.
Another View: What CoStar Group’s Ratios Are Saying
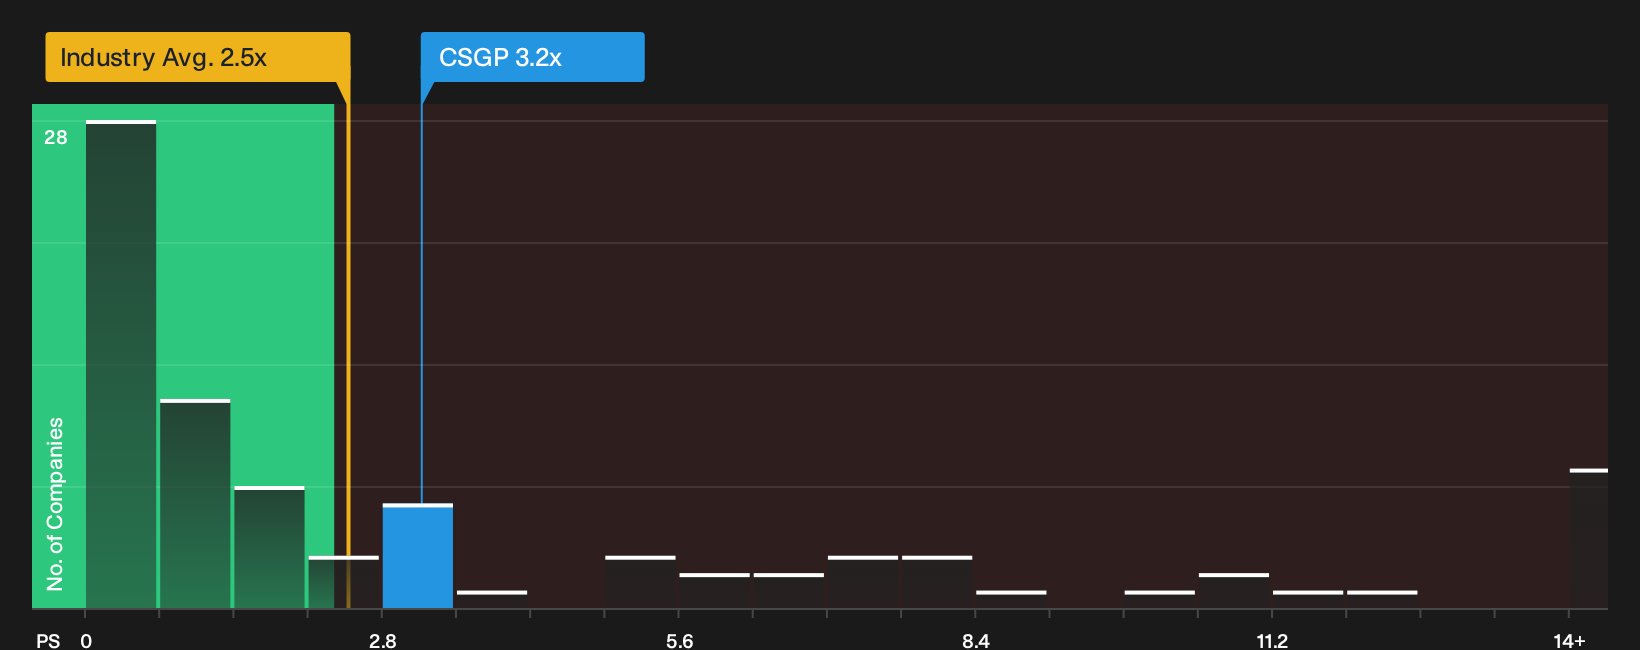
The story shifts once you look at CoStar Group through its sales multiple. The stock trades on a P/S of 3.2x, which is richer than both peers at 1.2x and the wider US Real Estate sector at 2.5x, even though the fair ratio estimate sits slightly higher at 3.6x.
That mix points to a company priced above its group but slightly below where the fair ratio suggests the market could drift over time. The key question is whether investors see that gap as valuation risk or a margin of safety if the business hits its targets.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around CoStar Group can make the picture feel messy. Move quickly, weigh both the downside risks and upside potential, and then test your own thesis against the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond CoStar Group?
If CoStar Group has you rethinking your watchlist, do not stop there. Fresh opportunities rarely wait around for investors who hesitate too long.
- Target dependable income by scanning companies positioned as potential payout anchors through the 7 dividend fortresses.
- Surface resilient balance sheets by running the list of solid balance sheet and fundamentals (25 results) and filtering for businesses built to handle tougher conditions.
- Unearth potential future leaders early by checking the 19 high quality undiscovered gems before the crowd turns its attention their way.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com