


Hammond Power Solutions (TSX:HPS.A) Expands In Fort Worth As Valuation Upside Stays In Focus
Hammond Power Solutions (TSX:HPS.A) has drawn fresh attention after agreeing to a long term lease for a new manufacturing facility in Fort Worth, Texas, which is aimed at expanding capacity for large transformers.
That Fort Worth announcement comes after a powerful run in Hammond Power Solutions’ shares, with a 30-day share price return of 28.31% and a year-to-date share price gain of 77.68%, even though the 90-day share price return fell 10.05%.
For longer term holders, the move adds to an already strong story, with a 1-year total shareholder return of 130.89% and a 5-year total shareholder return that is more than 27x. This suggests that momentum has been building rather than fading.
Capitalize on Hammond Power Solutions' momentum by scanning a curated field of grid and transmission players with the 39 power grid technology and infrastructure stocks that are poised to benefit from similar infrastructure demand.After a move this sharp and with a new Fort Worth build on the way, the real puzzle is whether Hammond Power Solutions still offers valuation upside or if most of the rerating has already occurred.
Most Popular Narrative: 24% Undervalued
Hammond Power Solutions last closed at CA$288.73, while the most followed narrative pegs fair value closer to CA$377.88. This frames the Fort Worth expansion against expectations for much larger future earnings power.
The ramp-up of new manufacturing facilities in Mexico, with expectations to be fully loaded and operational by early next year, will significantly increase production capacity, positioning Hammond to capture greater share of increasing North American demand and support long-term revenue growth while enabling improved operating leverage and margin expansion. Robust and accelerating demand from data center projects, highlighted as the fastest-growing segment and supported by ongoing digitization trends, is expected to drive sustained order flow and backlog, positively impacting top-line growth and supporting consistent earnings.
See why 39 investors see Hammond Power Solutions as 24% undervalued.
Result: Fair Value of CA$377.88 (UNDERVALUED)
Still, the bullish Hammond Power Solutions narrative can crack if material costs stay elevated or if new plants in Mexico and Texas suffer prolonged ramp-up inefficiencies.
Find out about the key risks to this Hammond Power Solutions narrative.
Another View: Hammond Power Solutions Through The P/E Lens
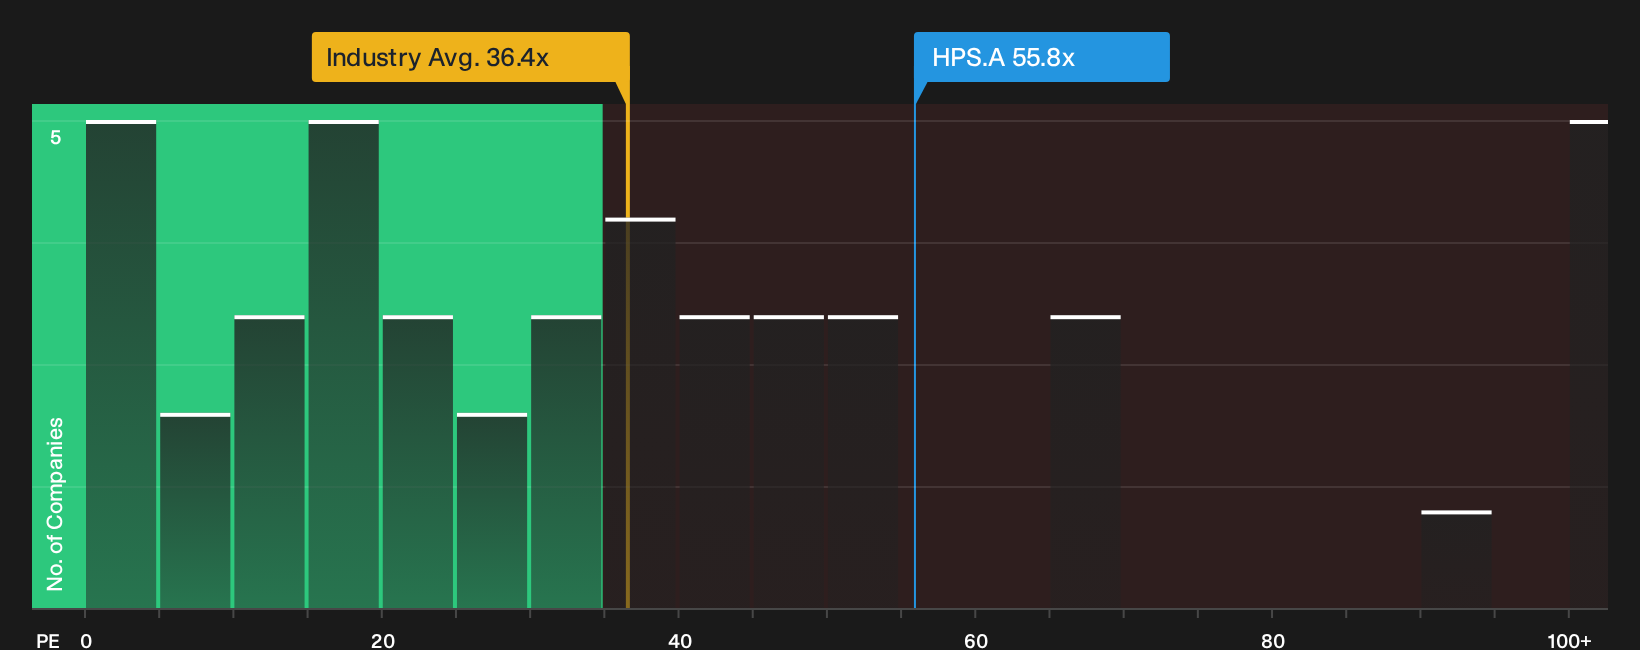
The story shifts when you look at Hammond Power Solutions through its P/E ratio instead of fair value models. The stock trades on about 55.8x earnings, while peers in its group sit near 42.7x and the broader North American Electrical industry is around 36.4x. The fair ratio is estimated at 46.7x, which is a level the market could move toward over time. That premium can be read as confidence in the growth outlook or simply as valuation risk that leaves less room for error if expectations change.
Before leaning on any single approach, it helps to see how those earnings multiples compare against detailed cash flow and fundamentals in our valuation breakdown, including the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the Hammond Power Solutions story so far feels split between optimism and caution, move quickly and weigh those signals yourself with the 3 key rewards and 2 important warning signs.
Looking for more Hammond Power Solutions style ideas?
If Hammond Power Solutions has sharpened your focus, do not stop here. Broaden your opportunity set with targeted screens that surface concrete ideas quickly.
- Zero in on quality at a discount by scanning companies flagged as 5 high quality undervalued stocks that pair stronger fundamentals with prices the market has not fully reflected yet.
- Prioritise resilience by filtering for businesses in the 9 resilient stocks with low risk scores that combine steadier financial profiles with lower overall risk scores.
- Hunt for future leaders early by combing through the 9 high quality undiscovered gems where solid fundamentals have not yet attracted broad attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com