


Is Stronger Hiring Altering The Investment Case For ADP Stock?
- Automatic Data Processing reported in its September National Employment Report that private sector employment rose by 90,000 jobs, with hiring led by education and health care and leisure and hospitality, while financial activities and professional and business services showed weaker conditions.
- ADP Pay Insights showed base pay up 3.2% and gross pay up 4.7% year over year, giving investors a real time view of wage trends that feed directly into demand for the company’s human capital management and payroll solutions.
- We will now look at how Automatic Data Processing's investment narrative is affected by stronger private sector hiring and wage growth.
Scan beyond Automatic Data Processing and see how other employment sensitive businesses stack up using our hand picked 31 resilient stocks with low risk scores as a starting point for further ideas.
Automatic Data Processing Investment Narrative Recap
For an investor in Automatic Data Processing, the core belief is that demand for payroll, HR outsourcing and HCM software remains steady through cycles while AI tools and Next Gen platforms support efficiency. The September ADP report showing 90,000 private jobs added and pay running in the low single digits generally fits that thesis, but it does not radically change it.
The near term swing factor still looks like execution in Employer Services and AI driven products rather than monthly hiring noise. The main risk remains margin pressure in the PEO unit from pass through costs and medical inflation. This employment print does little to ease that concern or make it worse in a clear way.
With no fresh corporate announcements tied directly to this hiring data, the most helpful reference point is management’s focus on AI automation across ADP Assist, Lyric and the Zone. Those tools aim to cut service contacts per client and improve productivity, which matters when wage growth and labor markets keep operating costs elevated.
Viewed against the September report, steady job creation and 3.2% base pay growth keep the backdrop supportive for Automatic Data Processing’s recurring payroll volumes, yet also underline why cost discipline and AI enabled service models are front and center. The catalyst to watch is how far those products can offset any ongoing PEO margin strain.
Automatic Data Processing’s current analyst narrative points to revenues of US$25.9b and earnings of US$5.6b by 2029. This outlook is built on an assumed 5.7% yearly revenue growth rate and an earnings increase of roughly US$1.2b from US$4.4b today.
Uncover why Automatic Data Processing's fair value indicates a 9% potential upside to its current price that could narrow quickly.
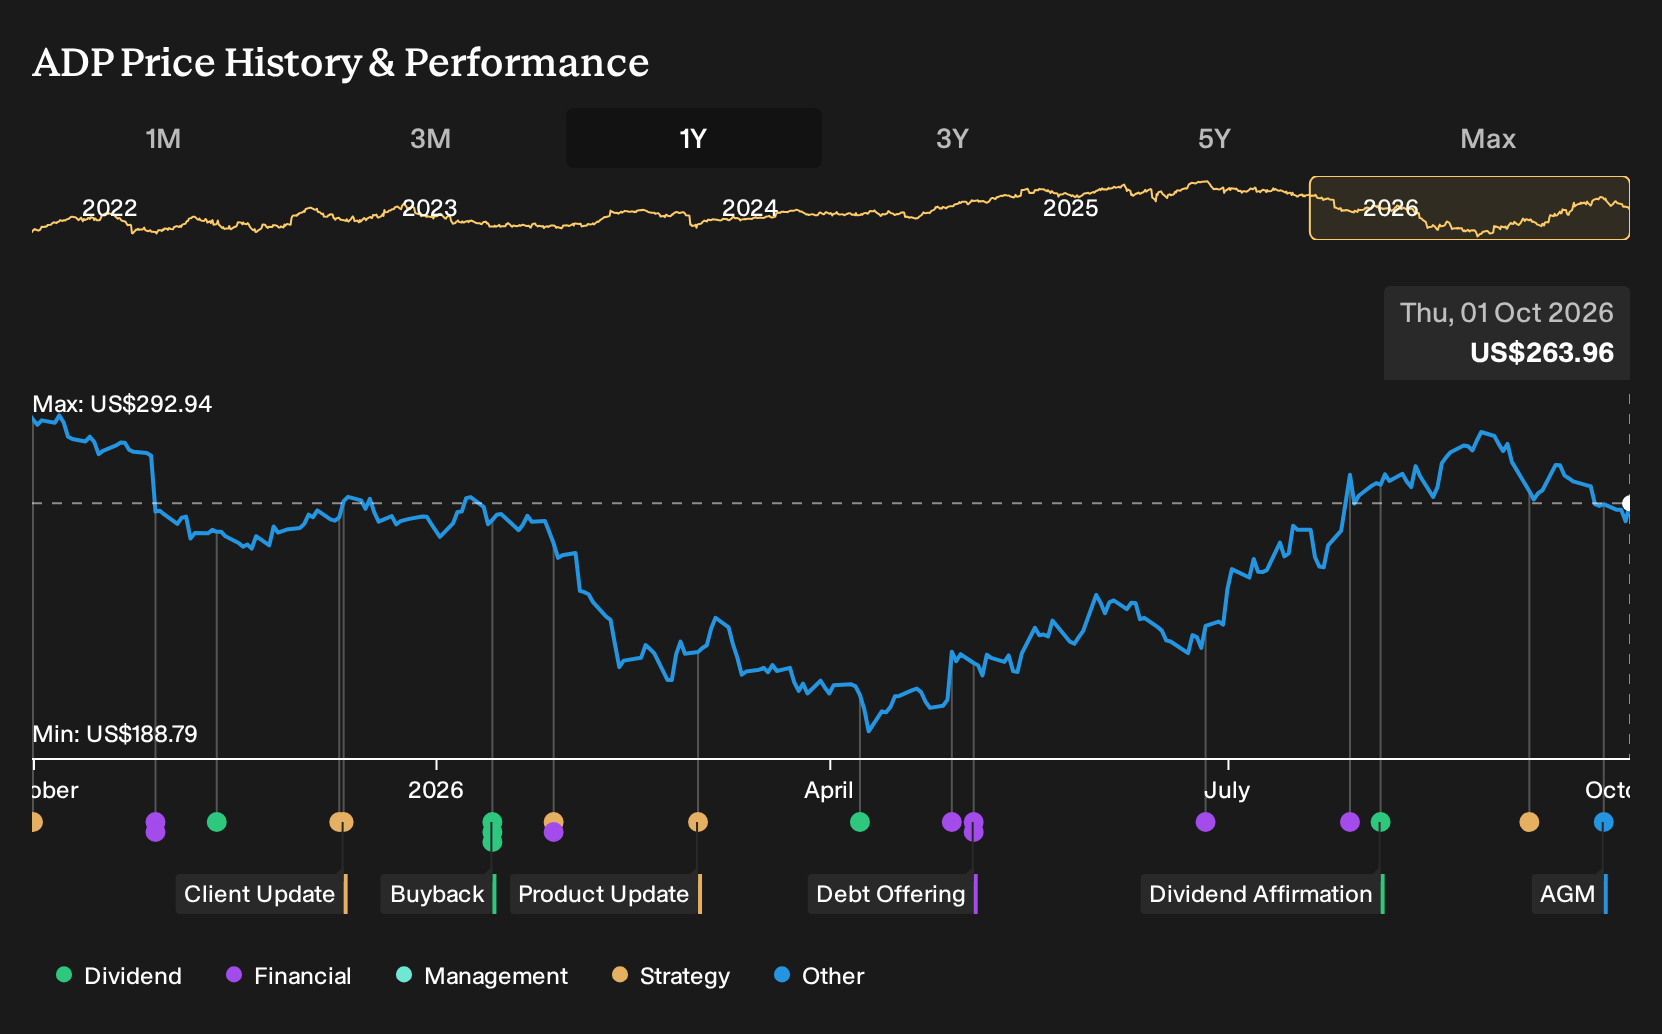
Exploring Other Perspectives
One alternate view on Automatic Data Processing focuses on client funds interest income. The more cautious analysts were pencilling in about US$25.8b of revenue and US$5.6b of earnings by 2029 on a lower 20.5x P/E. With wage growth at 3.2% and gross pay up 4.7%, those expectations may shift. Explore both narratives.
Explore 4 other Automatic Data Processing fair value estimates, including one that suggests it could be worth just $255.78.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Automatic Data Processing research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Automatic Data Processing. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Automatic Data Processing's overall financial health at a glance.
Looking For More Investment Ideas Beyond Automatic Data Processing?
If the Automatic Data Processing story has sharpened your thinking on payroll, hiring and cash flow resilience, use that same lens across the wider market. The Simply Wall St Screener lets you sort companies by balance sheet strength, income profile and valuation so you can build a watchlist that actually matches your risk tolerance and income needs.
- If capital preservation is your priority, start with a focus on resilience and work through 31 resilient stocks with low risk scores that pair sturdier fundamentals with lower overall risk scores.
- For investors hunting for mispriced opportunities, filter for quality businesses that trade below their estimated worth by checking out 28 high quality undervalued stocks with stronger cash flows and healthier financials.
- Income focused readers who care about stability alongside yield can scan 7 dividend fortresses and spot companies offering 5%+ payouts backed by more durable profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com