


Should Executive Board Resignation Require Action From Andritz Stock Investors?
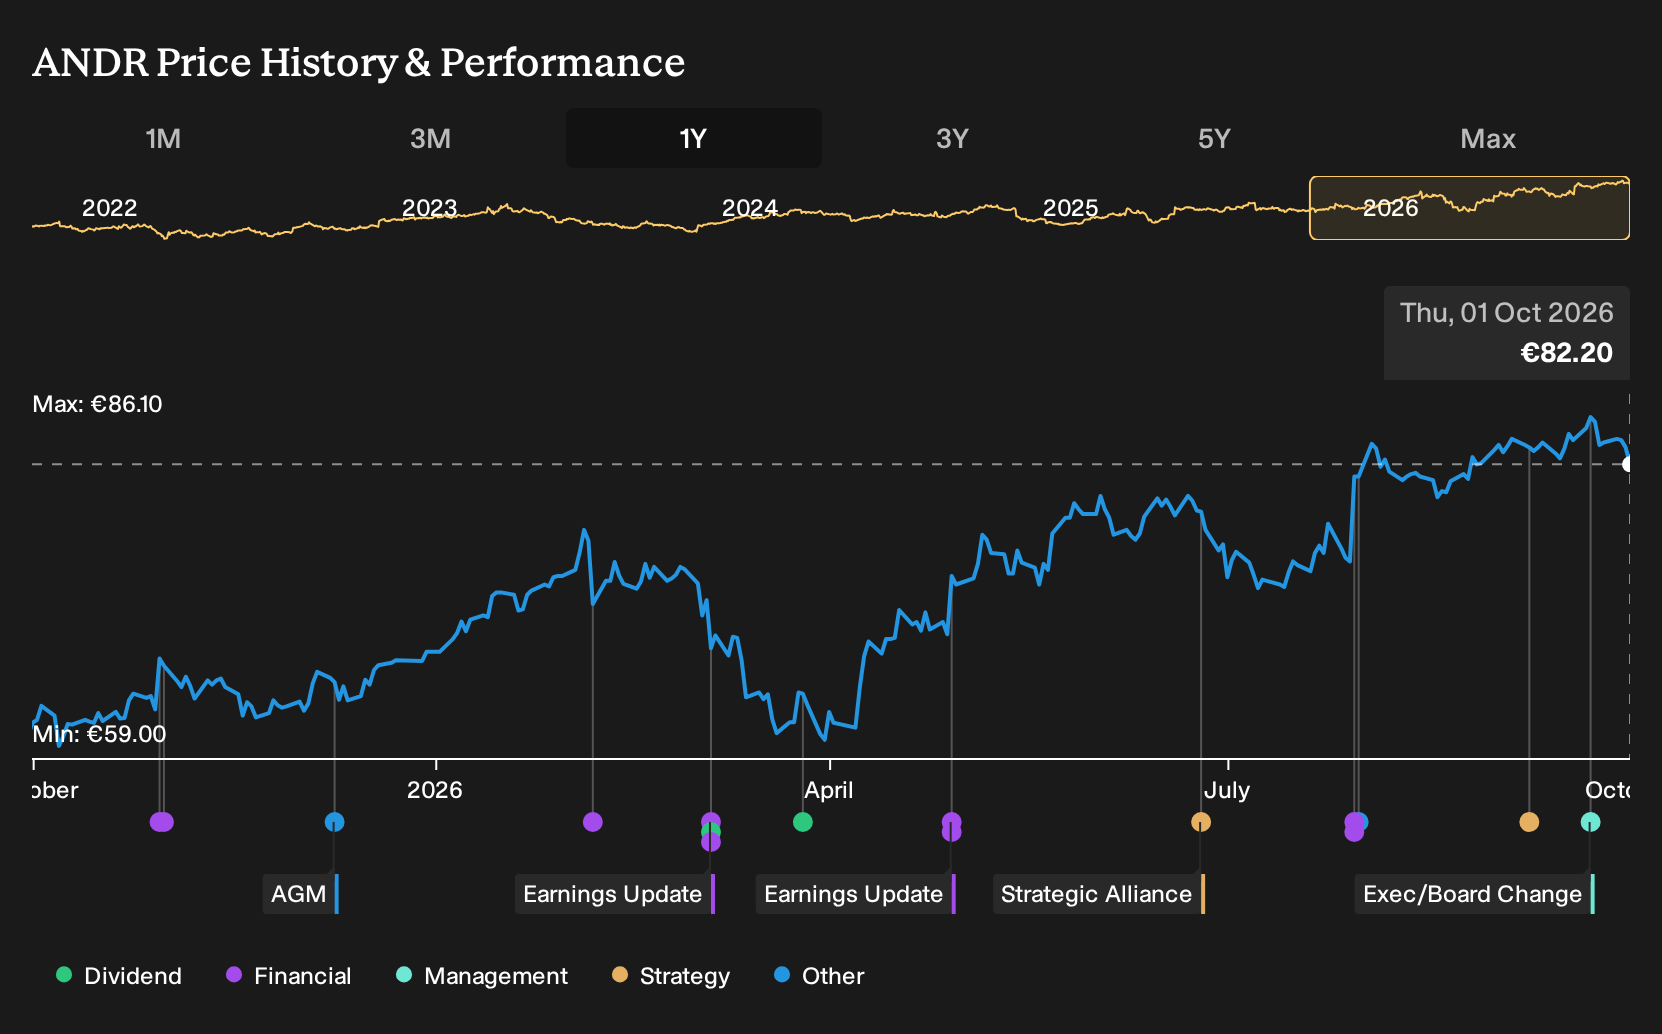
- Andritz announced that Executive Board member Dietmar Heinisser resigned with effect from 21 September 2026, stepping down from oversight of the Environment & Energy business area and Group Manufacturing Management after nearly three decades at the group.
- Heinisser’s exit removes a long-serving operator who helped build Andritz’s Paper Service activities. Executive Board Chair Joachim Schönbeck will temporarily consolidate responsibility for Environment & Energy and manufacturing under his remit.
- We will now look at how Andritz’s investment narrative could be influenced by Heinisser’s resignation from its Environment & Energy leadership role.
Scan how Andritz fits into the wider industrial reset by comparing it with a hand-picked list of solid balance sheet and fundamentals (207 results), which could be better placed for leadership shifts and capital-intensive projects.
Andritz Investment Narrative Recap
To own Andritz, you need to be comfortable with a project-heavy industrial group that relies on cyclical demand in Pulp & Paper, Metals, Hydropower, and Environment & Energy, supported by a record backlog and a rising share of services. The key near term swing factor is how efficiently that order book turns into revenue and cash against currency pressure and mixed end markets.
Heinisser’s exit matters most because it touches Environment & Energy, where customers have already been slow to commit to new projects, and where Andritz is pushing technologies tied to decarbonization. With Joachim Schönbeck taking over those responsibilities, the succession looks contained, so the bigger operational risk still sits in execution, restructuring, and any further softness in project decisions.
With no other recent announcements disclosed alongside this board change, the Heinisser resignation itself becomes the focal update for your thesis. It directly intersects with a segment that already carries risk from delayed orders in Pumps and Separation and from customer hesitancy around newer sustainable solutions.
Your question is whether Andritz can keep converting its large backlog and higher service mix into steadier earnings while absorbing leadership turnover in a sensitive division. The upside case leans on the existing project pipeline in Hydropower, Metals, and Pulp & Paper and on past capacity adjustments, while the bear case focuses on prolonged Environment & Energy weakness, FX headwinds, and integration and balance sheet strain from ongoing M&A.
Analysts expect Andritz to reach €9.9b in revenue and €693.3m in earnings by 2029. That outlook implies 7.0% yearly revenue growth and an earnings increase of about €227.8m from €465.5m today.
Discover how Andritz's fair value indicates a 12% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternative view on Andritz focuses on the risk that service and digital growth, especially around the Metris platform, disappoints. The most optimistic analysts were pencilling in revenue of about €10.3b and earnings near €820.4m by 2029. You can see how that upbeat story might be revisited after a leadership shakeup like Heinisser’s exit.
Explore 5 other Andritz fair value estimates, including one that suggests as much as 77% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Andritz research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Andritz. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Andritz's overall financial health at a glance.
Looking For More Investment Ideas Beyond Andritz?
If this Andritz update has you reassessing risk, it can help to widen the lens and compare it with other businesses that match your preferred style, whether that is stability, yield, or uncrowded opportunities.
The Simply Wall St Screener lets you do exactly that by filtering for balance sheet strength, income potential, or under-the-radar picks that still show solid fundamentals.
- If capital preservation sits high on your list, you can start with a shortlist of companies that score well on resilience and balance sheet quality through the 224 resilient stocks with low risk scores.
- If you care more about being paid while you wait, you can scan for higher yielding payers that still clear basic quality hurdles using the 159 dividend fortresses.
- If you prefer to hunt where fewer investors are looking, you can focus on smaller high quality firms that pair sound fundamentals with lighter coverage via the 617 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com