


Did Lithium Expansion Plans Just Shift SQM Stock's Investment Narrative?
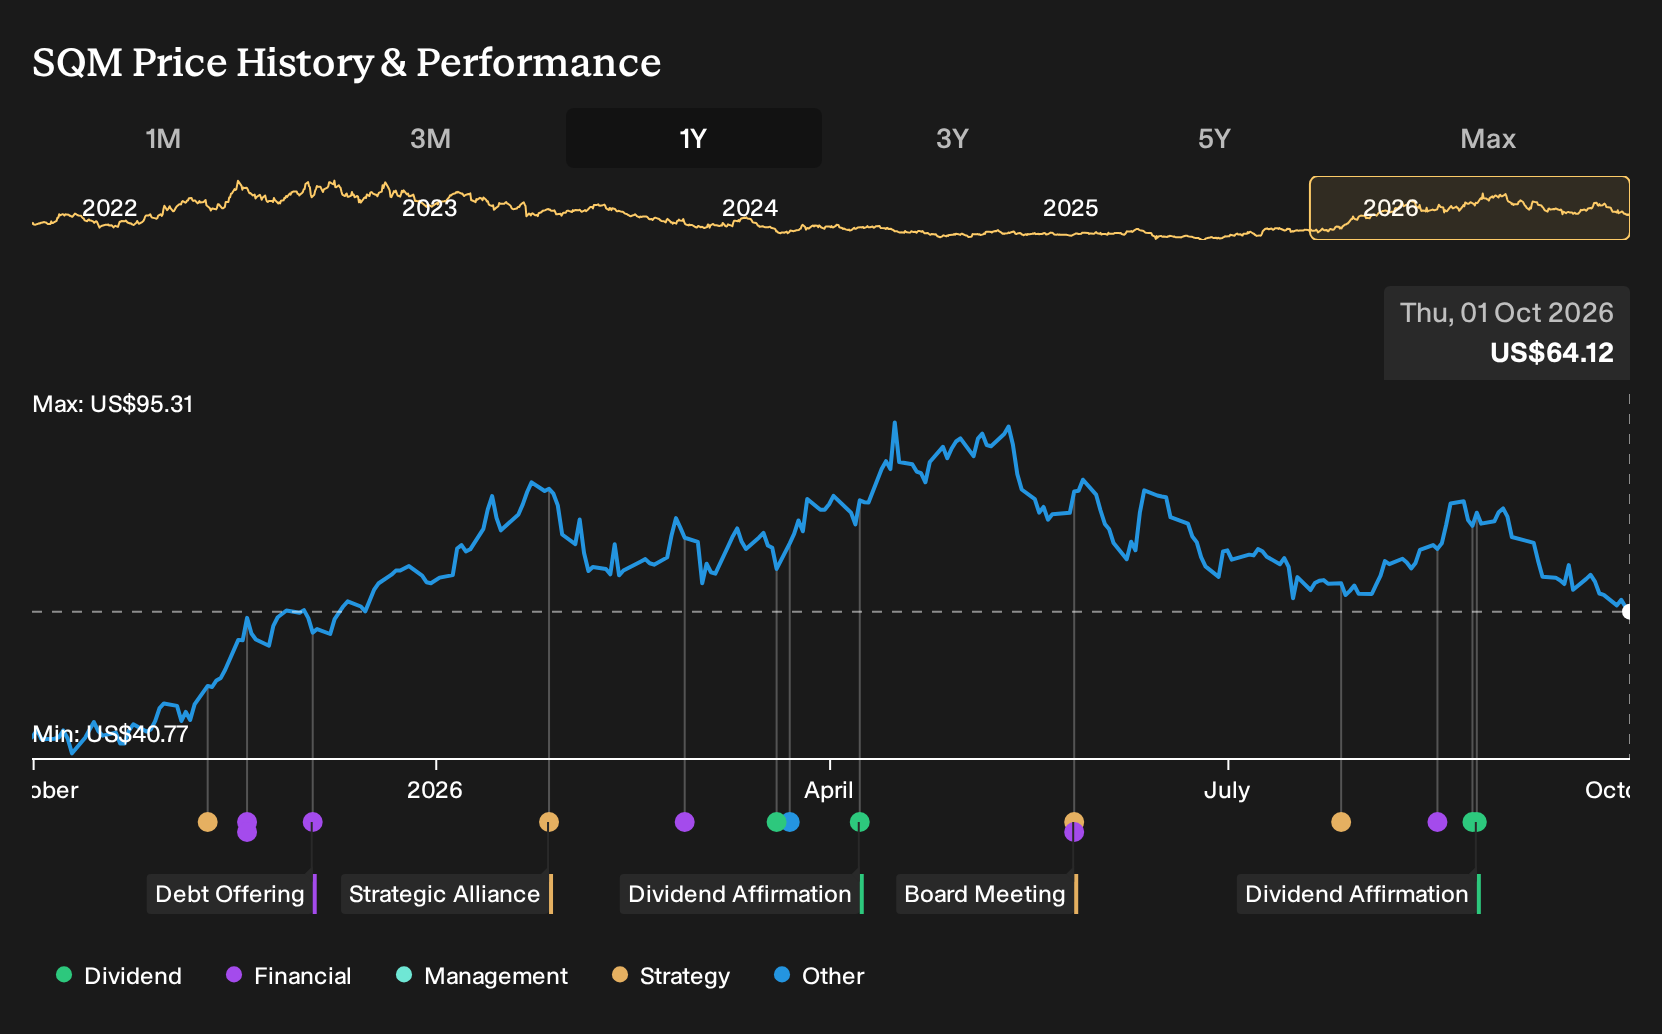
- Sociedad Química y Minera de Chile has recently drawn attention for its expanded lithium and specialty chemical capacity, with analysts using discounted cash flow models to assess how expected cash generation supports the current valuation.
- The key tension is between long-horizon lithium volume growth from new projects and exposure to volatile lithium pricing and evolving Chilean regulation, which together shape how durable the company’s cash flows may prove to be.
- We will look at how Sociedad Química y Minera de Chile's lithium expansion plans and regulatory exposure reshape the broader investment narrative.
Look beyond Sociedad Química y Minera de Chile and compare its setup with a curated group of 28 high quality undervalued stocks that also pair cash generation with balance sheet strength.
Sociedad Química y Minera de Chile Investment Narrative Recap
To own Sociedad Química y Minera de Chile, you need to be comfortable with a lithium driven story that depends on ramping production volumes and the firm staying near the low end of the cost curve. Recent share price swings do not change the near term swing factor. Pricing for lithium and iodine still drives how much of that capacity drops through to profit.
The biggest short term catalyst remains execution on lithium projects in Chile and Australia that can support higher sales volumes. The main near term risk is that lithium prices stay weak or contract terms reset lower, which would quickly feed into earnings and could make the current capex load feel heavy.
The most relevant backdrop for the recent price move is that Sociedad Química y Minera de Chile is investing heavily, with around US$1b of capex targeted each year, much of it pointed at growth initiatives such as Salar Futuro and Australian lithium assets. That spend is what underpins the long term volume story.
Those same programs raise the stakes. Any delay in Chilean approvals, partnership terms with Codelco, or project level cost overruns would hit free cash flow and could stretch the balance sheet. For you as a shareholder, the key question is whether the current discount to estimated fair value accurately reflects that execution and regulatory risk.
Sociedad Química y Minera de Chile's current setup assumes analysts' projections of US$8.4b in revenue and US$2.2b in earnings by 2029, which aligns with a forecast revenue growth rate of 16.7% per year. This implies earnings today of US$815.3m would need to rise by about US$1.4b to reach the 2029 consensus level.
Uncover why Sociedad Química y Minera de Chile's fair value indicates a 32% potential upside to its current price that could narrow quickly if sentiment shifts toward Sociedad Química y Minera de Chile.
Exploring Other Perspectives
One alternate view on Sociedad Química y Minera de Chile focuses on a possible lithium surplus rather than tight markets. In that story, the lowest analysts saw revenue sliding toward about US$5.7b and earnings easing to roughly US$1.2b by 2029. Those forecasts were set before this news, so you may see opinions adjust as fresh data becomes available.
Explore 4 other Sociedad Química y Minera de Chile fair value estimates, including one that suggests it could be worth just $74.96.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Sociedad Química y Minera de Chile research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Sociedad Química y Minera de Chile. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sociedad Química y Minera de Chile's overall financial health at a glance.
Looking For More Investment Ideas Beyond Sociedad Química y Minera de Chile?
If Sociedad Química y Minera de Chile has you thinking about where risk, balance sheets, and cash generation meet, it can help to line it up against other opportunities using the Simply Wall St Screener.
- If you want to focus on balance sheet strength first and work backward from there, start with a list of solid balance sheet and fundamentals (25 results) that already clear basic financial health checks.
- For investors who care most about paying a reasonable price for quality, compare Sociedad Química y Minera de Chile with a 28 high quality undervalued stocks that may offer a similar blend of fundamentals at different market prices.
- Income focused portfolios can take a different path and scan for mature, cash generative businesses by filtering for a 7 dividend fortresses that might complement a more growth oriented lithium exposure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com