


Conagra (CAG) Stock Looks Like A Bargain On Sales
Conagra Brands has seen its share price slide over recent years, and that kind of long stretch lower naturally raises a valuation question for investors who focus on what they are paying for the company’s sales. With the stock under pressure and the business still reporting meaningful revenue, the issue is whether the current price lines up with what its top line can reasonably support.
- Over the past 5 years, Conagra Brands' share price has fallen 50.2%, which puts extra focus on whether the revenue base justifies where the stock now trades.
- Recent results showed softer net sales in key retail categories alongside growth in foodservice and international operations, which can influence how investors think about the stability and mix of future sales that underpin any valuation built on revenue multiples.
- There is a second opinion on Conagra Brands worth weighing. See what analysts think Conagra Brands's shares could be worth.
For investors, the debate is whether Conagra Brands' current share price is adequately supported by its sales when judged against the Fair Ratio benchmark.
To see the same sales based valuation question applied across a broader set of companies, compare Conagra Brands with stocks in the 28 high quality undervalued stocks.
Is Conagra Brands Still Cheap on Sales?
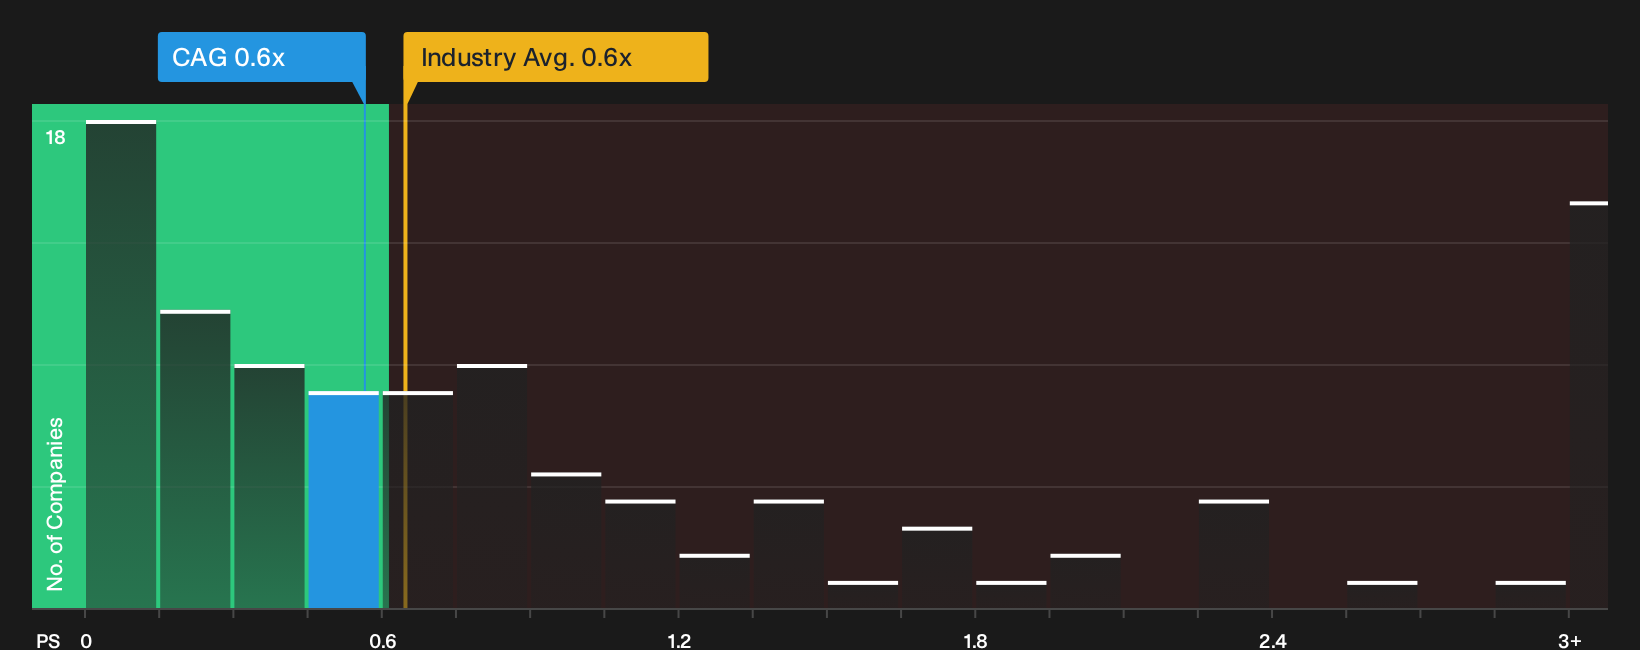
P/S works well for Conagra Brands because investors are weighing the value of its sales base against a pressured share price and mixed segment trends. The stock currently trades on a P/S ratio of 0.6x, which is very close to both the Food industry average of 0.6x and the peer group near 0.6x. This puts the business on roughly similar terms to comparable packaged food companies when you look only at revenue versus market value.
The Fair Ratio model, which adjusts the P/S benchmark for Conagra Brands' own scale, profitability profile and risk, points to a higher multiple than where the shares change hands today, so the current P/S level screens as undervalued on this framework. Because management reaffirmed its fiscal 2027 guidance despite the recent 1.4% net sales decline and segment mix shifts, the discount implied by the P/S ratio may draw attention from investors who focus on sales supported valuations. Explore the numbers behind Conagra Brands's P/S valuation.
The Conagra Brands Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Conagra Brands valuation question leaves off by spelling out which future paths for growth, margins and earnings would need to play out for the stock to be worth materially more or less than today’s price on the Community page. Rather than relying on a single P/S or DCF output, each narrative lays out the assumptions behind its view of fair value so you can track those against actual results over time.
One of the top community narratives on Conagra Brands: 8% undervalued
"The main thing that has to go right is Conagra Brands executing on portfolio simplification and supply chain modernization, including SKU rationalization…"
Discover why this Narrative puts Conagra Brands at 8% undervalued.
One more piece of the Conagra Brands puzzle still sits offstage
Everything so far has focused on what Conagra Brands looks like today, but professional coverage also sketches out where earnings and sales are expected to head over the next few years. Explore where analysts expect Conagra Brands to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com