


Ecolab (ECL) Could Be 17% Undervalued Following Its Recent Share Price Dip
Ecolab (ECL) has been drawing attention after recent trading left the stock modestly lower over the past month and past 3 months, despite positive annual revenue and net income growth.
Over the past year, Ecolab’s share price has been relatively steady overall, with a modest year to date share price gain of 3.3%. This contrasts with a recent 90 day share price decline of 4.3%, which suggests momentum has cooled, even though the 3 year total shareholder return of 66.1% remains strong in the background.
Compare Ecolab’s recent loss of momentum with a hand picked group of resilient stocks by scanning the 31 resilient stocks with low risk scores that aim to keep drawdowns in check.
Ecolab now sits at an awkward intersection of solid revenue and profit growth and a share price that has cooled. Does that recent wobble still leave the stock looking stretched, or is it starting to look reasonable on valuation?
Most Popular Narrative: 16.5% Undervalued
Ecolab’s most followed valuation storyline puts fair value at about $324.95 per share versus the recent $271.26 close. This frames the current lull in the share price as a potential discount rather than a reset.
Growth engines such as Global High Tech, Life Sciences, Digital and Pest, which now contribute roughly a quarter of sales and include Global High Tech targets for more than 25% annual growth to US$4b of sales and 25% operating margin by 2030, are expected to drive faster organic revenue growth and support the company’s goal of at least 20% operating margin and higher ROIC.
See why 49 investors see Ecolab as 17% undervalued.
Result: Fair Value of $324.95 (UNDERVALUED)
Still, the whole narrative on Ecolab can unravel if heavy industrial demand weakens further, or if tariffs and higher input costs squeeze pricing power and margins.
Find out about the key risks to this Ecolab narrative.
Another View: Ecolab Looks Pricey On Earnings
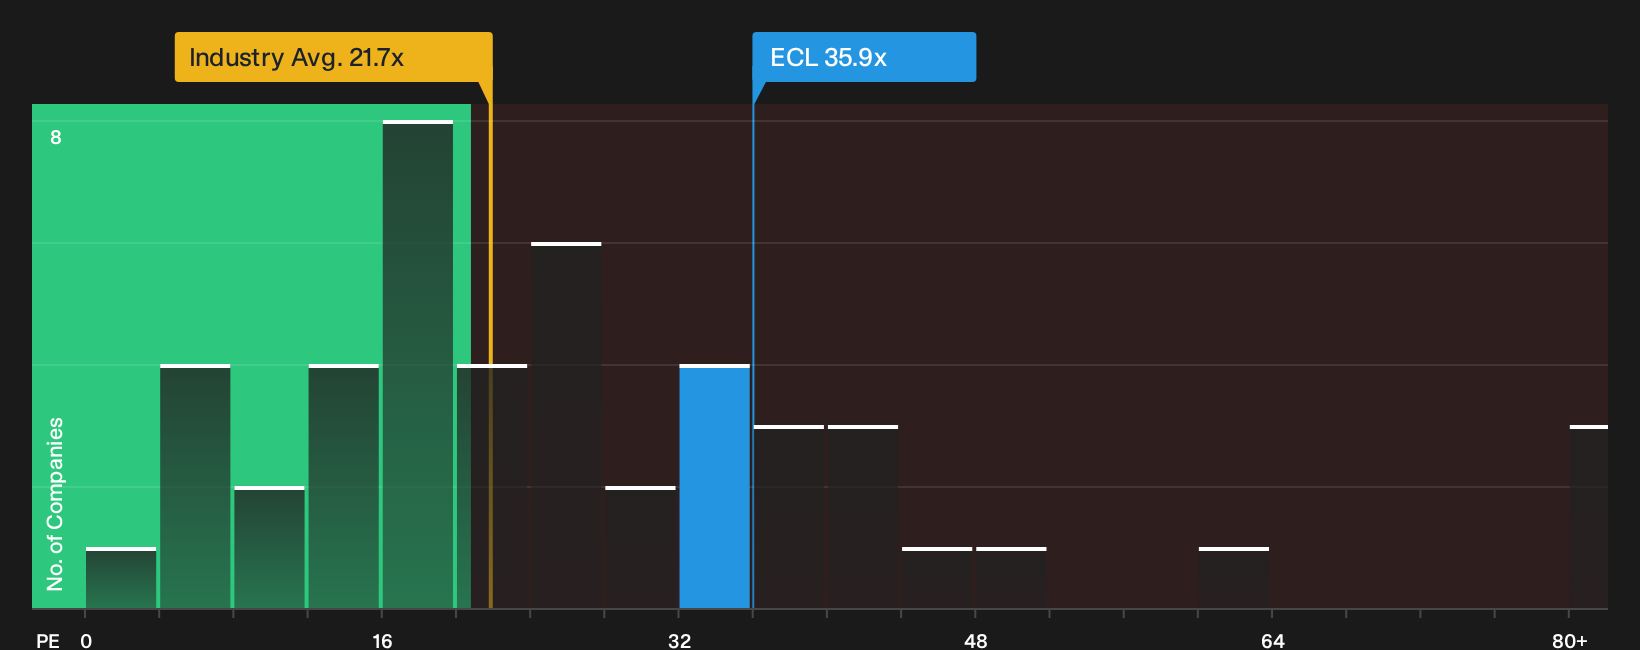
On the flip side of that 16.5% “undervalued” fair value story, Ecolab trades on a P/E of 35.9x. That is far above the US Chemicals industry on 21.7x, the peer group on 19x, and also above a fair ratio of 23.6x that the market could move toward.
For you as a shareholder, that gap means there is little room for error. If sentiment cools or expectations reset, the share price might drift closer to that fair ratio level rather than away from it. Which version of Ecolab’s valuation feels more realistic to you right now?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mixed sentiment around Ecolab leaves you on the fence, move quickly, stress test the numbers yourself, and weigh both sides. To round out that view, check the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Ecolab?
If Ecolab has you thinking harder about valuation and risk, broaden your watchlist now so you are not relying on a single storyline.
- Target stronger balance sheets and steadier fundamentals by scanning the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities that pair quality with attractive entry points using the 28 high quality undervalued stocks.
- Prioritize income potential and cash returns by reviewing the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com