


LyondellBasell (LYB) Stock May Be Undervalued Even After Its 30% Rally
LyondellBasell Industries has had a choppy few months, yet the shares are still up strongly year to date. This puts fresh attention on what investors are paying for its sales today. With the stock pulling back from recent levels, the key issue for readers is how the current price lines up with the revenue base of this large chemicals producer.
- LyondellBasell Industries is up 30.2% year to date, which raises the question of whether the share price is now stretching the value of its existing sales or simply catching up to them.
- The group’s model is heavily tied to converting commodity-like products into higher value materials, so pricing power and volume resilience can be crucial for how much investors are willing to pay for each dollar of revenue.
- Your read on LyondellBasell Industries is one view; the desks covering it have another. See what analysts think LyondellBasell Industries's shares could be worth.
The issue now is whether the current share price of LyondellBasell Industries is adequately supported by its sales when judged against the Fair Ratio benchmark.
If you are weighing whether LyondellBasell Industries' current P/S multiple feels rich or reasonable, it can help to compare it with a broader group using 28 high quality undervalued stocks
Is LyondellBasell Industries Still Cheap on Sales?
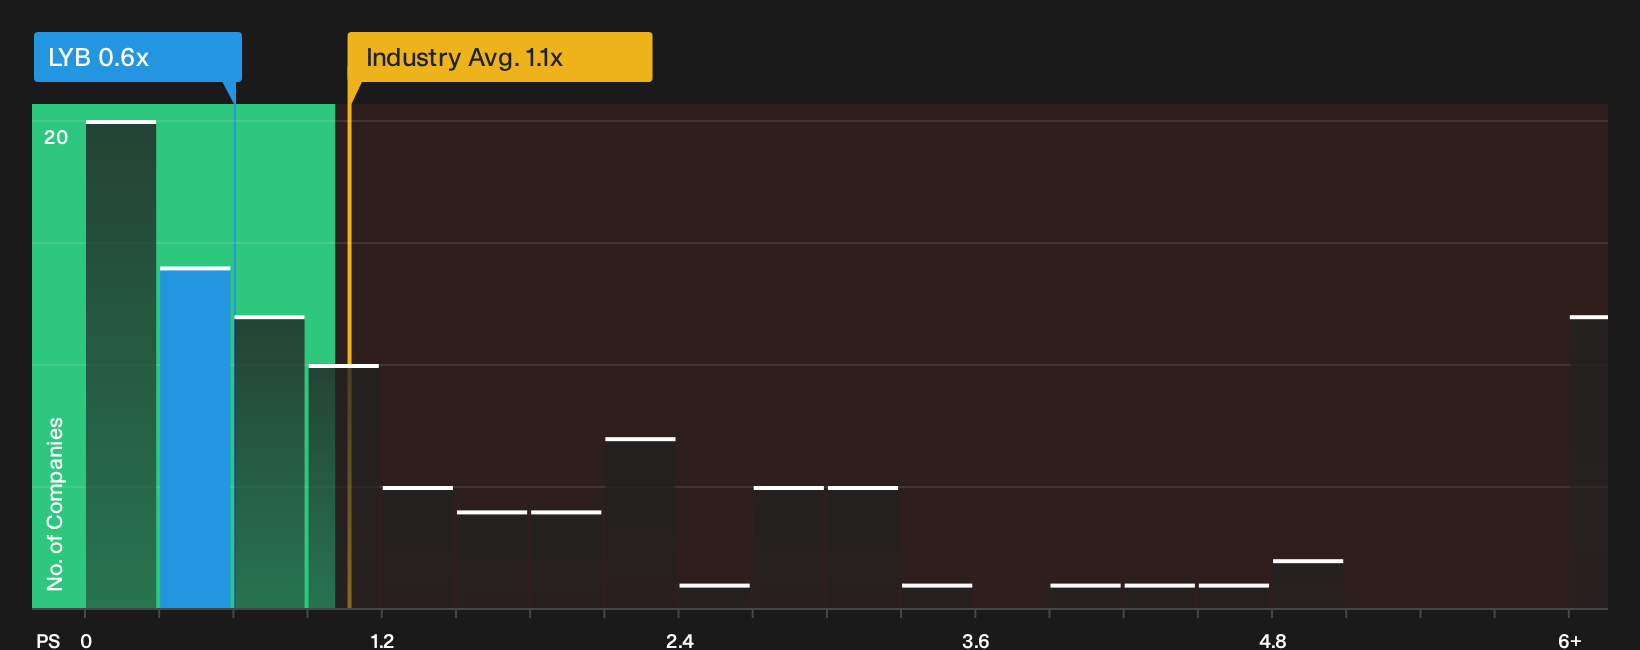
P/S is a useful way to think about LyondellBasell Industries because the business is built on turning large volumes of basic chemicals into higher value products, so what you pay for each dollar of sales really matters. At a current P/S of 0.6x, the stock is trading well below both the Chemicals industry average of 1.1x and the peer group at about 1.2x. This means the market is assigning a relatively low price tag to its revenue stream.
The Fair Ratio framework, which estimates the multiple you might expect given LyondellBasell Industries' economics and risk profile rather than simple averages, points to a higher P/S than where the shares currently change hands. That gap indicates the market price is below what this tailored benchmark would suggest for the sales base, so anyone looking at the recent rally still sees a stock that screens as undervalued on revenue against this lens. Explore the numbers behind LyondellBasell Industries's P/S valuation.
The LyondellBasell Industries Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for LyondellBasell Industries pick up where the P/S puzzle leaves off. They spell out which future paths for LyondellBasell Industries' growth, margins and earnings would need to hold for the stock to look meaningfully mispriced against today's quotation, using concrete views on how its economics and risk profile might evolve that you can revisit as fresh information comes through.
Bullish and bearish voices on LyondellBasell Industries are looking at the same cash and circular plastics story but drawing different conclusions on how much is already reflected in the current valuation.
Bull case: 32% undervalued
"Progress at MoReTec 1, where construction is on schedule for a late 2027 startup and most output is already committed to brand owners..."
Discover why this Narrative puts LyondellBasell Industries at 32% undervalued.
Bear case: roughly fairly valued
"The decision to cut the quarterly dividend by 50% in early 2026 to protect the balance sheet despite strong reported EBITDA and high recent cash conversion indicates that management still sees balance sheet fragility..."
Explore why this Narrative puts LyondellBasell Industries at roughly fairly valued.
LyondellBasell Industries: the share price is only one piece of the real decision
Before you stop at the multiple and the story, it is worth asking who is actually pulling the levers at LyondellBasell Industries and how their pay packets line up with your interests. See who runs LyondellBasell Industries and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com