


Did Fraud Defense Expansion Just Shift PayPal (PYPL) Stock Investment Narrative?
- PayPal Holdings has expanded its fraud and risk capabilities through integration with IPQualityScore across platforms such as Alloy, Shopify and Stripe, feeding real time intelligence into transaction checks, account screening and security workflows.
- This push into embedded fraud services signals PayPal’s effort to reposition itself as a broader digital commerce infrastructure provider rather than a pure payments processor, with product features like Pay Later and holiday shopping insights reinforcing that shift.
- We will now look at how PayPal’s deeper fraud intelligence integration could influence the wider investment narrative around its commerce platform.
What Is PayPal Holdings' Investment Narrative?
To own PayPal Holdings today, you need to believe this is more than a beaten up payments stock. The thesis rests on a large, global transaction network that can keep monetising both sides of the checkout, even if revenue growth around 4.1% a year is not rapid. The IPQualityScore integration fits that story. It pushes PayPal further into embedded fraud intelligence that can make its rails stickier for merchants already using platforms like Shopify and Stripe.
In the short term, the real swing factors still look operational. Execution on new products like Pay Later, controlling losses and protecting a 24.7% return on equity matter more than any one partnership headline. The share price is down sharply over 5 years and has underperformed the wider US market over 1 year, so sentiment is fragile. Fraud tools and holiday shopping insights may help demand and pricing power at the margin, but they do not erase the risk that earnings are forecast to decline slightly and that revenue growth is slower than many US companies.
Yet for all the appeal of a low 9.3x P/E and a stock trading well below one fair value estimate, there is a hitch that could derail that comfort if ...
There's only one way to know the right time to buy, sell or hold PayPal Holdings. Head to Simply Wall St's company report for the latest analysis of PayPal Holdings's Fair Value.
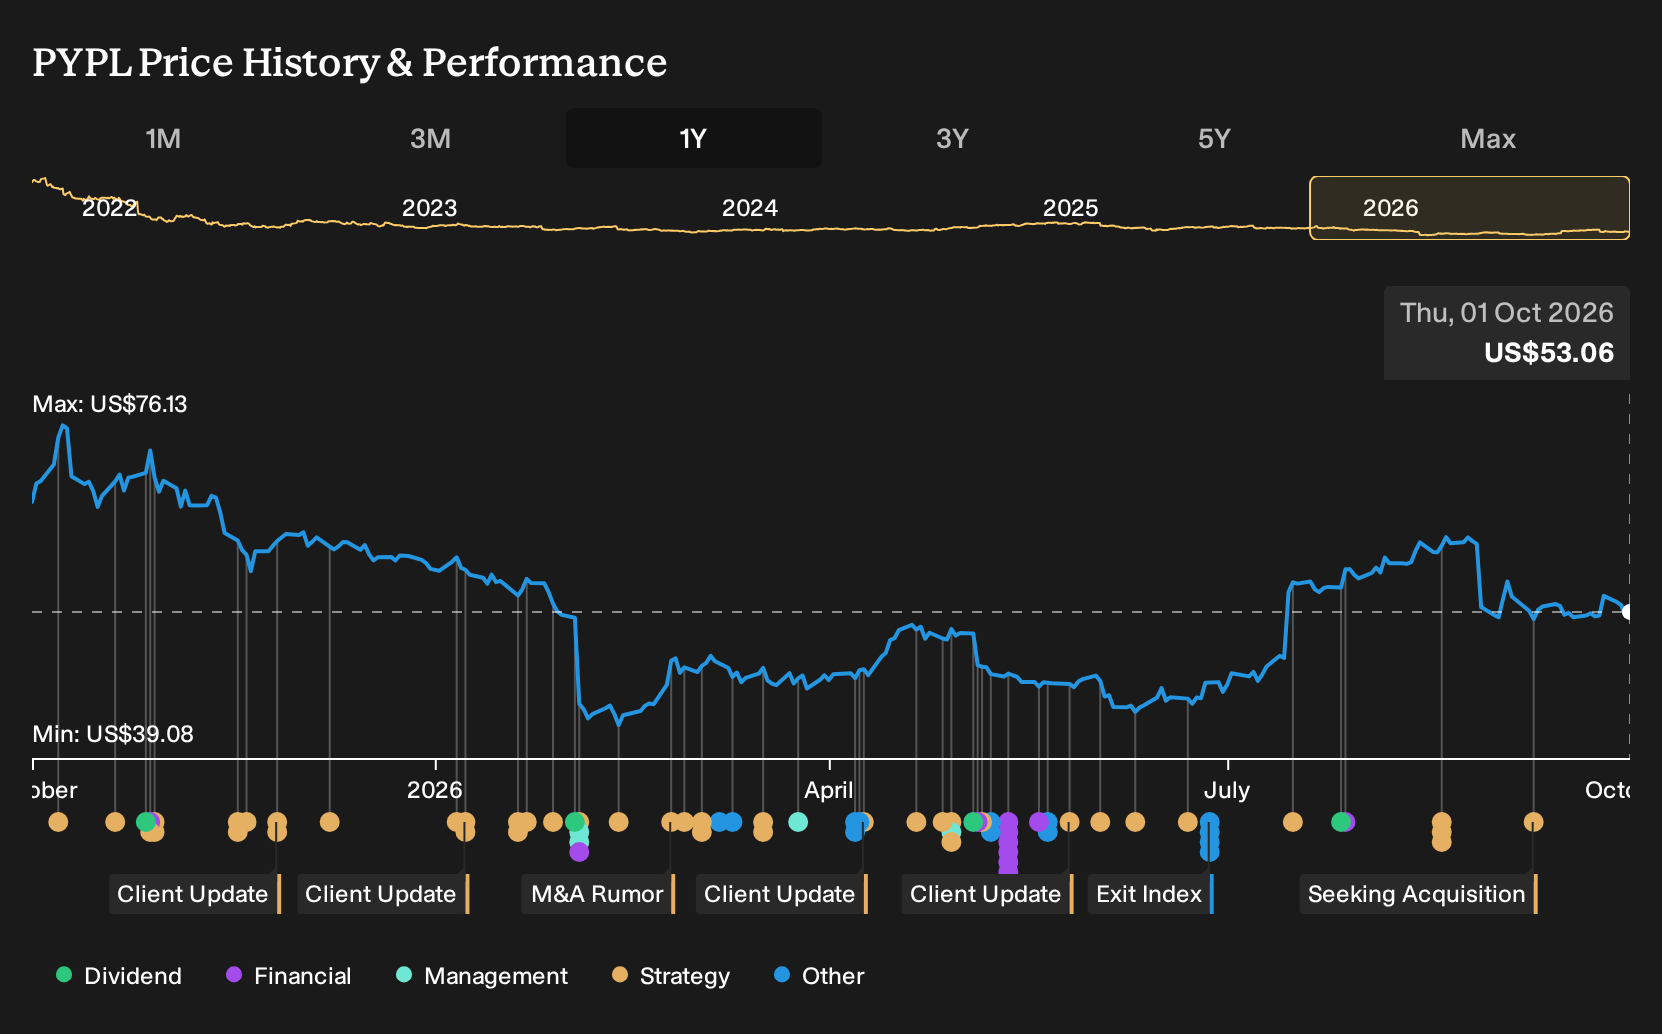
Exploring Other Perspectives
One alternate view of PayPal focuses heavily on margin risk. The most cautious analysts assume revenue would rise only about 2.9% a year and profits would slip from US$4.9b to US$3.9b by 2029. That is a far gloomier story than consensus. You can use the new fraud integration news to reassess which camp you align with.
Explore 29 other PayPal Holdings fair value estimates, including one that suggests it could be worth just $56.92.
The Verdict Is Yours
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your PayPal Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for PayPal Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easy to evaluate PayPal Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond PayPal Holdings?
Once you have formed a view on PayPal Holdings, it can help to broaden your watchlist with other businesses that fit clear financial themes. The Simply Wall St Screener lets you filter for companies by valuation, balance sheet strength and risk profile so you can build a line up that matches your own playbook.
- If you want potential mispricing on your side, start with companies that appear cheap on quality and fundamentals by reviewing 28 high quality undervalued stocks.
- For investors who care most about resilience, focus on businesses with strong finances and low risk scores by scanning the 31 resilient stocks with low risk scores.
- If you prefer rock solid finances as your foundation, build a watchlist from the list of solid balance sheet and fundamentals (25 results) to see which companies combine balance sheet strength with underlying fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com