


CarGurus (CARG) Stock May Be Undervalued As VINMax Launch Draws Focus
CarGurus has seen its share price move around over the past few years, and the big question now is whether the current US$29.73 level is justified by the earnings that support it. Recent trading pressure puts that earnings story under a brighter light for anyone considering the stock today.
- Over the past 3 years the share price has risen 73.6%, which puts real weight on whether the underlying profit engine can sustain that kind of value creation.
- The launch of VINMax, which uses CarGurus’ market data and AI tools to help dealers move vehicles faster, can shape expectations for future earnings by influencing how effectively the platform converts its traffic and data into monetizable services.
- Your read on CarGurus is one view; the desks covering it have another. See what analysts think CarGurus's shares could be worth.
The issue now is whether that recent price of US$29.73 still lines up with what CarGurus actually earns, once you judge it through the lens of its earnings power.
If you want to cross check CarGurus against other opportunities built around clear financial filters, a focused screen of 28 high quality undervalued stocks can be a useful next stop in your research.
Is CarGurus a Bargain on Earnings?
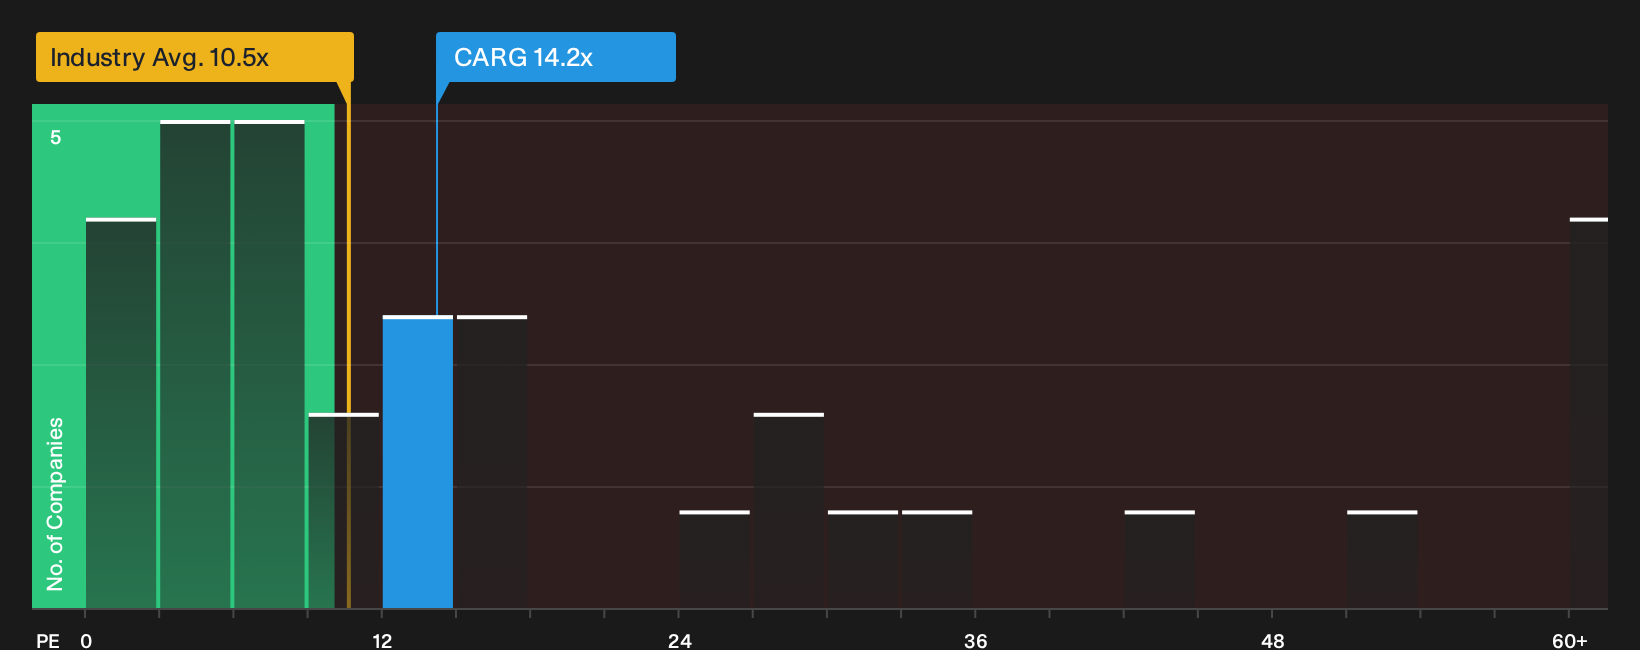
The P/E ratio suits CarGurus because earnings are a central part of how investors frame the business today. On this measure, CarGurus trades at roughly 14.2x earnings, which is very close to the 14.4x peer average and higher than the broader Interactive Media and Services group at about 10.5x. That combination points to a stock that is priced in line with similar platforms rather than one that is being treated as either a clear bargain or an outlier on simple earnings optics.
Because VINMax has sharpened the story around data driven dealer tools, it matters that the current P/E also sits below what a more tailored fair multiple model suggests for CarGurus. The fair multiple reflects factors like growth outlook, profitability profile and risk, so a lower headline P/E hints that the market is not fully paying up for those traits yet. For anyone weighing the shares today, the key question is whether that gap reflects caution that will persist or a window where expectations trail the underlying earnings power of the business. Explore the numbers behind CarGurus's P/E valuation.
The CarGurus Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for CarGurus connect the earnings puzzle above to specific paths the business could follow next. Each scenario spells out what would need to happen to CarGurus' growth, margins and risk profile for the stock to be worth materially more or less than today, and ties that view to a number you can revisit on the Community page as new information comes through.
One of the top community narratives on CarGurus: 28% undervalued
"Sharpened focus on high-margin technology and scalable offerings, combined with winding down volatile operations, is driving improved profitability and marketplace differentiation..."
Discover why this Narrative puts CarGurus at 28% undervalued.
CarGurus’ valuation still leaves one crucial risk question hanging
CarGurus can look reasonable on earnings, yet the research checks behind this article also flag specific risk markers that could change how you weigh the whole story. Take a closer look at 2 warning signs before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com