


Is TC Energy (TSX:TRP) Undervalued Following Coastal GasLink Phase 2 Expansion?
TC Energy (TSX:TRP) is pushing ahead with Coastal GasLink Phase 2 after LNG Canada approved its own expansion, nearly doubling pipeline capacity and tying the business more tightly to future LNG export flows.
Recent trading has been choppy for TC Energy, with the share price slipping 5.01% over the past 30 days and 11.93% over 90 days. At the same time, the year-to-date share price return sits at 8.54% and the 1-year total shareholder return is 14.70%, within a much larger 3-year total shareholder return of about 13x, which reflects how investors have previously priced in long-term pipeline and LNG projects.
Scan beyond TC Energy and evaluate other pipeline and energy infrastructure players that could benefit from similar long-horizon projects with the 39 power grid technology and infrastructure stocks
TC Energy now has a major LNG-linked growth project moving ahead, yet the share price has slipped in recent months. Does that combination still tilt the risk reward in favour of new buyers, or has the easy money already been made?
Most Popular Narrative: 16% Undervalued
TC Energy last closed at CA$83.41, while the most followed narrative pegs fair value at about CA$98.78, which frames today’s pullback as a potential mismatch between price and the business tied to LNG and data centre demand.
Active balance sheet optimization, marked by successful project execution, deleveraging targets (aiming for 4.75x by 2026), and disciplined capital allocation, improves financial resilience and could support sustained or growing dividends, which may positively impact earnings and shareholder value.
See why 67 investors see TC Energy as 16% undervalued.
Result: Fair Value of CA$98.78 (UNDERVALUED)
Still, if long term gas demand softens or regulators push harder on carbon and project approvals, that 16% valuation gap on TC Energy could shrink quickly.
Find out about the key risks to this TC Energy narrative.
Another View: TC Energy On Earnings Multiples
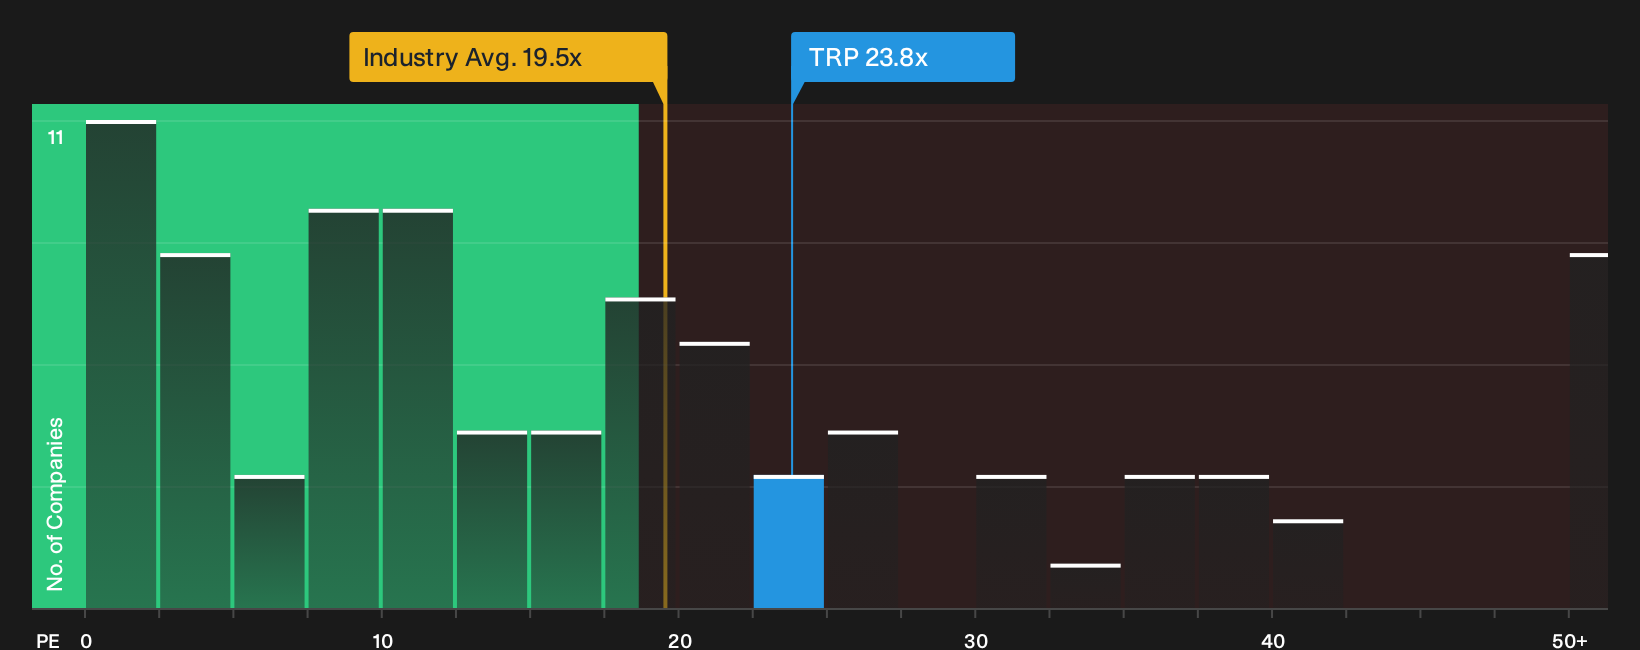
There is a very different signal when you look at TC Energy through its P/E ratio instead of the CA$98.78 fair value narrative. The stock trades on about 23.8x earnings, above the Canadian Oil and Gas group at 19.5x and above an estimated fair ratio of 21.3x.
That points to a richer tag than the wider industry and even its own fair ratio suggests. This can mean less room for error if future cash flows or margins fall short of current expectations. For an investor weighing new money today, the key question is whether this represents a quality premium or a sign that upside could be limited from here.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around TC Energy can either be a warning or an opening, so move quickly and stress test the full picture for yourself with 1 key reward and 2 important warning signs
Hunt For Your Next Idea Beyond TC Energy
TC Energy might be front of mind today, but your portfolio may benefit from a wider bench of ideas that align with different income, quality, and risk goals.
- Target resilient compounders by scanning a list of solid balance sheet and fundamentals (7 results) to help you avoid fragile businesses before trouble shows up in headlines.
- Pursue value opportunities with a 5 high quality undervalued stocks that highlights companies where fundamentals and price appear out of sync.
- Strengthen your income stream through a 1 dividend fortresses focused on higher-yield plays that also consider durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com