


What You Can Learn From Advanced Micro Devices 263% Gain
If one contract captured how 2026 reshaped Advanced Micro Devices, it was the five year, multi gigawatt MI450 GPU deal with Meta that turned a single product line into a long dated AI infrastructure commitment. For Advanced Micro Devices shareholders, the return over the past year was 262.8%, including dividends. If you were weighing an investment decision back on 2025-10-01, what had to be on your checklist to support that level of optimism around AI and data center exposure?
The useful thing about a Narrative is that the reasoning is checkable: the assumptions sit beside the argument, and together they imply an estimated Fair Value you can disagree with.
Advanced Micro Devices is not the only name tied to this theme. Zero in on 90 AI infrastructure stocks and compare how each one is priced.
The Two Stories Investors Were Arguing About On Advanced Micro Devices
The shares cost US$164 at the start of the period, which meant you had to decide what kind of future you believed Advanced Micro Devices was gearing up for in AI and data centers.
The bullish narrative set fair value at US$185, based on assumptions like 20.3% revenue growth and a future P/E of 43.6x. Supporters leaned on the idea that AI accelerators and data center CPUs could expand margins toward 17.8% over a 3 year window.
The bearish narrative anchored fair value at US$118. That view accepted ongoing growth yet focused on export restrictions on products such as MI308 and the risk that dependence on third party manufacturing would squeeze profitability.
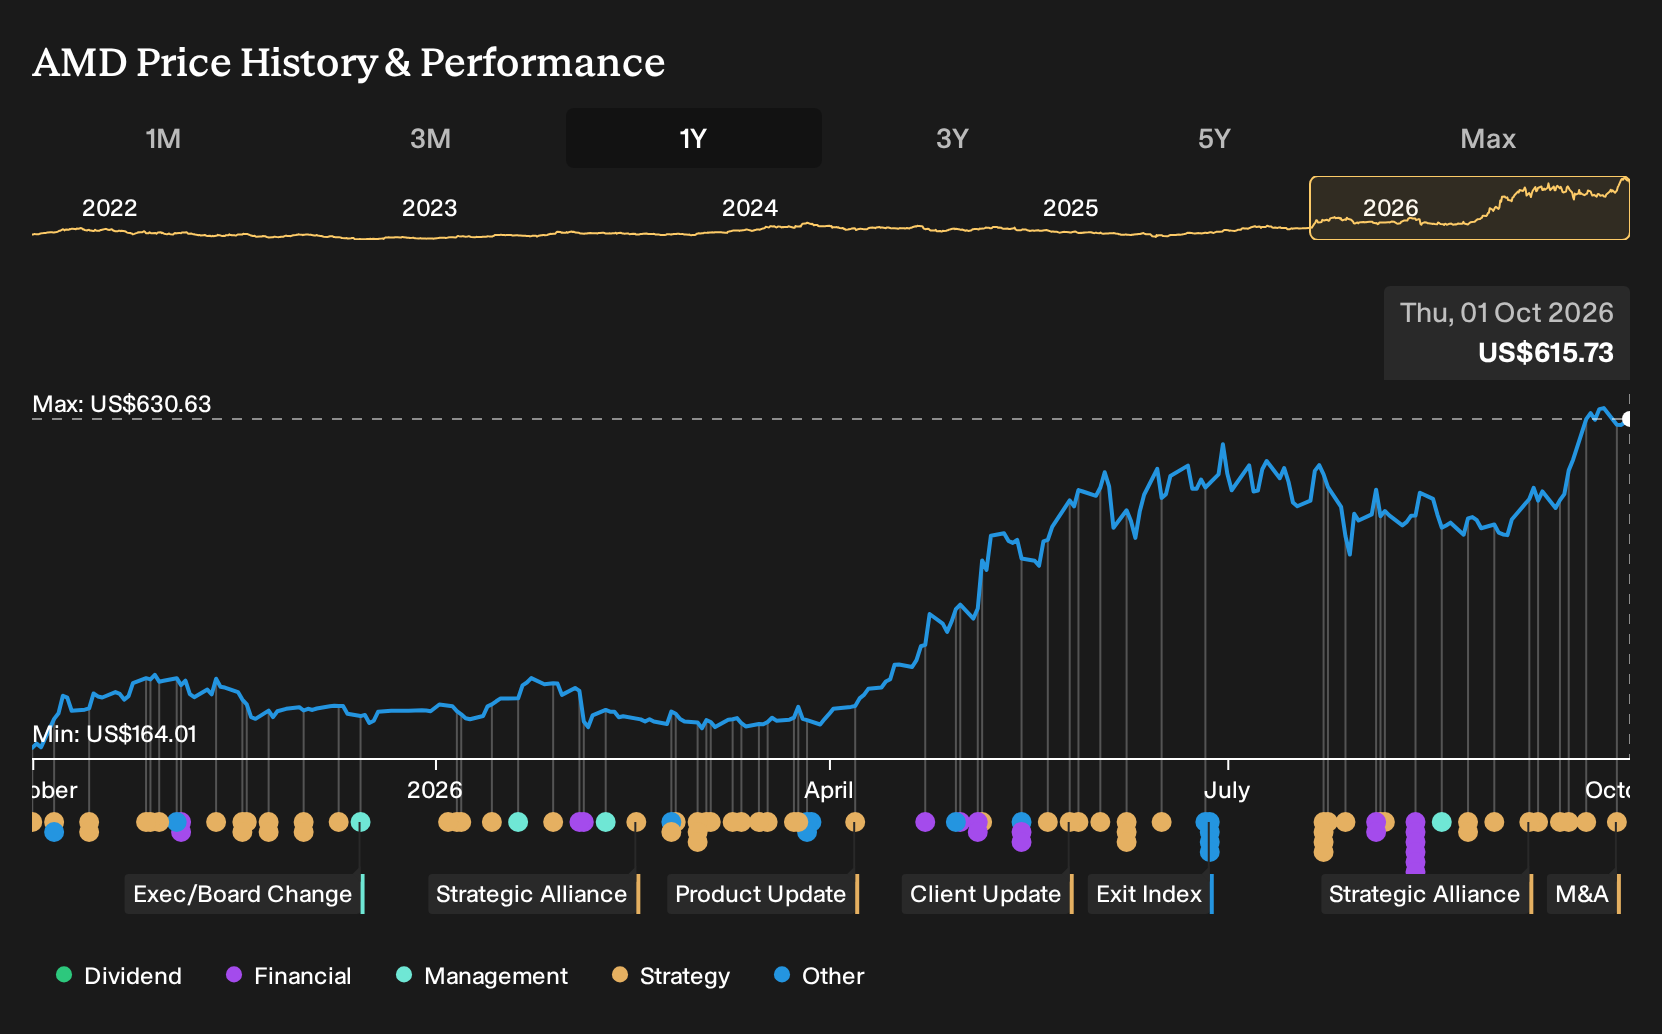
What The Results Changed For The Advanced Micro Devices Thesis
Advanced Micro Devices reported Q2 2026 revenue of US$11.54b and net income of US$2.31b. This compared with US$7.69b and US$0.77b a year earlier, with net margin increasing from 10.0% to 20.0%. The surge in AI data center demand and long-dated MI450 and Helios commitments supported the optimistic case, although export and supply risks remained.
The takeaway is straightforward: when an investment thesis relies on future AI and data center profitability, it is important to test it against actual segment revenue, reported net margin, and contract scale rather than relying solely on analyst enthusiasm.
What Advanced Micro Devices' Run Up To US$616 Already Assumes
Advanced Micro Devices now trades at US$616, far above where the story began a year ago. The current narrative places fair value below that quote and argues that the market price already incorporates an ambitious AI infrastructure trajectory.
This narrative leans on AI data center momentum and partnerships, yet still treats valuation as demanding. For today’s level to be maintained, a buyer would need to be comfortable with assumptions that AMD sustains rapid AI infrastructure growth while navigating export controls, higher onshore manufacturing costs, and competition in GPUs.
"AMD has evolved into a player in AI and enterprise compute, supported by its position in CPUs (EPYC) and a growing presence in GPUs (Instinct MI series). With revenue and earnings growth, recent analyst upgrades, and a valuation that some compare to peers, AMD is viewed by some as an exposure to AI infrastructure."
One Narrative disagrees with today's price. → See where this Narrative says Advanced Micro Devices should trade
Another Path Around AMD's AI Bet
Advanced Micro Devices puts your attention on AI hardware and data centers. Step sideways and a different angle appears.
The same buyers also look for AI systems with tightly integrated software. They want a full stack that can turn costly racks into productive tools quickly.
One major chip designer centers its strategy on that bundled approach. It links compute hardware to its own AI software ecosystem and keeps customers building on its platform.
If that model keeps winning budget share, your AMD thesis may sit beside a rival story, not above it.
That argument has a Narrative and a number behind it. → See the company one Narrative values 47% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com