


Has Weibo (WB) Fallen Far Enough To Look Undervalued?
Weibo has seen its share price fall sharply in recent years, which puts a spotlight on whether the current US$6.35 level is actually supported by the earnings the business is generating. The question now is whether that weaker share performance lines up with what the income statement says about the company.
- Over the past 5 years the stock has fallen 81.5%, which raises the issue of whether the market is now being too pessimistic or simply catching up with the earnings reality.
- The business model still leans heavily on monetising its user base through advertising and related services, so any shift in engagement, pricing power or cost control can feed directly into profit quality and the value investors place on those earnings.
- There is a second opinion on Weibo worth weighing. See what analysts think Weibo's shares could be worth.
For investors, the debate is whether the current share price is a fair reflection of Weibo's earnings today and the profit stream those earnings may support over time.
If you are weighing whether Weibo's earnings justify its current share price, it can help to compare that story with a wider group of 28 high quality undervalued stocks.
Is Weibo Still Cheap on Earnings?
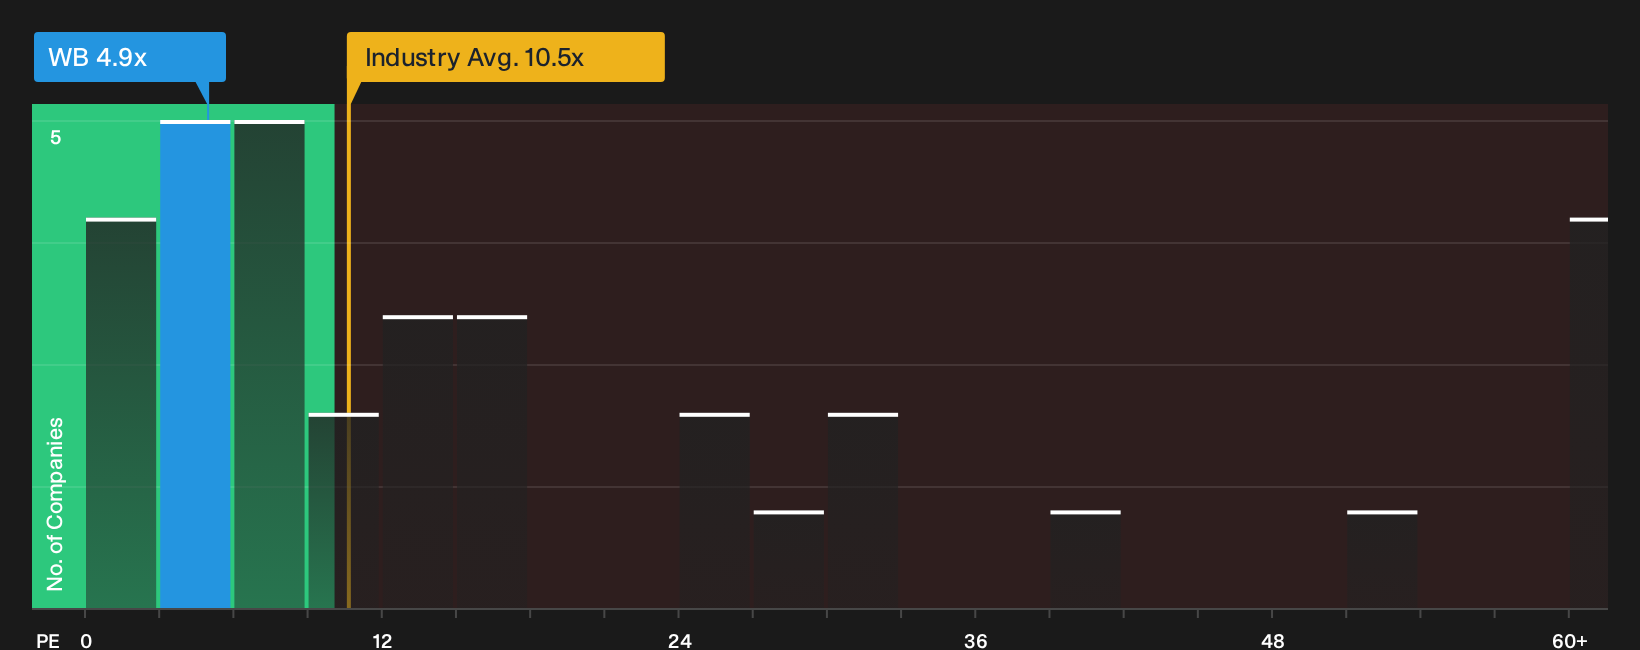
The P/E ratio is a useful lens here because Weibo is an established, profit-making platform with earnings that investors can actually price. On this measure, the stock trades on about 4.9x current earnings, which is less than half the Interactive Media and Services industry average of roughly 10.5x and also below the broader peer group near 11.3x. That gap indicates that the market is attaching a lower price tag to each dollar of profit than it does for many comparable online media businesses.
The Fair Ratio model, which blends factors like Weibo's profitability, sector, size and risk profile into a tailored benchmark, points to a higher multiple than where the shares change hands today. That places the current 4.9x P/E in undervalued territory on this framework. Investors still need to weigh how durable those earnings are and what risks might be keeping sentiment muted at this level. Explore the numbers behind Weibo's P/E valuation.
The Weibo Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St extend the Weibo valuation puzzle by spelling out what kind of future earnings path, profit margins and growth mix would need to hold for the shares to be worth meaningfully more or less than today’s price. Where a ratio or model gives you a single number, these scenarios unpack the assumptions sitting underneath it so you can track how Weibo's actual progress lines up over time.
One of the top community narratives on Weibo: roughly fairly valued
"The numbers imply that at an enterprise value close to its net cash and an EV or FCF multiple of about 2.26x, the current share price treats Weibo's core operating business as worth little more than zero..."
Discover why this Narrative puts Weibo at roughly fairly valued.
Before acting on Weibo’s valuation, look at who is steering the ship
Price multiples tell only part of the story, because how the leaders are selected, rewarded and aligned with shareholder outcomes can heavily influence how those earnings are treated over time. See who runs Weibo and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com