


Guidance Raise Change The Bull Case For Norwegian Cruise Line Stock?
- Norwegian Cruise Line Holdings reported that third quarter results are tracking above its prior guidance, reaffirmed its full year 2026 outlook, and highlighted record booked occupancy and pricing for 2027 with bookings for 2028 already running ahead of the prior year.
- The company is also reshaping its balance sheet through a proposed US$750 million senior notes offering due 2031. The offering is aimed at refinancing higher coupon 2028 debt and term loans, which could materially influence its interest expense profile and financial flexibility.
- We will now look at how Norwegian Cruise Line Holdings' stronger than guided third quarter shapes the broader investment narrative around the business.
Compare Norwegian Cruise Line Holdings' momentum and balance sheet rebuild with other travel and leisure operators by scanning a curated set of 19 high quality undiscovered gems that may still be off most investors' radar.
Norwegian Cruise Line Holdings Investment Narrative Recap
To own Norwegian Cruise Line Holdings, you need to believe the cruise operator can keep filling ships at strong pricing while steadily improving its cost base and guest experience. The latest signal that third quarter results should come in ahead of guidance supports that operating thesis in the near term, because it points to firmer revenue trends and demand holding up into 2027 and 2028.
The key short term swing factor is still how quickly earnings can grow relative to interest expense, given leverage and euro debt exposure. Higher booked occupancy helps, but the main risk remains that debt costs and rising inputs limit margin progress, leaving less room for reinvestment or balance sheet repair.
The most relevant update here is Norwegian Cruise Line Holdings’ proposed US$750 million senior notes due 2031. Management plans to use the proceeds, together with cash on hand, to redeem 6.125% notes maturing in 2028 and reduce borrowings on revolving and export credit facilities, while also covering transaction costs.
This refinancing sits squarely on the main catalyst and the main concern. Execution on this plan, combined with better than guided third quarter revenue, feeds directly into the 2027 net interest expense outlook of US$860 million to US$880 million. The more that interest bill stabilises, the easier it becomes for any operational progress to show up in earnings.
Norwegian Cruise Line Holdings’ long range setup assumes revenue of US$11.6b and earnings of US$895.5m by 2029, built on analysts’ 4.5% yearly top line growth and a shift from US$760.8m of earnings today to the 2029 consensus. This implies an earnings increase of about US$135m over the period.
Uncover why Norwegian Cruise Line Holdings' fair value indicates a 41% potential upside to its current price, which could narrow quickly.
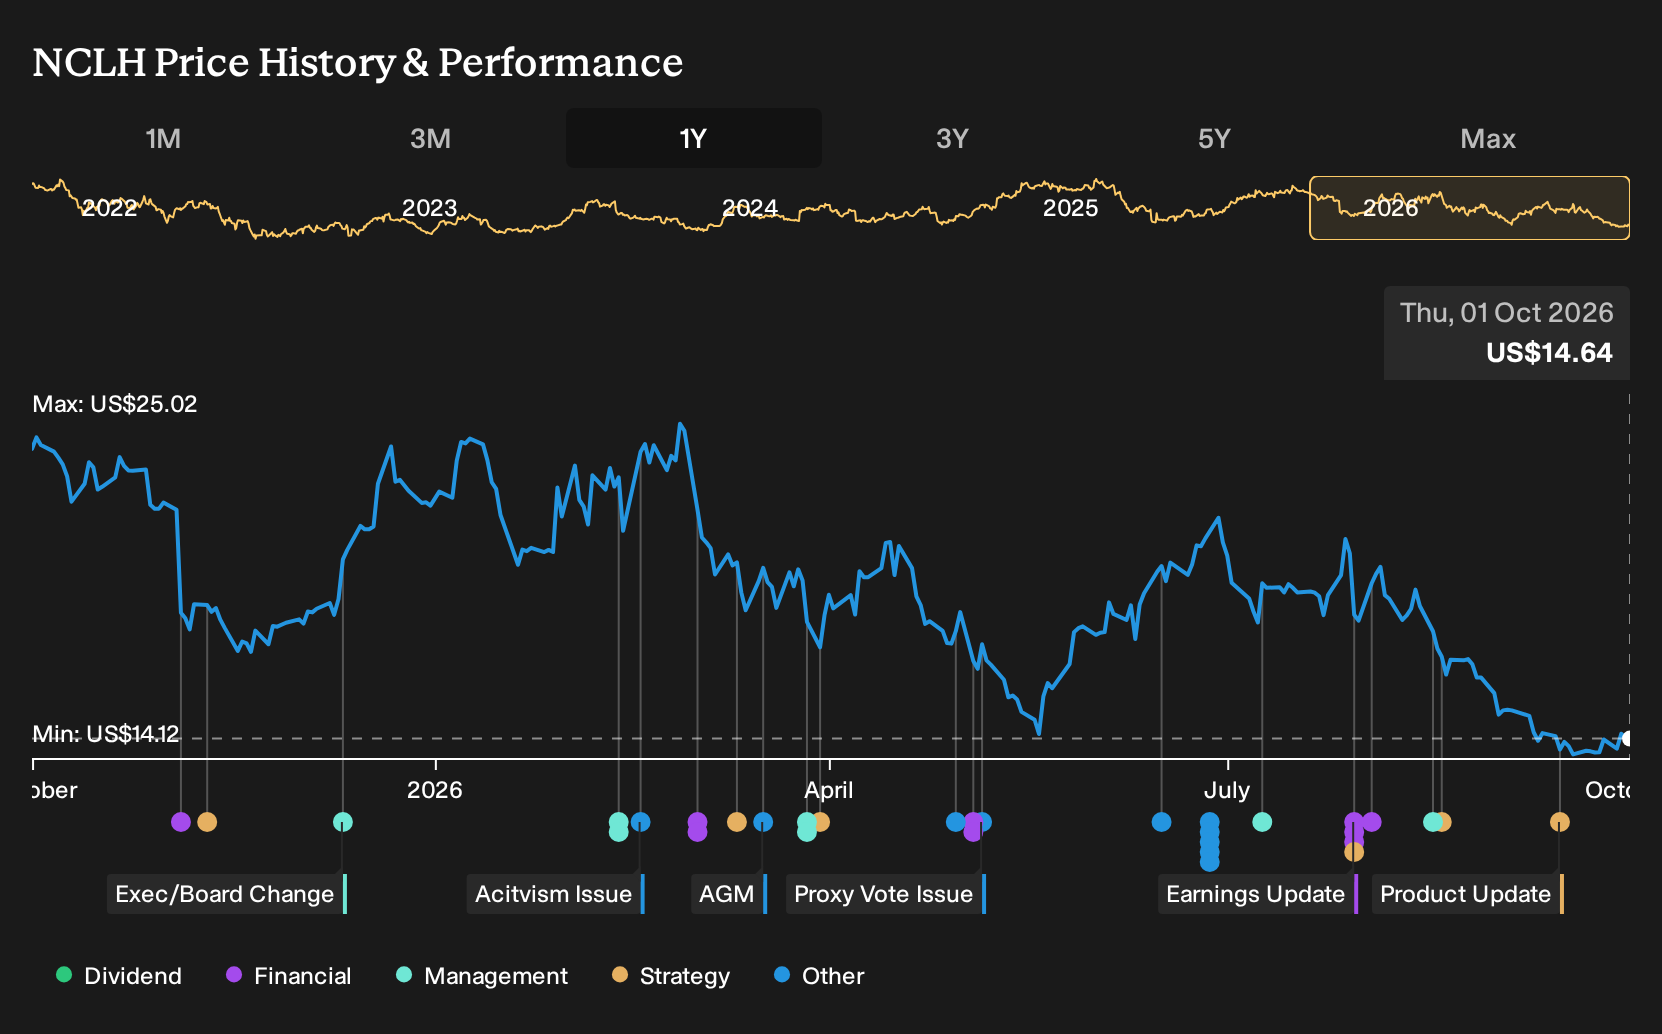
Exploring Other Perspectives
Fuel costs sit at the center of the alternate bearish view. While Norwegian Cruise Line Holdings talks about demand and refinancing, the weakest analysts focus on cost pressure and thinner margins. They were modeling revenue of about US$11.2b and earnings of roughly US$621.1m by 2029. Those forecasts came before this update, so you may see opinions shift as new information is released. It can be useful to compare several viewpoints before deciding how this fits your own thesis.
Explore 4 other Norwegian Cruise Line Holdings fair value estimates, including one that suggests as much as 72% downside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Norwegian Cruise Line Holdings research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Norwegian Cruise Line Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Norwegian Cruise Line Holdings' overall financial health at a glance.
Looking For More Investment Ideas Beyond Norwegian Cruise Line Holdings?
If the Norwegian Cruise Line Holdings story has sharpened your view on risk, reward, and balance sheet repair, it can be useful to widen the lens and compare it with companies in very different positions. The Simply Wall St Screener gives you a set of starting points so you can filter for the kind of profiles that best match your own approach, whether you care most about quality, income, or resilience.
- For investors who care most about quality at a reasonable entry point, consider scanning a focused group of 27 high quality undervalued stocks that combine fundamental strength with potentially attractive pricing.
- If income steadiness is a priority, you can zero in on 7 dividend fortresses that target higher yields while still paying attention to balance sheet support for those payouts.
- For readers who prefer durability over excitement, it can be helpful to review 31 resilient stocks with low risk scores that screen well on resilience and lower overall risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com