


Did Raised 2026 Guidance Just Shift Hapag Lloyd's (XTRA:HLAG) Investment Narrative?
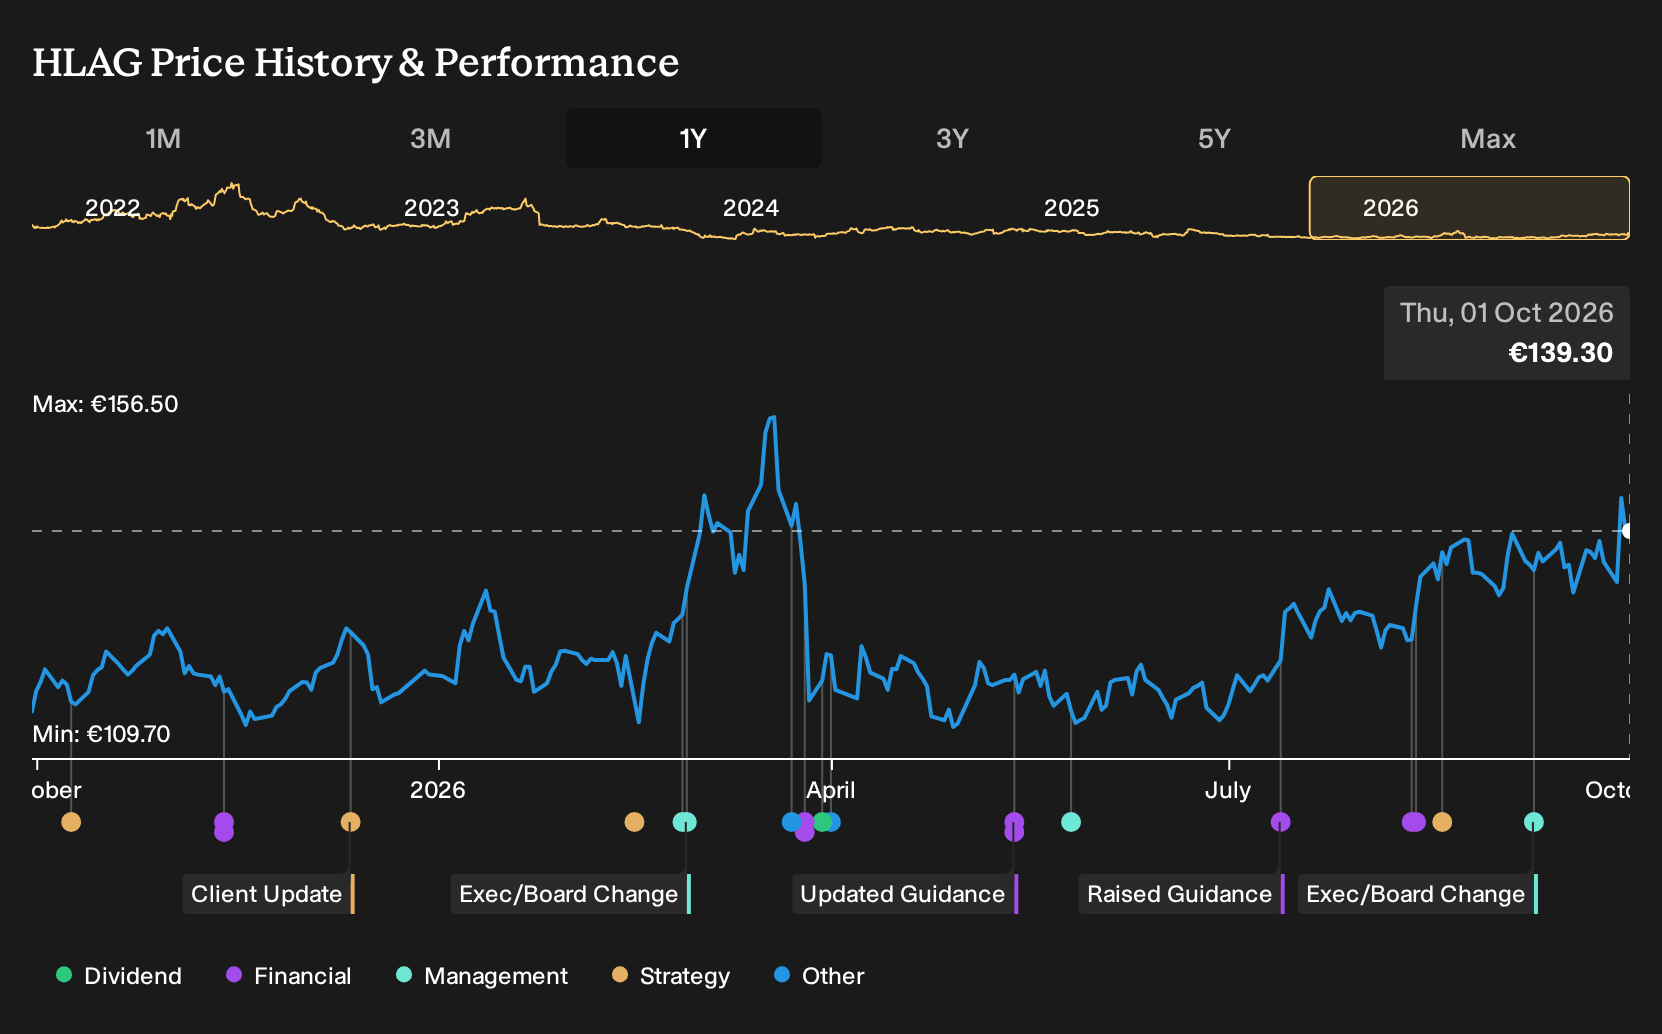
- Hapag-Lloyd recently raised its 2026 earnings guidance, citing sustained container shipping demand and supportive spot freight-rate trends, while still highlighting significant uncertainty from volatile pricing and geopolitical risks.
- The guidance change points to freight markets that are currently stronger than management had previously built into its planning, and it gives investors a clearer view of how sensitive Hapag-Lloyd’s profit outlook is to spot-rate conditions.
- We will now look at how Hapag-Lloyd's upgraded 2026 earnings guidance could influence the broader investment narrative for the group.
Scan how Hapag-Lloyd's upgraded outlook fits within a tighter universe of container shipping peers and capital-intensive operators by reviewing the list of solid balance sheet and fundamentals (207 results).
Hapag-Lloyd Investment Narrative Recap
To be comfortable owning Hapag-Lloyd, you need to accept a freight market that can swing quickly, while believing management can keep extracting value from its fleet, terminals and network upgrades. The higher 2026 earnings guidance leans on firm container demand and spot rates, which, if sustained, support that thesis but do not remove the cyclicality.
In the near term, the key swing factor is still freight pricing on core trade lanes. The upgraded outlook ties the short term catalyst directly to spot rate resilience. The biggest risk remains a sharp reset in those rates from current levels, especially with profit margins already thin at 0.3% and geopolitical disruption still elevated.
The latest guidance revision itself is the most relevant recent announcement. Management pointed to ongoing strong container demand and positive spot freight-rate trends when lifting the 2026 outlook, while at the same time calling out high uncertainty around pricing and geopolitics. That mix of confidence and caution puts a clear operational frame around the story.
For you as an investor, the takeaway is practical. Freight markets are currently supporting Hapag-Lloyd’s earnings ambitions, which could give more breathing room to progress on cost measures, digital tools and terminal integration. Yet the same outlook explicitly reminds you that earnings are still highly exposed to rate volatility, trade policy shifts and potential route disruptions.
Hapag-Lloyd's current analyst narrative points to €20.1b in revenue and €155.8m in earnings by 2029, based on 3.3% yearly revenue growth and an earnings increase of about €97.8m from €58.0m today.
Uncover how Hapag-Lloyd's fair value indicates a 24% potential downside to its current price, suggesting that the current premium may not be sustainable.
Exploring Other Perspectives
One alternate view puts freight rate risk front and center. The most optimistic Hapag-Lloyd analysts were assuming faster revenue growth of 9.5% a year and earnings of €95.8 million by 2029 before this guidance upgrade. That more upbeat story could strengthen further or be challenged as this new outlook gets absorbed.
Explore 3 other Hapag-Lloyd fair value estimates, including one that suggests it could be worth as much as €135.00.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hapag-Lloyd research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Hapag-Lloyd. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hapag-Lloyd's overall financial health at a glance.
Looking For More Hapag-Lloyd Investment Alternatives?
If Hapag-Lloyd's updated guidance has sharpened your view on shipping risk and reward, it can help to line that up against other listed businesses with different balance sheet strength, income profiles and risk levels using the Simply Wall St Screener.
- For investors who want potential mispricing with quality fundamentals, scan a curated set of 189 high quality undervalued stocks that pair financial strength with attractive valuation markers.
- If capital preservation and steadier profiles matter more to you than rapid gains, focus on a targeted group of 223 resilient stocks with low risk scores that screen well on balance sheet resilience and risk scores.
- For those hunting beyond the usual watchlists, sift through 617 high quality undiscovered gems that combine solid underlying metrics with relatively limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com