


3 Japanese Undervalued Stocks With Earnings Growth Over 16%
Global bond yields have surged to multi decade highs, including in Japan, as investors demand higher compensation for lending to governments. That pressure has knocked confidence in many Tokyo listed stocks and left some high quality businesses trading on cautious expectations. This creates a window for you to look at financially solid Japanese companies that screens flag as potentially undervalued. This article highlights three such stocks from our high quality breakout shortlist.
The three examples below are a small sample of the opportunities that screen as both high quality and potentially mispriced, and the full filter currently flags 14 more companies with similarly interesting stories that are not covered here. To go straight to the source, use the High Quality Undervalued Stocks screener to identify, filter and analyze the highest conviction ideas for your watchlist.
BuySell TechnologiesLtd (TSE:7685)
Overview: BuySell TechnologiesLtd runs a reuse and resale platform in Japan, trading kimonos and branded luxury goods through online, store, event, and auction channels.
Operations: The business generates all of its ¥124,962 million revenue from the reuse segment for kimonos and branded products within Japan.
Market Cap: ¥176.3 billion
BuySell TechnologiesLtd fits this high quality undervalued screen because its kimono and branded goods reuse business produces recurring, asset backed cash flows that support value scores pointing to potential mispricing. Management is focusing on that model through guidance upgrades and expansion plans, with future profitability tied closely to how one unseen pressure on funding costs and leverage ultimately resolves.
With that funding question hanging in the air, review the 4 key rewards and 1 important warning sign for BuySell TechnologiesLtd to see how the balance of upside and pressure really stacks up.
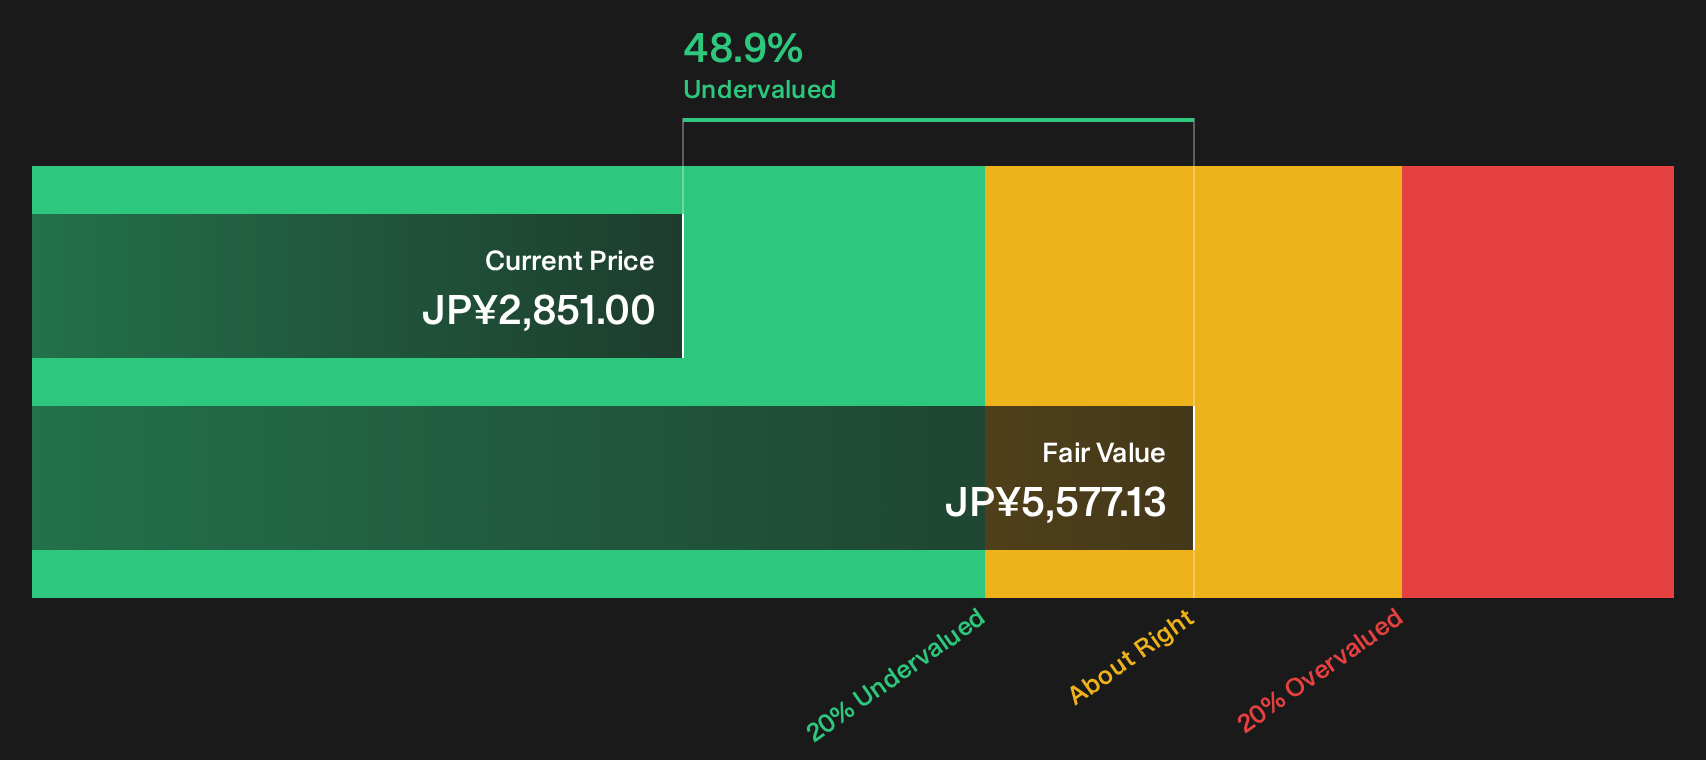
GMO Payment Gateway (TSE:3769)
Overview: GMO Payment Gateway runs cashless payment and financial services platforms that process online and in store transactions for merchants in Japan and overseas.
Operations: The business generates approximately ¥67.9 billion from Payment Processing, ¥21.7 billion from Money Services, and ¥1.8 billion from Payment Enhancement, with a small unallocated adjustment.
Market Cap: ¥653.2 billion
GMO Payment Gateway appears on this high quality undervalued screen because its PG multi payment service and processing platform handle recurring digital transactions across cards, QR apps and bank transfers, supporting sizeable cash flows and a solid balance sheet. Recent revenue of ¥69,728 million and net income of ¥18,981 million illustrate that position. Future margin resilience will depend on how competitive and pricing pressures develop.
Those competitive and pricing pressures are exactly why it helps to review the 5 key rewards and 1 important warning sign and evaluate what the market might be missing on GMO Payment Gateway.

Rakuten Bank (TSE:5838)
Overview: Rakuten Bank is a Japanese internet bank that gathers deposits and lends to consumers and businesses while earning payment and transfer fees.
Operations: Rakuten Bank generates all of its ¥207,733 million revenue from banking activities in Japan, mainly through deposit taking, lending, and related services.
Market Cap: ¥1.1 trillion
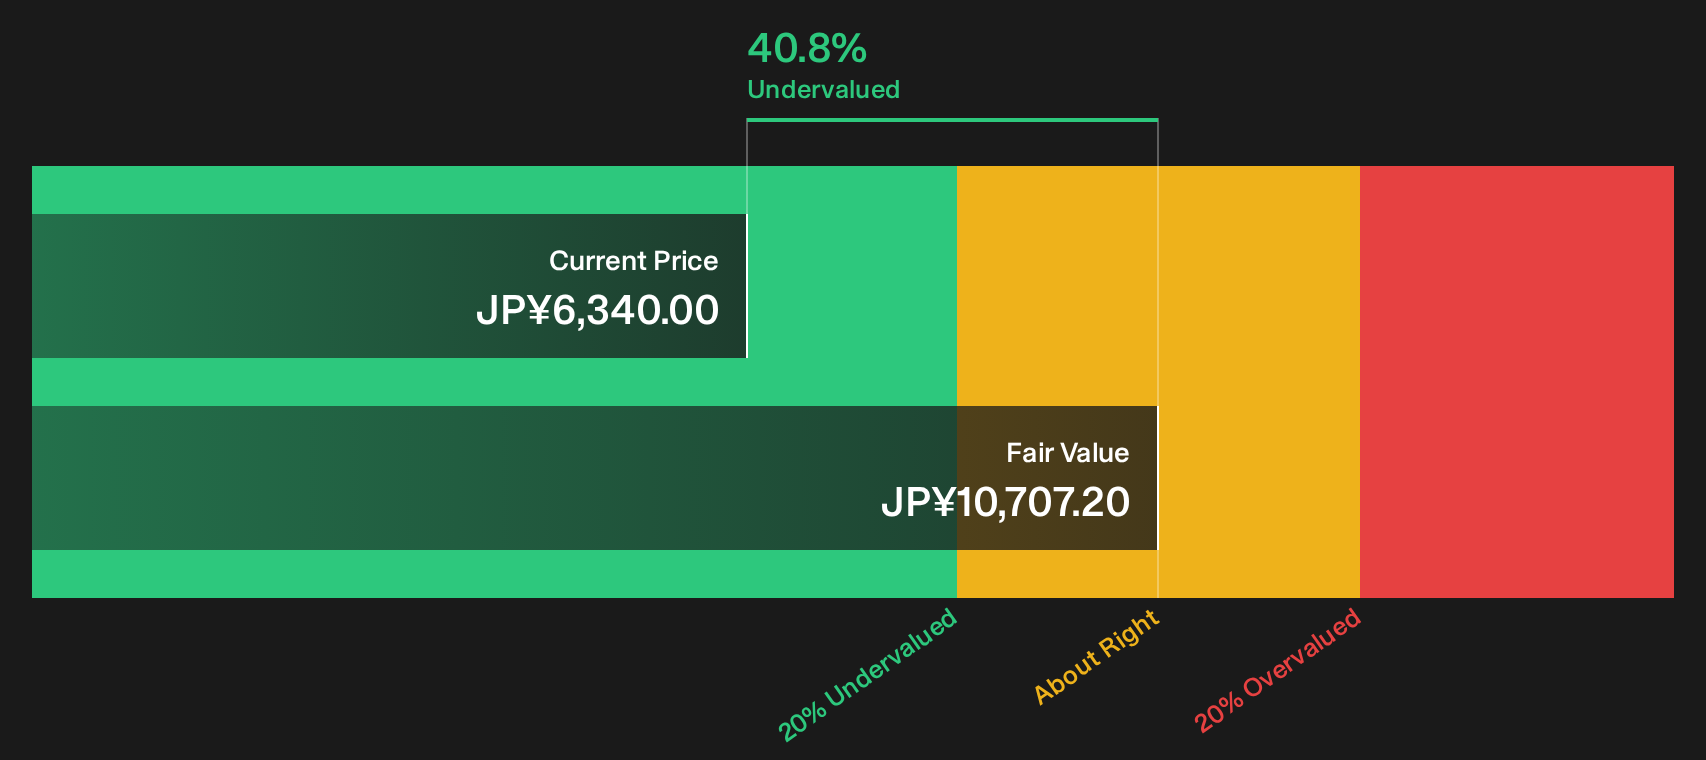
Rakuten Bank aligns with the High Quality Undervalued Stocks theme, with its online deposits, loans, and payment services feeding interest and fee income. Earnings grew 43.9% year on year, forecast growth is 16.7% a year, and the shares trade about 40.8% below one fair value estimate. Much depends on how one unseen pressure on digital banking profitability ultimately plays out.
That digital profitability question is exactly why the analysis report for Rakuten Bank can help you see where Rakuten Bank’s risk and valuation story may be quietly decoupling.
Seeking Fresh Alternatives Before They Fly
Fresh breakout potential often gets caught early, before momentum is obvious and while the data still matters. Do not let under the radar ideas slip away; act now.
- Target resilient cash generators by scanning the curated list of solid balance sheet and fundamentals (23 results) and spot companies that pair disciplined funding with fundamentals strong enough to handle tougher conditions.
- Ride structural demand shifts by reviewing the 39 power grid technology and infrastructure stocks and focus on businesses positioned around grid upgrades, transmission tech, and critical infrastructure momentum.
- Track the next wave of automation by using the 90 robotics and automation stocks and zero in on operators tying software, sensors, and hardware into scalable real world solutions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com