


What ABN AMRO Bank (ENXTAM:ABN)'s Infosys AI Tie Up Means For Shareholders
- Infosys and ABN AMRO Bank announced that they have extended their collaboration to modernize the bank's IT systems with AI, covering application development, testing, and support to improve efficiency and scalability across operations.
- The deeper use of Infosys Topaz to embed AI across ABN AMRO Bank's technology stack points to a push for more data driven services, which could influence long term cost discipline and digital execution.
- This raises the question of how ABN AMRO Bank's investment narrative could be affected by this wider AI integration with Infosys across its systems.
ABN AMRO Bank Investment Narrative Recap
To own ABN AMRO Bank, you need to believe it can keep compounding solid earnings from a focused Northwest Europe footprint while steadily tightening its cost base. The Infosys AI expansion fits that story only if it feeds into lower unit costs, quicker product rollouts, and better digital retention versus fintech and big tech competition.
The near term swing factor still looks like execution on digital and cost to income rather than this single contract. The biggest risk remains pressure from regulation and capital requirements that could cap loan growth and returns, especially with a low bad loan allowance and ongoing oversight around mortgages and past compliance issues.
The extended Infosys Topaz rollout across ABN AMRO Bank’s IT stack feels most relevant right now because it plugs directly into those digital and efficiency catalysts. Management has already been pushing app modernisation and BUUT, its Gen Z focused neobank. This agreement gives that push more engineering scale and tooling depth.
For you as a shareholder, the interest is operational. Better AI driven systems might support leaner headcount, more targeted risk monitoring and smoother customer journeys, which matter for costs and fee resilience. If client activity weakens or regulation tightens, the risk is that efficiency wins arrive more slowly than needed to offset margin pressure.
ABN AMRO Bank's narrative projects €10.8b revenue and €3.4b earnings by 2029, which assumes 6.0% yearly revenue growth and about a €1.1b earnings increase from €2.3b today.
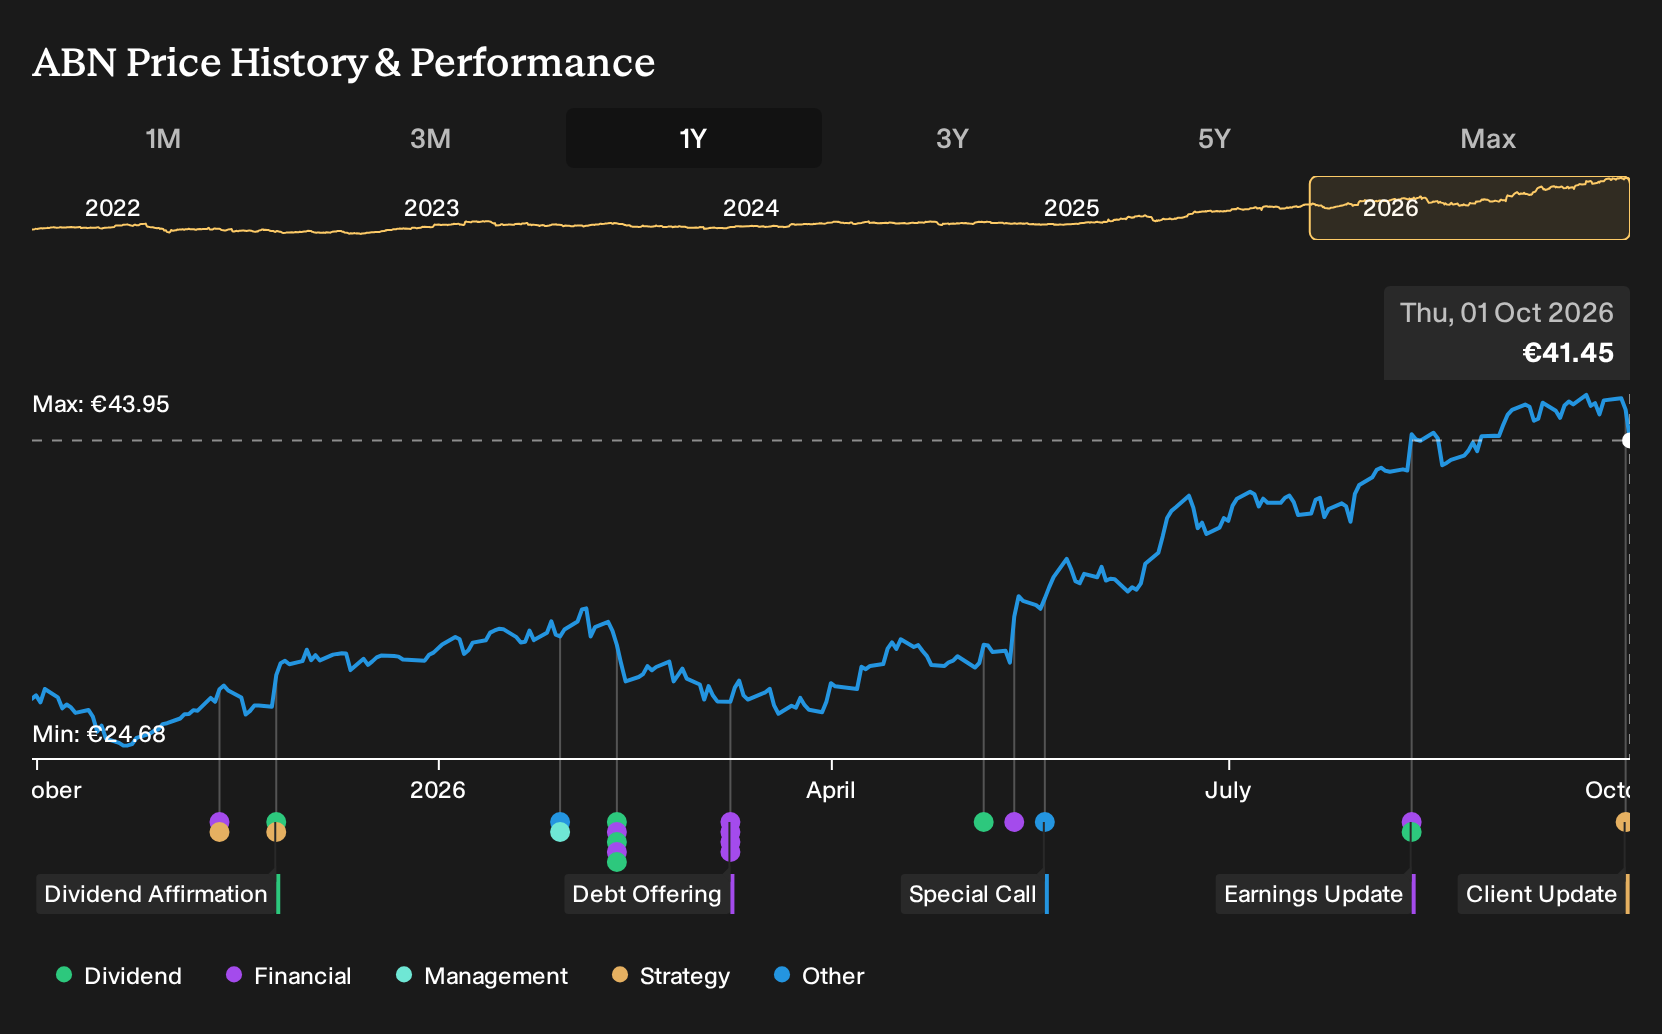
Discover why ABN AMRO Bank's fair value indicates a 4% potential upside to its current price that could close sooner than the market expects.
Exploring Other Perspectives
Some of the lowest ABN AMRO Bank analysts lean hard into the risk that digital competitors eat into fee and interest income, which clashes with today’s AI-heavy Infosys deal. Before this news, the bearish group worked off revenue of about €10.6b and earnings of €3.3b by 2029. That gap shows how widely views differ and why you might want to look at several alternative forecasts before deciding what this AI push could mean for you.
Explore 3 other ABN AMRO Bank fair value estimates, including one that suggests it could be worth just €43.18.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your ABN AMRO Bank research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ABN AMRO Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ABN AMRO Bank's overall financial health at a glance.
Looking For More Ideas Beyond ABN AMRO Bank?
If you want to stress test your thesis on ABN AMRO Bank, it can help to scan for other businesses with different balance sheet profiles, payout approaches, or valuation setups. The Simply Wall St Screener lets you line up options side by side so you can decide where capital might work hardest for your own goals.
- For income focused portfolios that still prize resilience, check out 157 dividend fortresses that combine meaningful yields with an emphasis on durability.
- If capital preservation and steadier earnings streams matter most to you, filter for 223 resilient stocks with low risk scores that aim to keep downside surprises in check.
- When you want quality fundamentals that are not already crowded trades, scan through 617 high quality undiscovered gems that may sit off the usual radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com