


ASX Growth Companies With High Insider Ownership For October 2026
The Australian market has recently experienced a strong rebound from its September weakness, driven by encouraging inflation numbers that have tempered expectations of further rate hikes by the RBA. Despite mixed signals from US equities and fluctuating oil prices, the focus on growth companies with high insider ownership remains pertinent as these firms often signal confidence in their potential for long-term success.
Top 10 Growth Companies With High Insider Ownership In Australia
| Name | Insider Ownership | Earnings Growth |
| Wisr (ASX:WZR) | 15.3% | 94.2% |
| Starpharma Holdings (ASX:SPL) | 19.3% | 75.1% |
| SKS Technologies Group (ASX:SKS) | 23.3% | 27.7% |
| PDI Gold (ASX:PDI) | 10.4% | 43.7% |
| Forrestania Resources (ASX:FRS) | 24.8% | 72.9% |
| Elsight (ASX:ELS) | 12.5% | 58.5% |
| Barton Gold Holdings (ASX:BGD) | 22% | 97.2% |
| Austral Resources Australia (ASX:AR1) | 24% | 28.2% |
| Adveritas (ASX:AV1) | 17.6% | 99.9% |
| Advanced Engineered Materials (ASX:AEM) | 35.1% | 58.7% |
Here we highlight a subset of our preferred stocks from the screener.
Australian Ethical Investment (ASX:AEF)
Simply Wall St Growth Rating: ★★★★☆☆
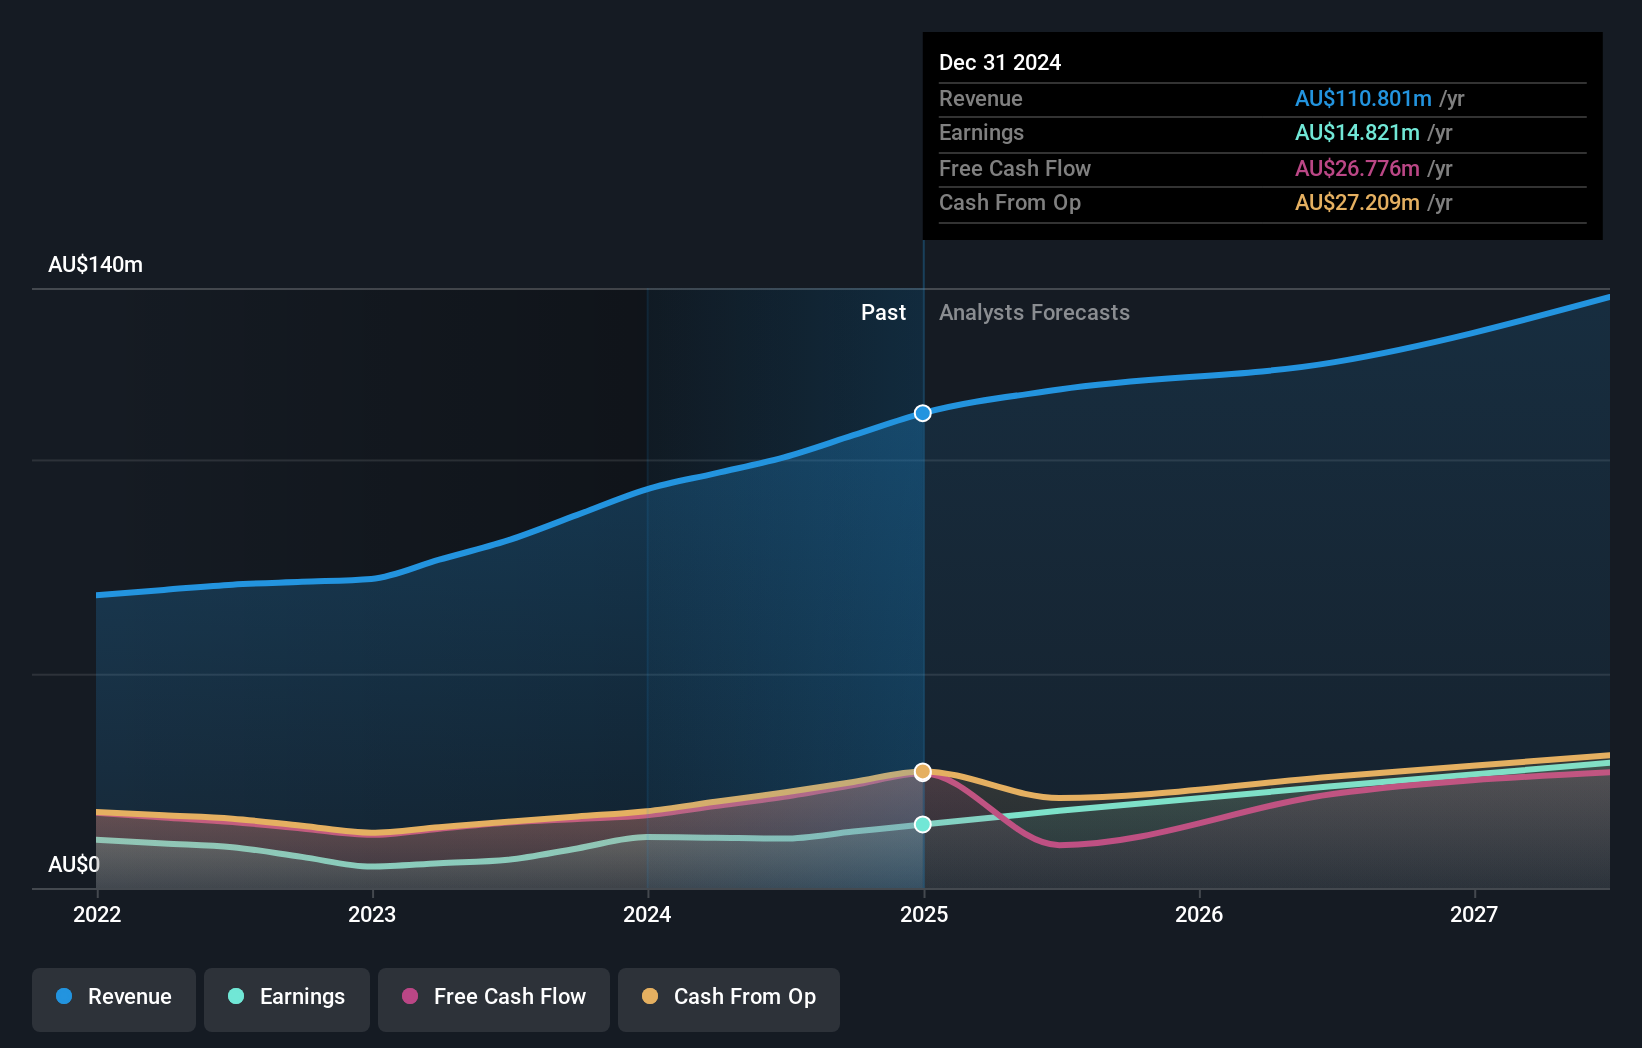
Overview: Australian Ethical Investment Ltd is a publicly owned investment manager with a market cap of A$464.43 million, focusing on ethical and sustainable investment strategies.
Operations: The company generates revenue primarily through its funds management segment, which accounts for A$129.55 million.
Insider Ownership: 19.5%
Earnings Growth Forecast: 14.0% p.a.
Australian Ethical Investment demonstrates solid growth potential, with earnings increasing by 27.8% over the past year and forecasted to grow at 14% annually, outpacing the Australian market. Despite a slower revenue growth forecast of 8.7%, it remains above the market average of 5.1%. The company's inclusion in the S&P/ASX Emerging Companies Index highlights its growing prominence. However, its dividend track record is unstable, and insider trading activity is currently minimal.
- Get an in-depth perspective on Australian Ethical Investment's performance by reading our analyst estimates report here.
- Upon reviewing our latest valuation report, Australian Ethical Investment's share price might be too optimistic.
Telix Pharmaceuticals (ASX:TLX)
Simply Wall St Growth Rating: ★★★★☆☆
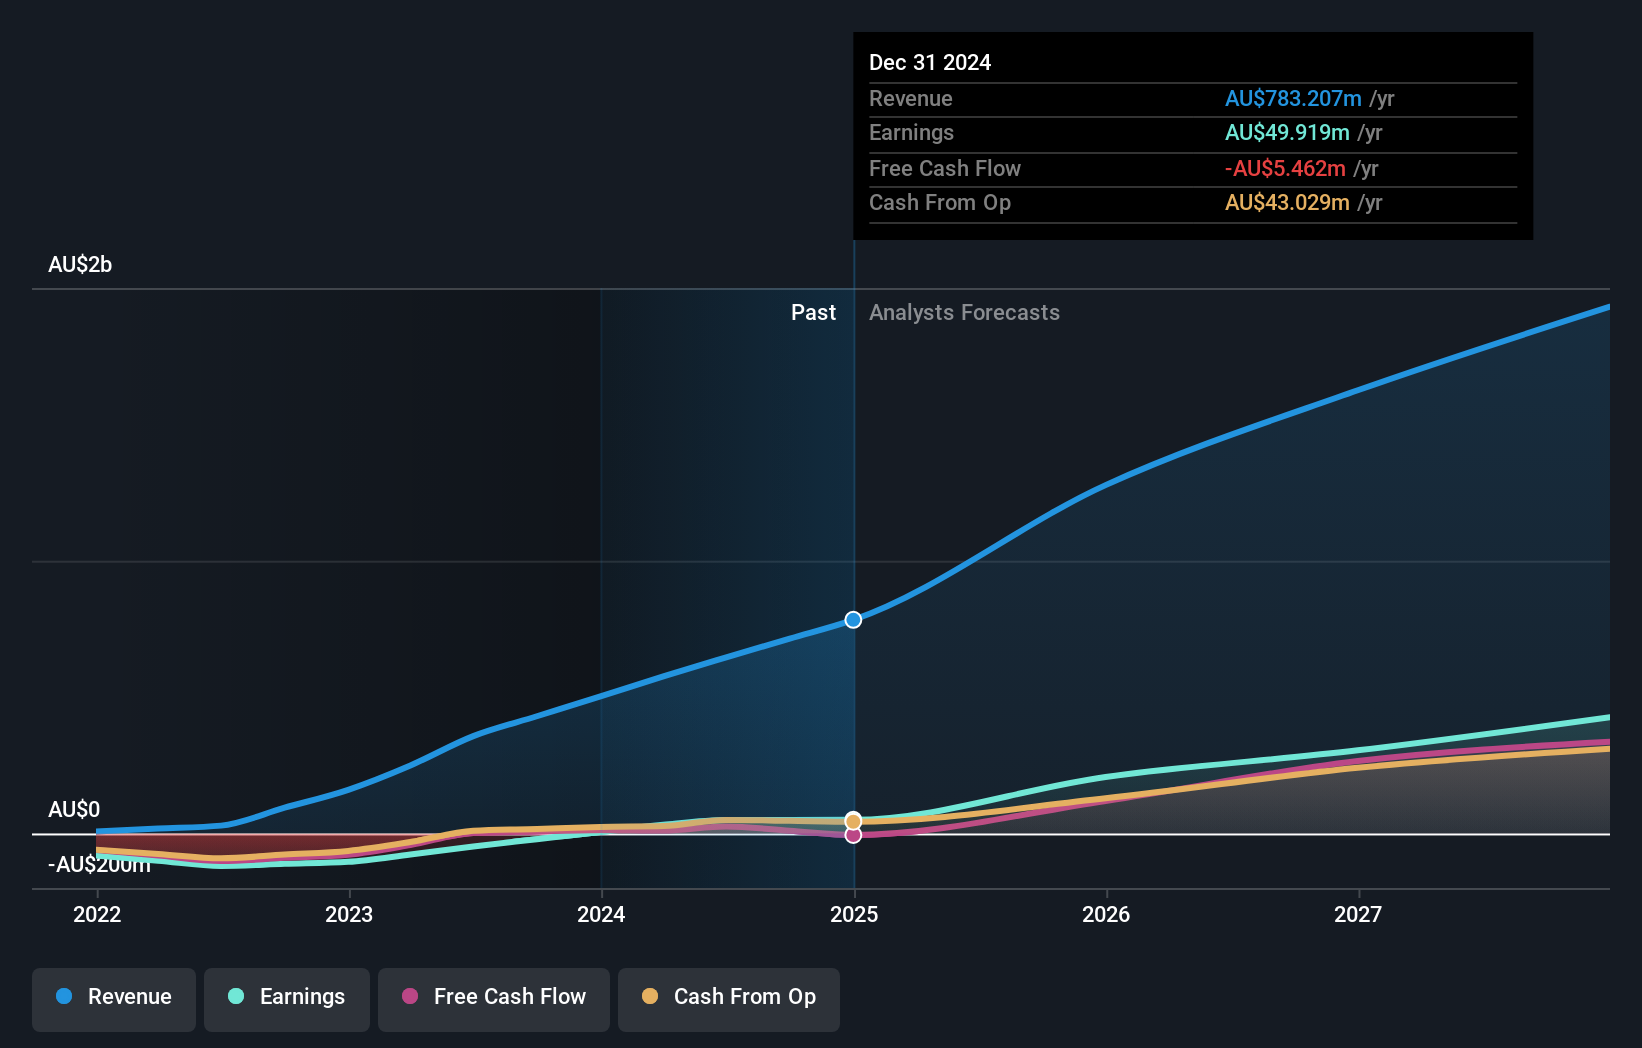
Overview: Telix Pharmaceuticals Limited is a commercial-stage biopharmaceutical company specializing in the development and commercialization of therapeutic and diagnostic radiopharmaceuticals, with a market cap of A$5.30 billion.
Operations: Telix Pharmaceuticals Limited generates revenue primarily from Precision Medicine ($704.73 million) and Manufacturing Solutions ($277.07 million).
Insider Ownership: 14.8%
Earnings Growth Forecast: 34.1% p.a.
Telix Pharmaceuticals is poised for significant growth, with earnings forecasted to rise 34.1% annually, surpassing the Australian market's average. Recent FDA approval of Pixclara enhances its competitive edge in radiopharmaceuticals. The company is exploring a strategic merger with ITM Isotope Technologies Munich SE, potentially expanding its global footprint. Despite low insider trading volumes recently, Telix insiders have been net buyers over the past three months, indicating confidence in future prospects.
- Navigate through the intricacies of Telix Pharmaceuticals with our comprehensive analyst estimates report here.
- Our valuation report here indicates Telix Pharmaceuticals may be overvalued.
WIA Gold (ASX:WIA)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: WIA Gold Limited, with a market cap of A$782.94 million, is involved in the exploration and evaluation of mineral properties in Namibia and Côte d’Ivoire through its subsidiaries.
Operations: The company focuses on exploring and evaluating mineral properties in Namibia and Côte d’Ivoire.
Insider Ownership: 18.8%
Earnings Growth Forecast: 30.3% p.a.
WIA Gold is forecast to achieve profitability within three years, with earnings growth expected at 30.31% annually, surpassing market averages. Despite reporting a net loss of A$14.15 million for the year ending June 2026, its high projected return on equity of 58% in three years underscores potential value creation. Recent inclusion in the S&P Global BMI Index and a follow-on equity offering of A$125 million suggest strategic positioning for future expansion despite current revenue challenges.
- Click here and access our complete growth analysis report to understand the dynamics of WIA Gold.
- According our valuation report, there's an indication that WIA Gold's share price might be on the expensive side.

Key Takeaways
- Investigate our full lineup of 116 Fast Growing ASX Companies With High Insider Ownership right here.
- Ready For A Different Approach? The end of cancer? These 35 emerging AI stocks are developing tech that will allow early idenification of life changing disesaes like cancer and Alzheimer's.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com