


British American Tobacco (LSE:BATS) Stock Could Be Below Fair Value On Earnings
British American Tobacco has delivered a 128.2% gain over the past 5 years, which naturally raises a question for anyone looking at the shares today. Is the current price still grounded in what the business earns, or has the performance moved ahead of its underlying earnings power?
- A 128.2% total return over 5 years puts real weight on whether British American Tobacco's earnings can support the share price that run has created.
- With a mature cash generating model and significant ongoing investment needs, the way profit converts into free cash flow can shape how much investors are prepared to pay for each pound of earnings.
- The analysts covering British American Tobacco have run their own numbers. See what analysts think British American Tobacco's shares could be worth.
The issue now is whether British American Tobacco's current market valuation is justified by the earnings the business is producing today.
If you are weighing British American Tobacco against other options built around earnings and valuation, it can help to compare it with companies in the same mindset using 8 high quality undervalued stocks.
Is British American Tobacco Still Cheap on Earnings?
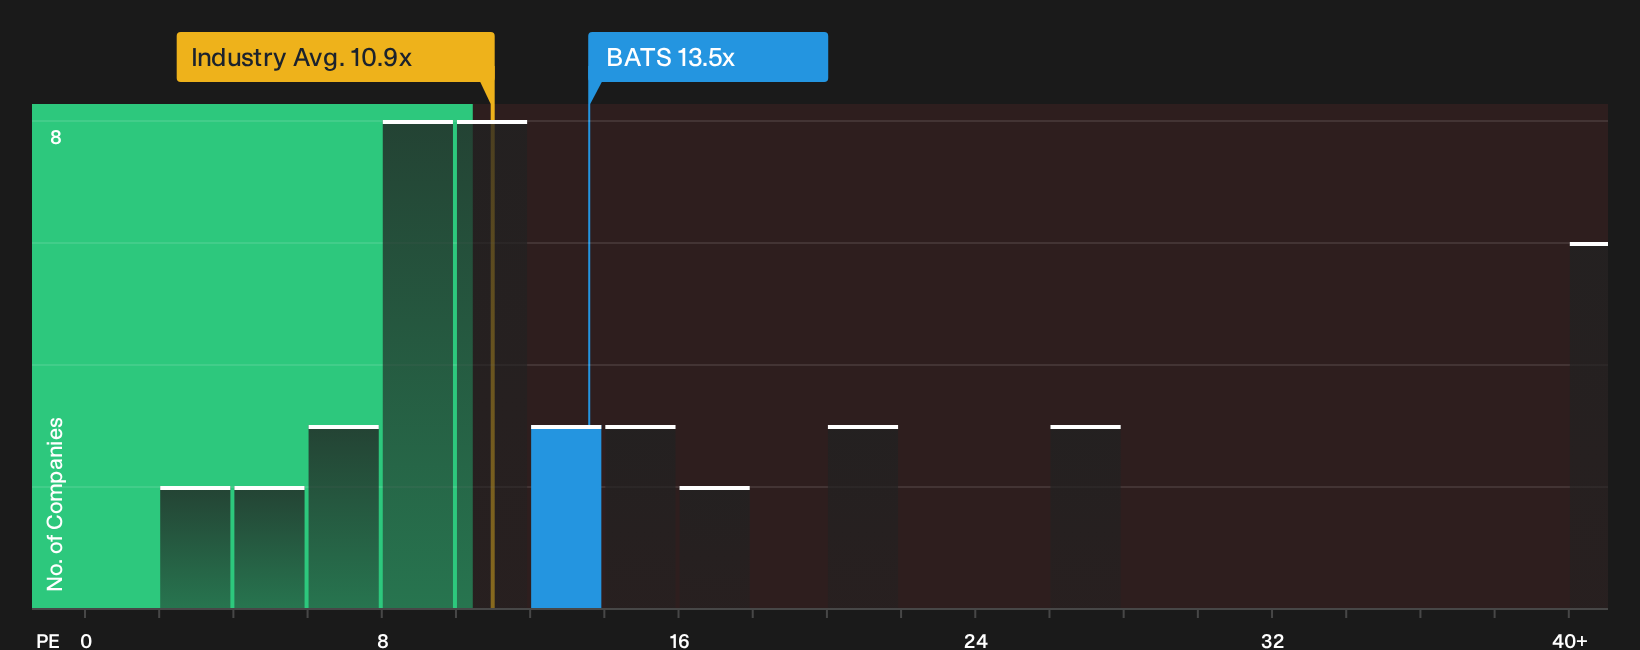
The P/E ratio suits British American Tobacco because earnings remain a central focus for investors deciding what they are willing to pay for each pound of profit. On this measure, the stock trades at about 13.5x earnings. That is lower than the Tobacco industry average of roughly 10.9x, which points to a richer multiple than many sector peers. Against a peer group average of about 17.5x, the valuation sits closer to the lower end of that range.
A tailored fair P/E, which reflects British American Tobacco's mix of margins, expected cash generation, size and risk profile, sits above where the shares currently change hands. That gap suggests the stock screens as undervalued on this earnings yardstick, even after accounting for sector specific risks and capital needs. For anyone comparing it with other income focused or cash generative companies, the P/E level flags a discount that may warrant a closer look at how durable those earnings really are. Explore the numbers behind British American Tobacco's P/E valuation.
The British American Tobacco Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the British American Tobacco valuation puzzle leaves off by spelling out which future paths for earnings, margins and cash generation would need to play out for the stock to be worth materially more or less than it is today, and they sit on the company’s Community page. Each one treats fair value as a working hypothesis about British American Tobacco's business that you can revisit over time rather than a one off snapshot.
One of the top community narratives on British American Tobacco: 23% undervalued
"Digital transformation, operational streamlining, and targeted cost savings programs are releasing capital for reinvestment in high return opportunities and innovation…"
Discover why this Narrative puts British American Tobacco at 23% undervalued.
One more British American Tobacco angle worth checking before you move on
Price tags and profit multiples only tell part of the story, because the people setting priorities and the way their rewards are structured can heavily influence how that story unfolds over time. See who runs British American Tobacco and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com