


How Investors May Respond To MasTec (MTZ) AI Infrastructure Growth
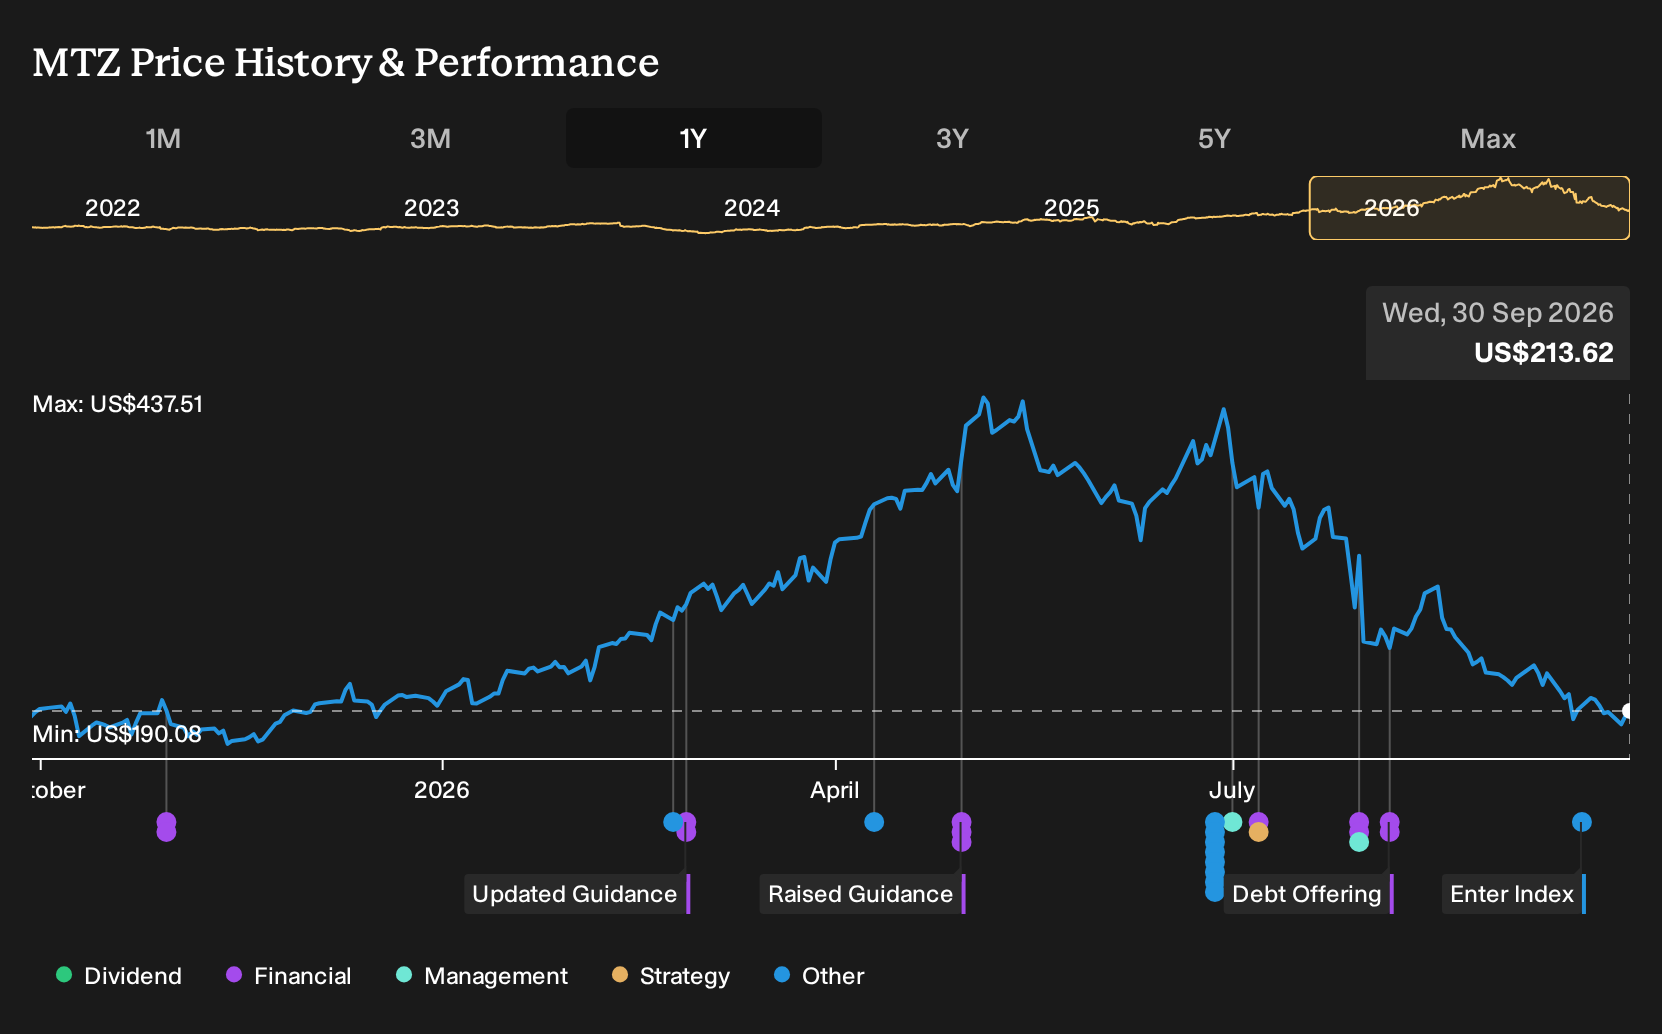
- MasTec was added to the FTSE All-World Index (USD) in September 2026, recognizing the infrastructure contractor’s growing role in global equity benchmarks.
- The inclusion comes as MasTec leans further into AI data center buildouts, utility grid work, and clean energy projects, deepening its exposure to long-cycle infrastructure spending.
- This article examines how MasTec’s investment narrative is influenced by index inclusion together with rising AI data center infrastructure demand.
Scan beyond MasTec and see how other hand-picked AI infrastructure contractors are positioned across grids, data centers, and clean energy through our 90 AI infrastructure stocks
MasTec Investment Narrative Recap
To own MasTec, you need to believe in a long stretch of work in power delivery, clean energy, and AI driven data infrastructure, with the record backlog turning into cash flow without major hiccups. The FTSE All World inclusion may incrementally support liquidity and index driven demand, but it does not change how effectively projects are executed on the ground.
The key near term swing factor remains how quickly higher AI data center and grid related work flows through to margins after the recent investment in people and equipment. The biggest risk is that large customers delay or resize projects, which would leave MasTec carrying higher fixed costs and thinner profitability for longer.
The most relevant piece of context for the index news is MasTec leaning into AI data center infrastructure. Management is already building routes for fiber, power lines, and clean energy assets that support hyperscale facilities. That operational tilt gives the FTSE inclusion more substance than a simple technical index move for you as a shareholder.
Those same AI and grid projects tie directly into the main catalysts investors focus on. These catalysts include record backlog in Power Delivery and Clean Energy and an expectation of higher margins as utilization improves. The risk side is clear. These are large, complex contracts, so any execution slip or permitting delay can quickly eat into the earnings ramp that many investors are watching.
MasTec Forecasts Behind the FTSE Inclusion
Analysts currently frame MasTec around a multi year build in earnings power. Consensus assumes revenue expands at about 18.3% a year over the next three years, with profit rising from $494.3 million today to $1.2b by 2029. That uplift in profitability underpins expectations that margins move from 3.1% to 4.6% over the same period as the heavier AI data center and grid work matures.
MasTec's narrative points to forecast 2029 revenues of $26.7b and earnings of $1.2b. This rests on 18.3% yearly revenue growth and an earnings increase of roughly $706 million from $494.3 million today.
Discover why MasTec's fair value indicates a 95% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
You might focus on AI data center upside, yet the most cautious analysts fixate on project risk instead. They were modeling 17.0% annual revenue growth and about US$25.8b of sales by 2029, along with US$1.1b of earnings. Those pre inclusion forecasts could shift, so consider how views on MasTec might broaden from here.
Explore 6 other MasTec fair value estimates, including one that suggests there may be as much as 16% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your MasTec research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for MasTec. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MasTec's overall financial health at a glance.
Looking for more MasTec-sized investment ideas?
If MasTec has you thinking about how infrastructure, cash flow, and long-term projects fit into your portfolio, it can be useful to line it up against other opportunities on the Simply Wall St Screener before making any decisions.
- If you want potential mispricings where quality and valuation intersect, scan through a curated set of 31 high quality undervalued stocks that might sit alongside or compete with MasTec in your watchlist.
- If capital preservation matters just as much as upside, focus on companies with sturdier finances through a list of solid balance sheet and fundamentals (25 results) that can help you stress test your ideas.
- If you prefer to hunt where fewer investors are looking, widen your radar with a group of 19 high quality undiscovered gems that pair fundamental strength with lower visibility.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com