


Citi Just Upgraded Rocket Lab Stock. Here's Why.
Citi’s senior analyst John Godyn believes Rocket Lab (RKLB) shares have now bottomed and are poised for meaningful recovery through the remainder of 2026. On Thursday morning, Godyn upgraded RKLB to “Buy” and assigned a $105 price target to the launch service provider, indicating potential upside of more than 40% from here.
His bullish call brings a much-needed reprieve to Rocket Lab stock, which is currently trading at less than half of its price in late May.
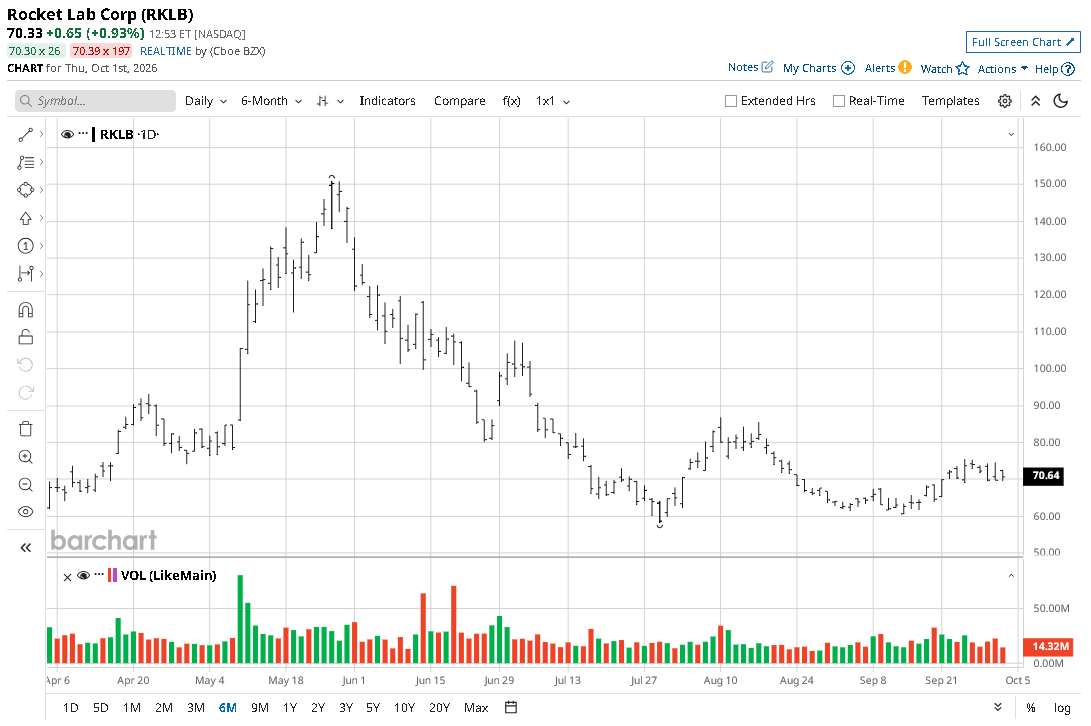
Why Citi Upgraded Rocket Lab Stock Today
In his research note, John Godyn dubbed RKLB stock a “core holding for space bulls,” citing the firm’s vertical integration, which positions it to benefit from different segments of the fast-growing space economy.
His research report follows Rocket Lab’s multi-year agreement with Synspective — a Tokyo-based Earth observation company — for 20 launches, representing its largest-ever commercial contract for Electron.
According to the Citi analyst, RKLB is “one of the only companies on the planet delivering regular commercial access to orbit,” a distinction that alone positions it for significant upside from current levels.
That said, Barchart holds a “40% SELL” opinion on Rocket Lab, indicating technical momentum has not yet turned in its favor.
Massive Backlog Warrants Buying RKLB Shares
Rocket Lab’s agreement with Synspective provides significant revenue visibility for the core Electron segment while the company continues developing its larger, reusable Neutron rocket.
RKLB’s overall launch backlog now sits comfortably above 100 missions, a commercial traction that Citi sees as concrete validation that enterprise clients trust the Nasdaq-listed firm for mission-critical deployments.
In August, Rocket Lab reported better-than-expected revenue for its fiscal Q2, and issued full-year guidance for at least $250 million in revenue — also ahead of Street estimates.
However, RKLB shares, despite the recent decline, are still trading at nearly 70x sales, a multiple that makes them expensive at current levels.
Wall Street’s View on Rocket Lab
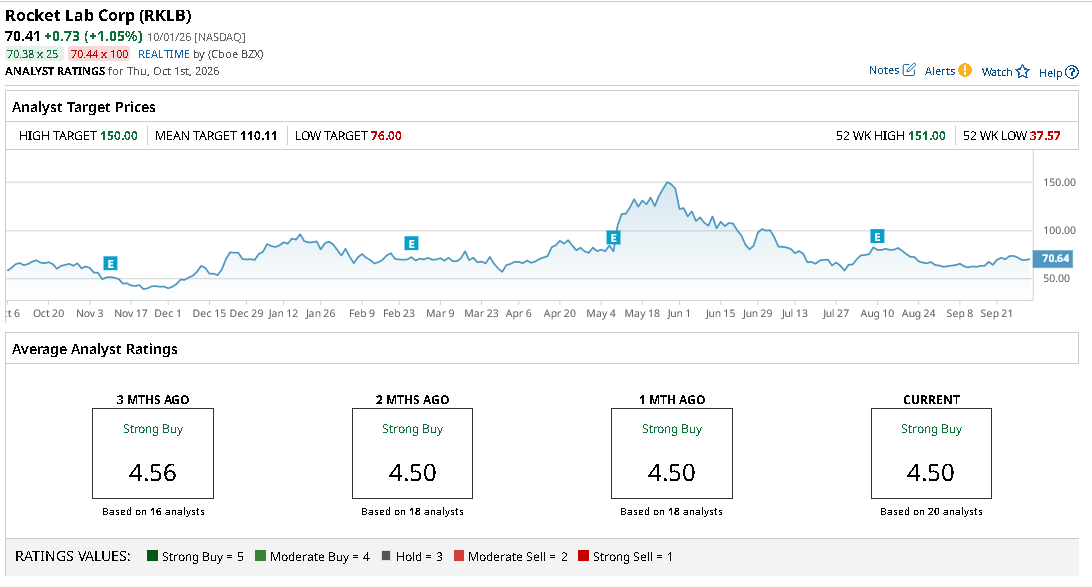
Wall Street analysts nonetheless recommend looking at valuation concerns and owning Rocket Lab shares in late 2026.
The consensus rating on RKLB sits at “Strong Buy,” with the mean price objective of roughly $110 signaling potential for a more than 50% rally from here.
On the date of publication, Wajeeh Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.