


3 Regional Bank Stocks Built For Higher Interest Rates
The dollar’s surge and a stubbornly hawkish Fed are reshuffling the deck for big U.S. banks and brokers, tightening funding costs while keeping trading desks and deposit margins firmly in focus. That mix can punish the wrong balance sheets and reward the right ones. This article walks through three large-cap financial stocks that screen well against this backdrop, and explains how recent Fed expectations may help or hurt each story.
The three stocks below are just a sample from this idea, and the full quantitative screen surfaced 14 more large U.S. banks and brokers with equally interesting stories that are not covered here. To see the wider field and identify which balance sheets, income streams, and capital returns best fit your own thesis, head straight to the U.S. Large-Cap Financials (Banks and Brokers) screener.
First Bancorp (FBNC)
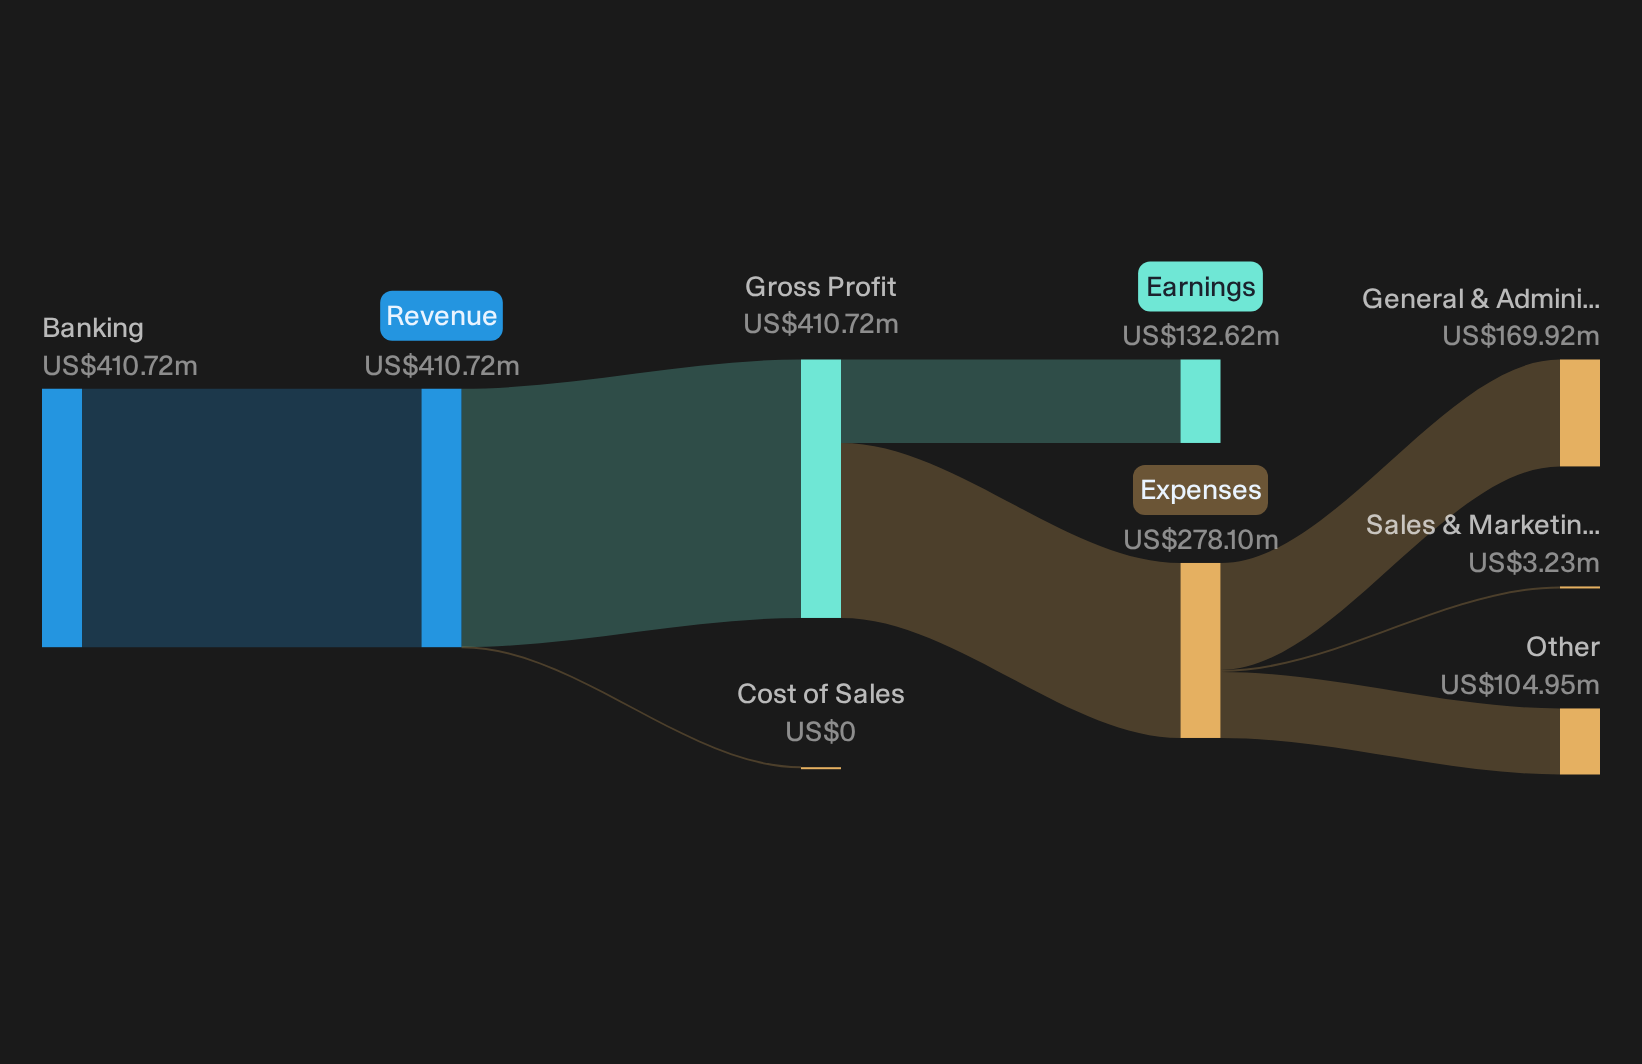
First Bancorp is a U.S. regional bank holding company in the large cap financials bracket, earning about US$410.7 million from banking activities like deposits, loans, cards, and fee services, all generated in the United States, with a market value of roughly US$2.6b.
First Bancorp fits this banks and brokers theme because its earnings are tied directly to net interest income, which can widen when Fed policy keeps short term rates elevated. Strong recent profitability and an ongoing dividend give the stock clear rate exposure. However, what happens if funding costs stop lagging remains the key pressure point.
If that pressure point is what you care about, go straight to the First Bancorp financial health report for a clearer read on how First Bancorp handles rising funding strain.
Nicolet Bankshares (NIC)
Nicolet Bankshares runs a regional banking platform across Wisconsin, Michigan, and Minnesota, offering loans, deposits, wealth management, and digital banking services. It generates about US$510 million from consumer and commercial banking, all in the United States, and has a market value near US$3.4b.
Nicolet Bankshares gives you direct exposure to a large cap regional bank whose earnings hinge on net interest margins and loan demand, which is what the U.S. Large-Cap Financials screener targets. Recent strength in net interest income and profitability makes that rate sensitivity a potentially attractive feature, depending on how one unseen pressure on those spreads develops.
That hidden pressure on spreads is exactly what shows up in the Nicolet Bankshares financial health report, where funding costs and balance sheet resilience come into sharper focus.

Columbia Financial (CLBK)
Columbia Financial is a New Jersey based bank group in the U.S. Large-Cap Financials theme, running a full service lending and deposit franchise that earns about US$267 million from financial services in the United States, and carries a market value near US$3.0b.
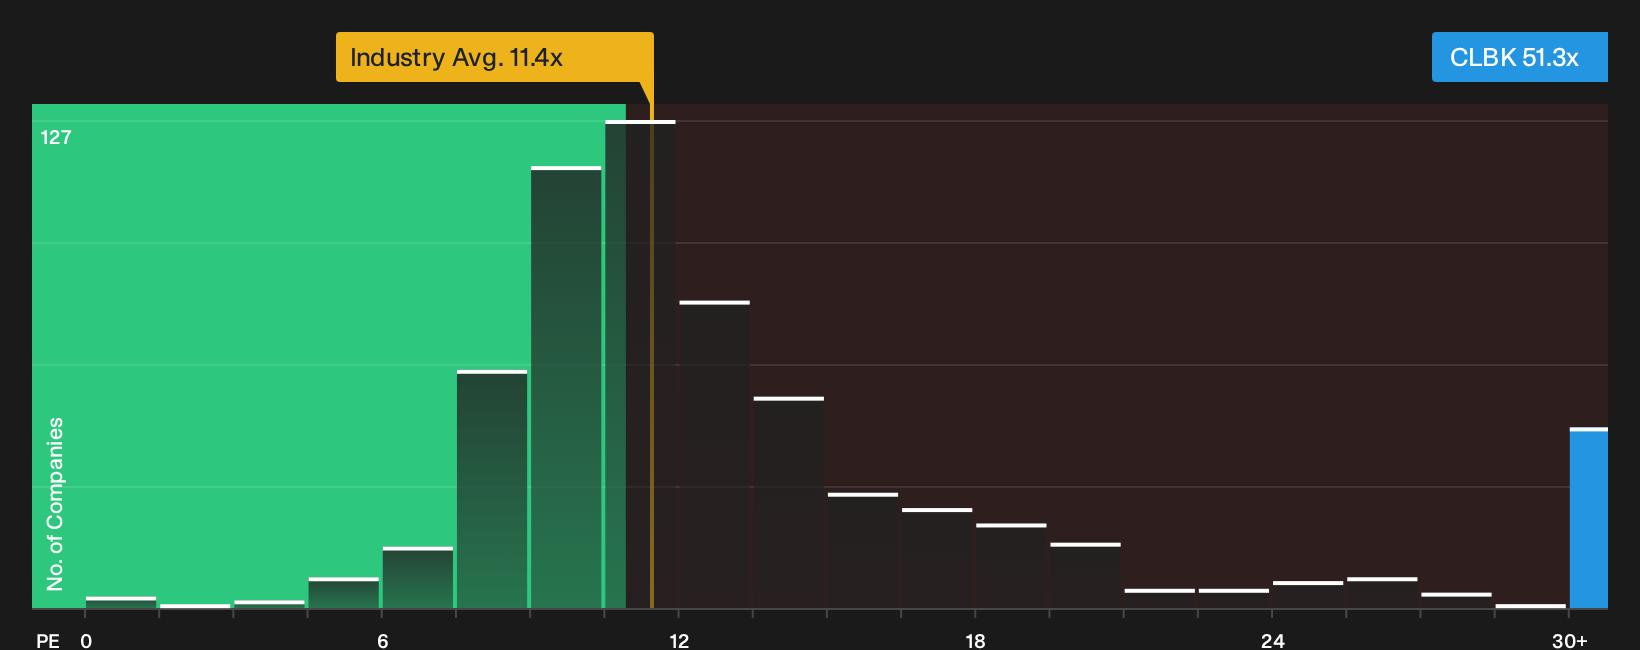
Columbia Financial is heavily wired into the higher for longer rate story, with interest bearing loans and deposits driving its US$267 million financial services income and supporting recent net interest income and dividend moves. Investor enthusiasm around its outlook meets a premium P/E and one unresolved question about how far margins can stretch if conditions shift again.
That margin question is exactly what the analysis report for Columbia Financial digs into, showing where Columbia Financial’s premium P/E could be masking either resilience or brewing strain.
Seeking Alternatives Before The Crowd?
Fresh ideas move first when momentum builds. Breakout stories often get picked off quickly once attention flies their way. Scan these curated lists while it matters and get in early.
- Track cash rich companies quietly building strength before the crowd notices by scanning a list of solid balance sheet and fundamentals (25 results).
- Review 34 best rare earth metal stocks that have already been filtered for quality to gain exposure to structural demand for critical metals as the next commodity cycle develops.
- Explore income streams that aim to keep portfolios steady while yields remain elevated by checking a curated set of 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com