


Is Cardinal Health (CAH) Cheap As Its CVS Deal Extension Locks In Revenue Visibility?
Cardinal Health (CAH) drew fresh attention after signing a binding Letter of Intent to extend its distribution agreement with CVS Health through June 2032, reinforcing long-term contract visibility for the wholesaler.
The renewed CVS agreement lands while Cardinal Health’s share price has eased, with a 30 day share price return down 5.17% and a 90 day share price return down 6.88%, even though the year to date share price return is up 8.16% and the 1 year total shareholder return is 42.22%. This reinforces that long term investors have seen strong gains even as recent momentum has softened.
Scan how Cardinal Health compares with other contract-backed distributors and large healthcare players by reviewing the hand picked list of solid balance sheet and fundamentals (25 results) that also lean on recurring revenue agreements.
Cardinal Health is trading lower over the past quarter just as a major customer relationship is being locked in for longer. Is that move saying more about the business, or about shifting sentiment around the stock as investors weigh valuation next?
Most Popular Narrative: 18% Undervalued
Cardinal Health closed at $222.50 while the most followed narrative pegs fair value near $270.94. The recent pullback sits against a thesis that leans on higher margin services, specialty distribution and a repaired medical products base.
The expansion of specialty pharma distribution, multi specialty MSO platforms in areas like oncology, urology and gastroenterology, and a rapidly scaling Biopharma Solutions business that is ahead of its prior growth plan points to a larger mix of higher value services that can influence segment profit and overall earnings.
See why 48 investors see Cardinal Health as 18% undervalued.
Result: Fair Value of $270.94 (UNDERVALUED)
Still, Cardinal Health faces real pressure points, including product quality issues around levothyroxine recalls and sensitivity in its Global Medical segment to fuel and commodity costs.
Find out about the key risks to this Cardinal Health narrative.
Another View on Cardinal Health’s Valuation
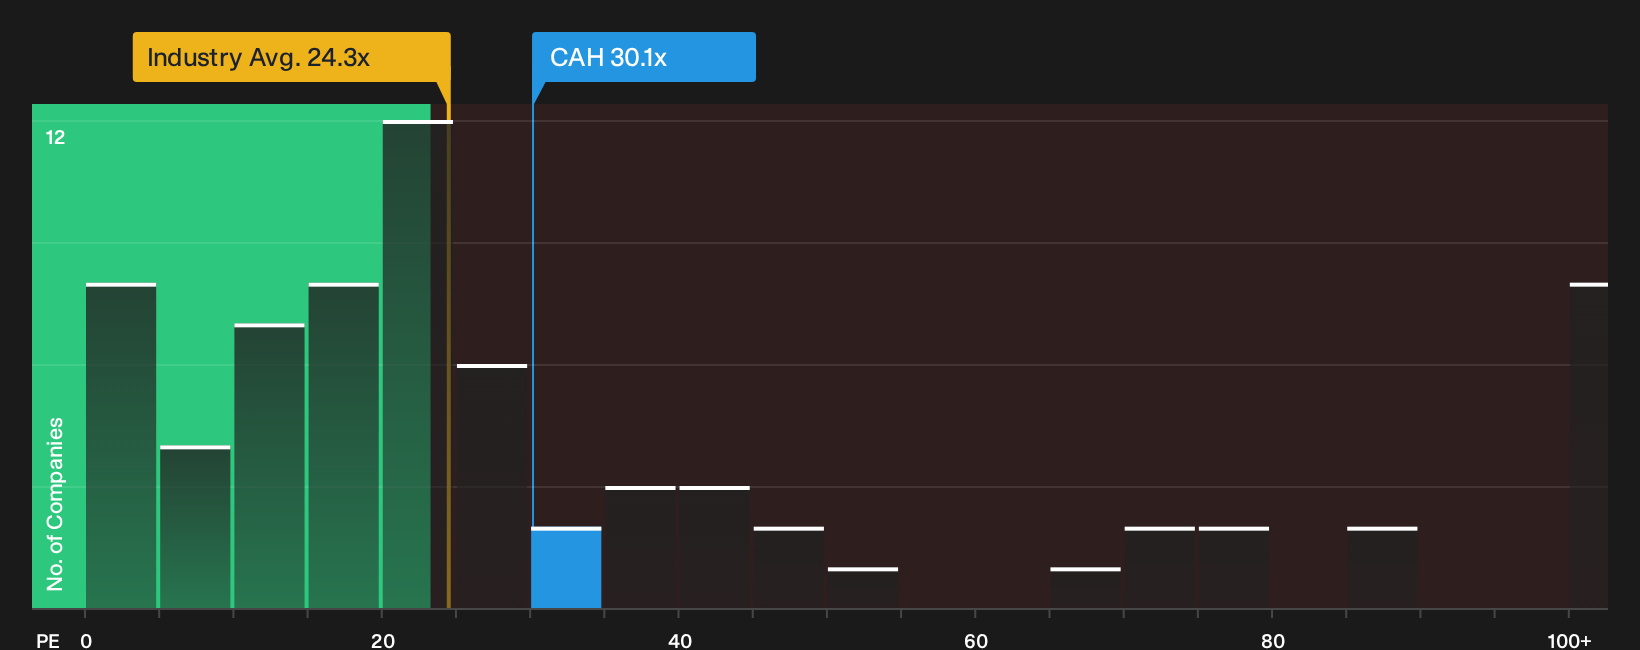
The first fair value estimate for Cardinal Health leans on analyst earnings forecasts and price targets. A second lens looks at the current P/E of 30.1x, which is higher than both the US Healthcare industry at 24.3x and peers at 25.6x, yet still below a fair ratio of 32.4x that the market could move toward. That split between expensive versus fair value raises a blunt question for you as an investor. Is this pricing closer to a premium you are comfortable paying, or a margin of safety you feel confident relying on next?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed sentiment around Cardinal Health is clear. Move quickly, review the numbers for yourself, and weigh both sides through the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Cardinal Health?
You have already done the hard work by digging into Cardinal Health. Do not stop there when more opportunities might be sitting just outside your current watchlist.
- Target dependable cash generators by scanning companies with resilient fundamentals through the 31 resilient stocks with low risk scores.
- Hunt for potential mispricings by running a quick pass over the 31 high quality undervalued stocks to see which stocks the market may be overlooking.
- Broaden your watchlist with quality plays by checking the 19 high quality undiscovered gems before other investors focus on them.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com