


Behind the Multibillion-Dollar Turnaround: 3 Catalysts Positioning This Stock to Race Ahead
Key Points
Stellantis has brought on thousands of new quality engineers, efficiency-driven software engineers, and other new hires to support its Value Creation Program.
The auto industry is poised to evolve more in the next decade than it has in a century. That could help change the low-margin narrative the industry has suffered.
Pent-up demand in more affordable vehicle segments could be the perfect opportunity for Stellantis to quickly retake lost market share.
Investors get caught in the trap of throwing around massive headline figures, but perhaps without grasping the gravity of those figures. A great example is Stellantis (NYSE: STLA), a global legacy automaker with the heart and soul of Detroit combined with a European flair, that over the summer announced a $70 billion turnaround strategy.
For context, Stellantis has spent roughly $50 billion in capital expenditures over the five-year period from 2021 through 2025. By the way, that $70 billion strategy compares to Stellantis' total market capitalization of less than $12 billion.
Missed AI’s "Act 1"? Act 2 Could Be 15x Bigger. Most investors think they missed the AI boat because they didn't buy Nvidia in 2005. But according to our analysts, we’re only at the end of "Act 1"—the R&D phase. "Act 2" is the global rollout. Continue »
Fear not, brave potential Stellantis investors! Here are three reasons to believe the beaten-down and heavily sold-off automaker can turn its business around and send a much-needed jolt to its stock price over the next three years.
Talent onboarding
When companies face plunging corporate morale and elevated concerns, it's not unusual to see an exodus of talent. Fortunately, Stellantis has been working to shape the narrative in a completely different way. It started by hiring an unprecedented number of more than 2,000 new engineers in North America who will become the backbone of designing high-demand vehicles, improving vehicle quality, accelerating the time to develop a new car from start to finish, all while not falling too far behind in the transition to electric vehicles (EVs).
Those factors are all incredibly important as Stellantis is tasked with launching more than 60 new vehicles by the end of 2030.
Another portion of these hires will feed into Stellantis' new "Value Creation Program," which is tasked with achieving roughly $7 billion in cost savings by the end of 2028. In addition to the hardware talent influx, Stellantis announced long-term targets to bring in 4,500 efficiency-driven software engineers globally.
Narrative changes
With 2025 being a dark year for Stellantis, there was little choice but to improve the narrative. Stellantis improved its net revenue by 10% through the first half of 2026, compared to the same time period a year ago. After losing 2.3 billion euros during the first half of 2025, Stellantis reversed those losses and recorded a 670 million euro net profit during the first half of 2026. Industrial free cash flow improved by more than 2 billion euros and is on pace to return to positive territory in 2027.
A bigger-picture development for investors to chew on is the broader transition to software-defined vehicles. Software-defined vehicles are known for the technologies and capabilities they offer, such as over-the-air updates that can prevent a return trip to the dealership. These newer vehicles can also offer services, subscriptions, on-demand features, and data-as-a-service for fleet operators, among other things.
Most importantly, software-defined vehicles and services are helping change the narrative on automaking being a low-margin industry. These software and subscription services can generate gross margins of nearly 70% compared to the 5% to 10% margins from traditional car sales, and will one day play a much larger role in automakers' bottom line.
Affordability has upside
Automakers are in a unique position, as many focused on selling fewer but higher-priced vehicles during COVID-19; in the years since the pandemic, the average cost of a new vehicle has risen to a record high of around $50,000. That's created a lack of affordable options, and the lower-price segment has pent-up demand. While Jeep and Ram will focus on high-margin product lines, Stellantis can use its regional brands, such as Chrysler and Dodge, to attack more affordable segments to regain lost market share, increase sales volume, and improve production utilization in its factories, a long-term goal amid its turnaround.
Stellantis plans to introduce 11 all-new vehicles in North America by 2030: Seven of those will be priced under $40,000, and two will be priced under $30,000. If Stellantis creates compelling, valuable, and more affordable all-new vehicles and can stay profitable at those lower price points, it would be a big win for the automaker's turnaround. Already, investors saw a bit of good news when Stellantis reported that second-quarter North American shipments soared 38% compared to the prior year, suggesting that, in addition to preloading inventory for a planned summer shutdown, newer models are gaining sales momentum.
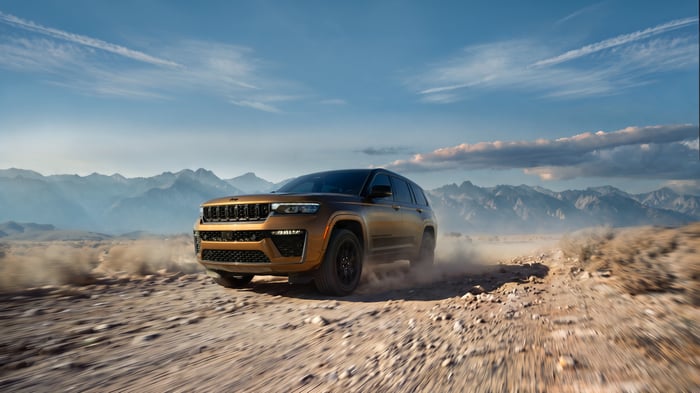
While Dodge and Chrysler focus on affordability, Jeep will play a pivotal role in improving market share and margins. Image source: Stellantis.
Is it time to buy?
One problem that has plagued Stellantis in recent years was its lack of identity. The automaker did make a critical decision to focus a significant portion of its product investment on four key global brands that offer the greatest scale and highest profit potential: Jeep, Ram, Fiat, and Peugeot.
The company is also embracing its Detroit roots and focusing on its core profit engine, North America. In fact, Stellantis is committing about 60% of its total $70 billion strategy directly to North America. Jeep and Ram will play a huge role in the company's ability to increase profitability with their competitiveness in high-margin trucks and SUVs. Some analysts wanted to cull ineffective brands, and that's fair, but Stellantis has more of an identity and path forward now than it has in years.
Stellantis is bringing in a massive wave of talent to improve quality and develop a crowded pipeline of new vehicles, and has taken important early steps in its financial recovery. The stock has a lot of potential upside over the next five years if investors have a healthy appetite for risk.
Daniel Miller has no position in any of the stocks mentioned. The Motley Fool recommends Stellantis. The Motley Fool has a disclosure policy.