


Dropbox (DBX) Stock Still Looks Undervalued As It Gains 26%
Dropbox shares have climbed strongly this year, which puts fresh attention on whether the current valuation really lines up with what the business is earning today. With the stock now trading well above where it started the year, investors are increasingly focused on how much of Dropbox's earnings power is already reflected in the price.
- The stock is up 25.7% year to date, which raises the question of how much further upside its current earnings profile can reasonably support.
- The company leans heavily on subscription-based revenue and a software cost base, so profit margins and cash generation can be key to how much investors are prepared to pay for its earnings.
- Your read on Dropbox is one view; the desks covering it have another. See what analysts think Dropbox's shares could be worth.
The issue now is whether Dropbox's recent share price level is justified by its earnings when measured against the Fair Ratio benchmark.
If you are weighing whether Dropbox's current P/E makes sense against its earnings, it can help to compare that question across 31 high quality undervalued stocks.
Is Dropbox Still Cheap on Earnings?
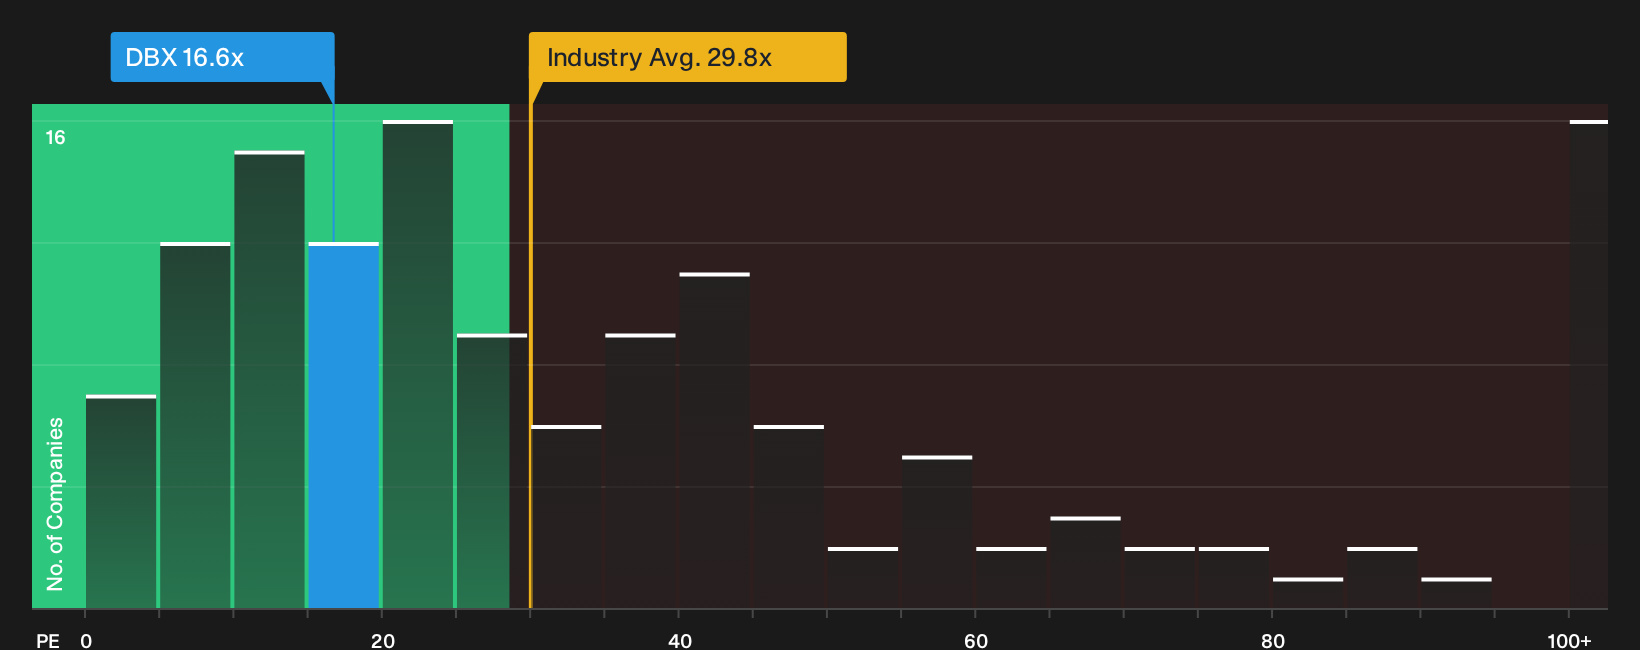
The P/E ratio suits Dropbox because earnings are a key anchor for a subscription software model. On this measure, the stock trades on about 16.6x earnings, which is well under the broader Software industry average of roughly 29.8x. Against a peer cohort closer to 31.3x, the gap is also wide. This indicates that the market is pricing Dropbox’s earnings at a lower multiple than many comparable software businesses.
The Fair Ratio, which reflects what investors might usually pay given Dropbox’s growth prospects, profitability profile, size and risk, sits above where the current P/E has settled. On this framework, the shares appear undervalued, with the market paying less for each dollar of earnings than that tailored benchmark implies could be reasonable. For anyone weighing whether the recent share price move has already used up the upside on earnings, the spread between the 16.6x P/E and those reference points is the key question to work through. Explore the numbers behind Dropbox's P/E valuation.
The Dropbox Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Dropbox pick up where the P/E debate leaves off and spell out the specific growth, margin and earnings paths that would need to hold for the stock to be worth materially more or less than today's price on the Community page. Instead of a single output from a ratio or model, they lay out the future that number quietly assumes so you can watch how Dropbox's actual progress lines up with it over time.
One of the top community narratives on Dropbox: roughly fairly valued
"The company's strategy to achieve growth via new products like Dash is still in early stages, with management conceding it will take time…"
Discover why this Narrative puts Dropbox at roughly fairly valued.
One more big question for Dropbox that this valuation does not answer
Valuation only captures where Dropbox is priced today, while analysts have already mapped out where they expect the business to be several years from now, which gives you a different lens on what the current multiple is really saying. Explore where analysts expect Dropbox to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com