


2G Energy (XTRA:2GB) Has The Market Asking A Bigger Question
2G Energy (XTRA:2GB) is back in focus after reporting third quarter new orders above €400 million, supported by a 275 MW contract with Energy Vault for AI and data center power infrastructure in the United States.
Despite the third quarter order momentum, 2G Energy’s share price has been choppy in recent months, with the stock up 10.37% over 30 days but down 10% over 90 days. However, a 69.76% year to date share price return and 89.29% one year total shareholder return hint that longer term momentum is still intact.
Scan for other power and data infrastructure plays that may be benefiting from similar AI data center demand with the hand-picked 90 AI infrastructure stocks.
2G Energy now looks like a solid operator with fresh visibility from AI linked orders, yet the share price has already run hard. The real issue is how that story lines up with what you are paying today.
Price-to-Earnings of 65.5x: Is it justified?
On simple earnings math, 2G Energy is not cheap. The share price of €61.2 equates to a P/E of 65.5x, which is well above both peer and sector references.
The P/E ratio compares what you pay per share to the profit that share currently represents. For a manufacturer of energy systems like 2G Energy, a rich P/E often signals that investors are leaning heavily on future earnings growth rather than today's profitability.
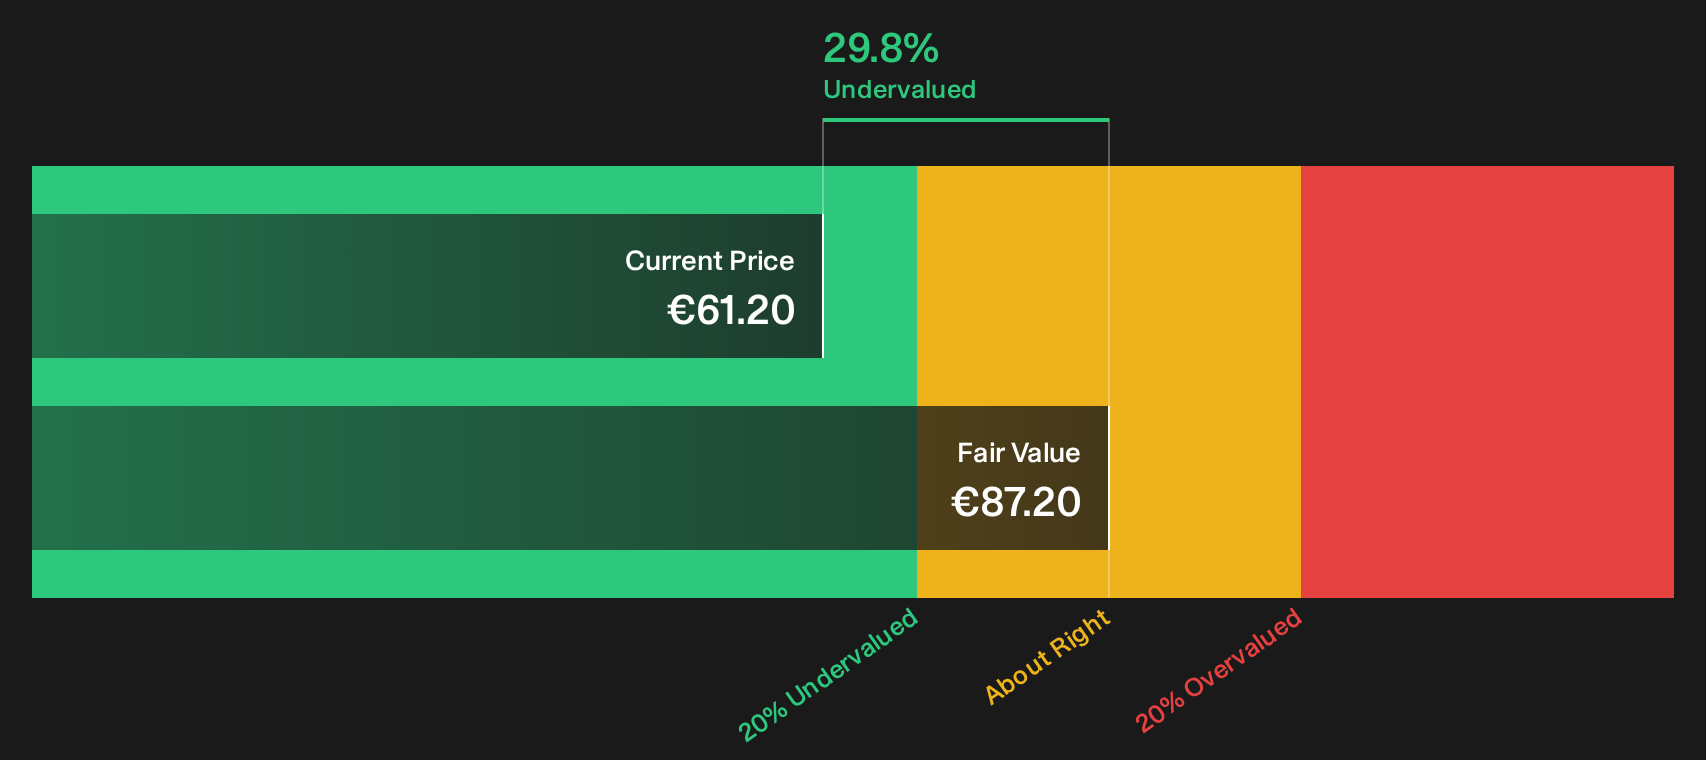
Analysts currently forecast revenue growth of 21.2% per year and earnings growth of 30.2% per year, which helps explain why the market is comfortable paying a premium multiple to current profits. That said, the same stock is described as trading 29.8% below an estimated fair value based on the SWS DCF model, so the P/E and the cash flow valuation are sending very different messages about what might be baked into the price.
Compared with an Electrical peer average P/E of 22.6x and a European Electrical industry average of 26.8x, 2G Energy trades on a much richer earnings multiple. The fair P/E estimate of 29.7x is also less than half the current 65.5x level. This suggests the ratio could have plenty of room to compress if sentiment cools.
Explore the SWS fair ratio for 2G Energy.
Result: Price-to-Earnings of 65.5x (OVERVALUED)
Still, the 2G Energy story can be knocked off course if AI data center orders slow or if high expectations meet execution hiccups on large projects.
Find out about the key risks to this 2G Energy narrative.
Another View on 2G Energy's Value
On the flip side of that rich 65.5x P/E, the SWS DCF model points to an estimated value of €87.2 per share. With 2G Energy trading at €61.2, that implies the stock is around 29.8% below this cash flow based fair value and screens as undervalued on this measure.
This gap between earnings multiple risk and DCF upside puts the burden on you to decide which lens feels more convincing for 2G Energy. Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out 2G Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 191 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Plenty in the 2G Energy story looks promising, yet parts of the setup clearly worry investors. It may be helpful to move quickly, review the full data, and weigh both the 2 key rewards and 3 important warning signs.
Looking for more 2G Energy style investment ideas?
If you stop with just 2G Energy, you could miss other opportunities with strong fundamentals and different risk profiles that might suit your portfolio even better.
- Target potential mispricings by scanning companies that combine quality fundamentals with discounted valuations through the 191 high quality undervalued stocks.
- Prioritise resilience by focusing on businesses with sturdy finances and reliable balance sheets using the list of solid balance sheet and fundamentals (205 results).
- Hunt for lesser known opportunities with strong metrics before they gain broad attention by running the 617 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com