


Intellia Therapeutics (NTLA), What Is Drawing Fresh Attention Now?
Intellia Therapeutics (NTLA) has stayed in focus after recent price moves, with the stock closing at US$12.06. Investors are weighing that level against the company’s clinical-stage CRISPR pipeline and collaboration footprint.
For context, the recent move around US$12.06 comes after a year where the share price return is up 30.94% year to date, but the 1 year total shareholder return has declined 41%, so momentum has picked up in the short term while longer term holders still face heavy drawdowns.
Compare Intellia Therapeutics with a curated group of other high potential biotech opportunities by checking out 19 high quality undiscovered gems while this renewed momentum in gene editing stays in focus.
Intellia Therapeutics now trades near multi year lows while carrying a clinical pipeline and partner roster that many investors view as strong. Is that gap a bargain or a value trap as the valuation work begins?
Most Popular Narrative: 49.6% Undervalued
Compared with the last close at $12.06, the most followed fair value estimate for Intellia Therapeutics sits at $23.94. This frames the story around late stage trial execution and cash discipline rather than near term earnings.
Growing patient and physician enthusiasm for Intellia's lead in vivo CRISPR therapies is driving faster-than-expected enrollment across multiple late-stage clinical trials (including an expanded 1,200-patient ATTR cardiomyopathy study and strong uptake in HAE). This is positioning the company to achieve meaningful clinical readouts and regulatory milestones ahead of prior guidance. This advances timelines to potential commercialization and drives long-term revenue growth prospects.
See why 86 investors see Intellia Therapeutics as 50% undervalued.
Result: Fair Value of $23.94 (UNDERVALUED)
Still, if the resumed Phase 3 programs encounter new safety issues or if cash burn forces heavier dilution, the bullish Intellia Therapeutics narrative could unravel quickly.
Find out about the key risks to this Intellia Therapeutics narrative.
Another View: Intellia Therapeutics Looks Expensive On Sales
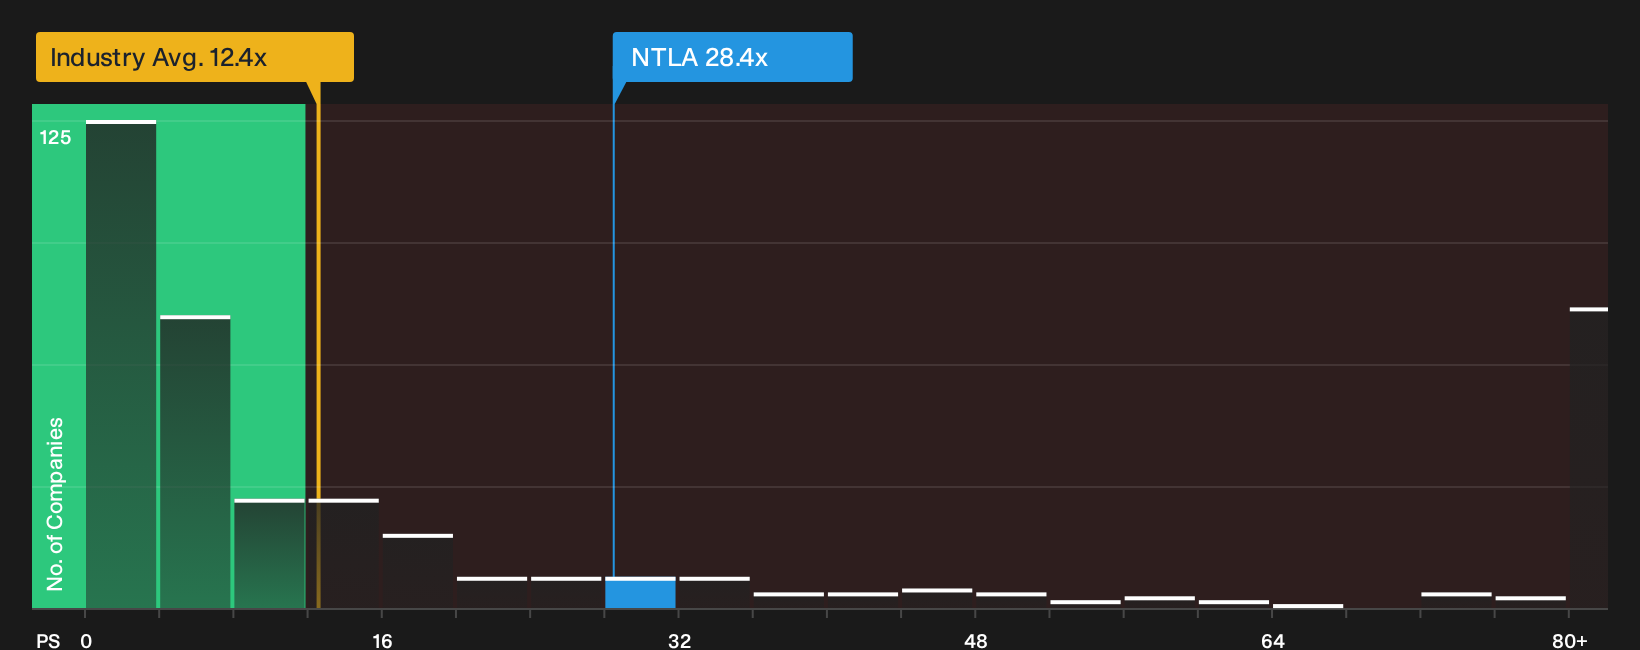
On the flip side of that fair value story, Intellia Therapeutics trades on a P/S ratio of 28.4x. The broader US Biotechs group sits around 12.4x, while the peer average is 24.6x and the fair ratio is just 0.1x, which flags real valuation risk if sentiment turns.
For investors who prefer to anchor decisions on revenue multiples rather than long range cash flow models, that gap raises a simple question. Is this pricing power or just hope being capitalized into the share price, and how much downside are you willing to underwrite if expectations reset like the fair ratio implies, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Intellia Therapeutics story can be useful if you move quickly and stress test the numbers yourself instead of relying on headlines. To balance the upside potential against the concerns already flagged, take a closer look at 2 key rewards and 2 important warning signs.
Looking for more Intellia Therapeutics investment ideas?
If Intellia Therapeutics has your attention, do not stop with a single ticker. Cast the net wider so you are not relying on one story.
- Target resilient balance sheets by scanning the list of solid balance sheet and fundamentals (25 results) and compare Intellia Therapeutics with companies that carry cleaner funding profiles.
- Hunt for mispriced quality by reviewing the 31 high quality undervalued stocks and see which businesses combine appealing valuations with stronger fundamentals than Intellia Therapeutics.
- Reduce portfolio stress by filtering for steadier prospects using the 31 resilient stocks with low risk scores before short term headlines around Intellia Therapeutics push you into rushed decisions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com