


Should LNG Canada Contract Win Require Action From JGC Holdings Stock Investors?
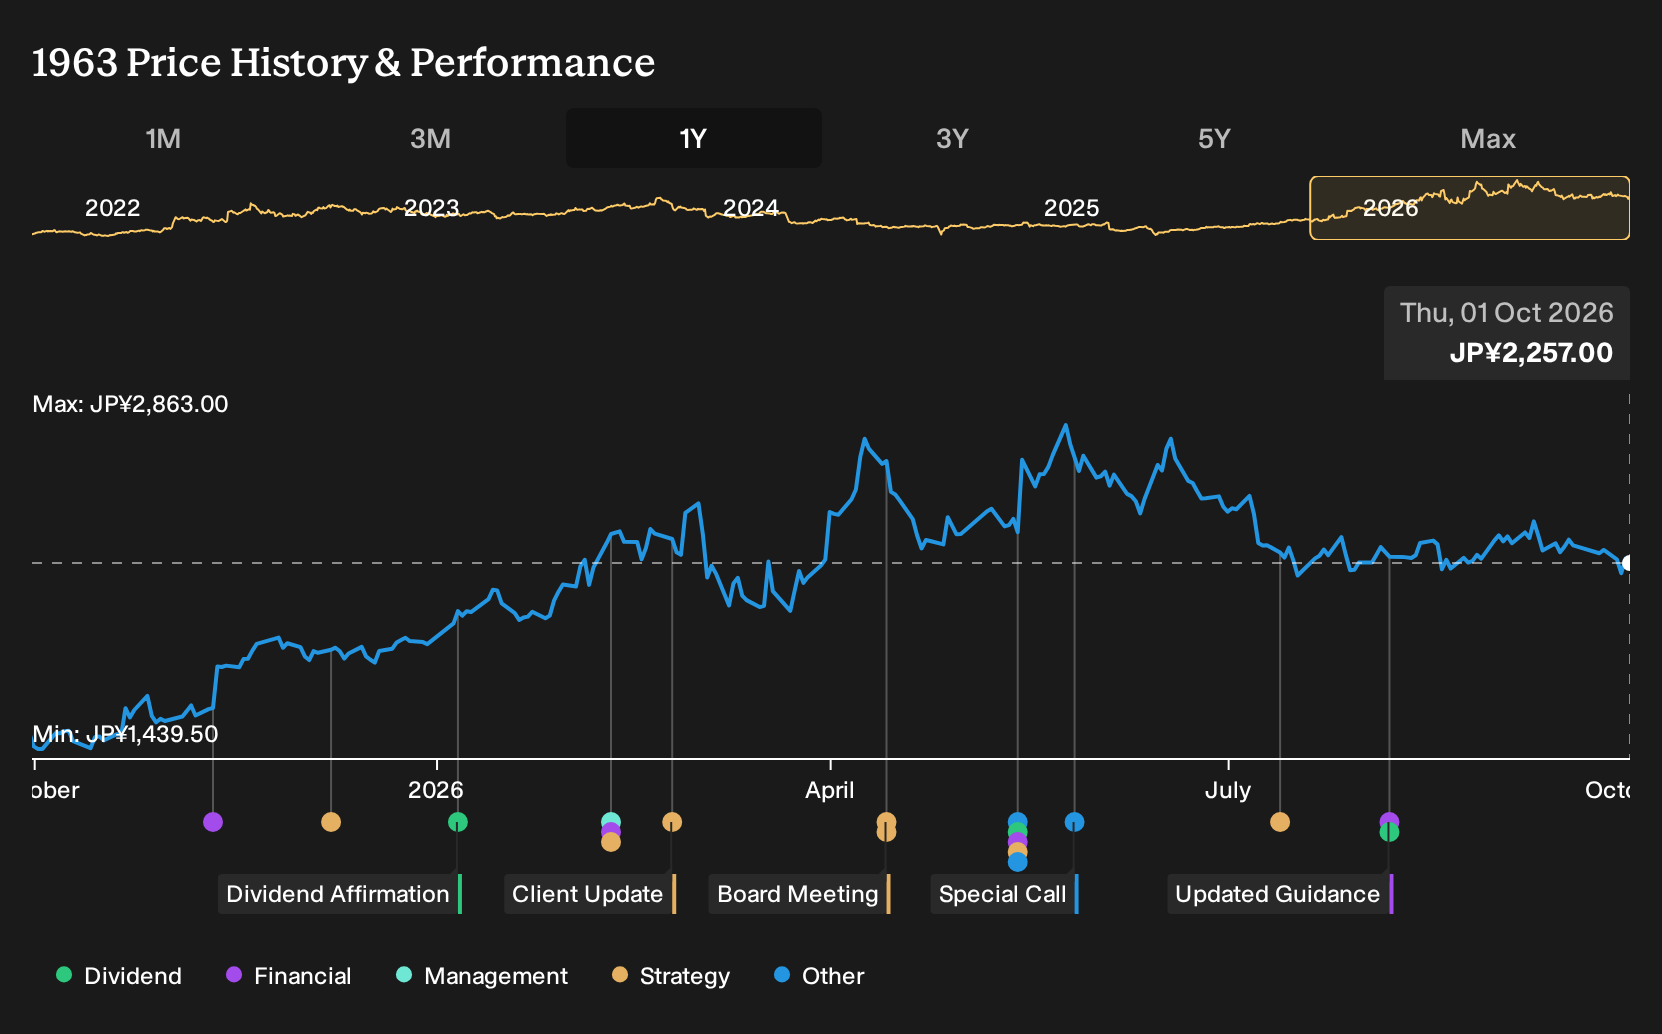
- JGC Holdings, through subsidiary JGC Corporation, previously secured a share of a US$7.5b LNG Canada Phase 2 contract with Fluor, covering engineering, procurement, fabrication, construction and commissioning to add two liquefaction trains and one storage tank.
- The LNG Canada Phase 2 award reinforces JGC Holdings' exposure to large, complex LNG engineering work. It highlights both revenue potential and execution risk on a single, high profile project.
- We will now assess how JGC Holdings' expanded LNG Canada role could reshape the existing investment narrative around project risk and earnings quality.
Scan how JGC Holdings fits into the LNG and infrastructure build out by comparing it with a curated 39 power grid technology and infrastructure stocks that could also benefit from large capital projects.
JGC Holdings Investment Narrative Recap
To own JGC Holdings, you need to be comfortable with a contractor that leans heavily on large LNG and energy projects while trying to tighten project control. The LNG Canada Phase 2 award increases order visibility and keeps the engineering backlog supported, but it also concentrates execution risk in one more complex, multi year contract.
The key short term swing factor remains whether management can avoid fresh cost overruns on big EPC work while keeping recently restored profitability intact. This new contract does not change that core debate. It simply raises the stakes on risk management, subcontractor stability, and cost inflation across the Total Engineering segment.
With no new company announcements disclosed alongside LNG Canada Phase 2, the most relevant reference point is still the earlier focus on governance and senior management restructuring. That effort is aimed at tighter risk control and more disciplined project selection across JGC Holdings, especially in Total Engineering.
If those internal changes translate into cleaner execution on LNG Canada and other large jobs, they could support the backlog driven catalyst of more stable earnings and cash flow. If not, the same contract that extends LNG exposure and revenue visibility could reinforce existing concerns around margins, loss provisions, and dividend reliability.
JGC Holdings' current analyst narrative points to forecast revenues of ¥844.5b and consensus earnings of ¥46.4b by 2029, based on an assumed 4.3% yearly revenue growth rate and an earnings increase of ¥4.6b from earnings today of ¥41.8b.
Uncover why JGC Holdings' fair value indicates a 14% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on JGC Holdings’ LNG pipeline as a catalyst. Before this news, they were pencilling in ¥884.4b of revenue and ¥46.8b of earnings by 2029, assuming 7.4% yearly growth. You can see how a contract like LNG Canada Phase 2 might prompt them to revisit those already upbeat assumptions.
Explore 2 other JGC Holdings fair value estimates, including one that suggests up to 14% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your JGC Holdings research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for JGC Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate JGC Holdings' overall financial health at a glance.
Looking for more JGC Holdings style investment ideas?
If you want to balance JGC Holdings with other opportunities, the Simply Wall St Screener helps you quickly scan for different types of stocks that fit your risk and return preferences.
- For investors who care most about resilient balance sheets and solid fundamentals, start with a curated list of solid balance sheet and fundamentals (23 results) that can help you stress test your portfolio against financial risk.
- If income is a key part of your plan, use a set of high yield 20 dividend fortresses to spot companies offering stronger cash returns today.
- When you are hunting for overlooked opportunities with stronger quality markers, cast a wider net through a group of 76 high quality undiscovered gems that might not yet be on every investor's radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com