


What The PENN Entertainment Bears Got Right, And Where It Is Playing Out Again
If you backed PENN Entertainment on the promise of ESPN integration and riverboat-to-land projects transforming the business, the ride since last autumn has been rough. For PENN Entertainment shareholders, the loss over the past year was 23.5%, including dividends. If you were weighing a purchase in late September 2025, with analysts split between upbeat ESPN-led growth and caution over regulation, debt and weak Interactive economics, which of those specific assumptions most clearly missed reality?
PENN Entertainment is not the only name tied to this theme. Zero in on 92 robotics and automation stocks and compare how each one is priced.
The Two PENN Entertainment Stories Investors Had To Weigh
The shares cost US$19.26 at the start of the period, and anyone looking at PENN Entertainment then had to choose between two quite different stories about what came next.
The optimistic view pointed to a Fair Value of US$22.11, a notional price implied by assumptions that deeper ESPN integration and omni-channel investments would lift user engagement, support double digit revenue growth and improve profit margins from a loss into positive territory.
The cautious narrative saw Fair Value nearer US$17, based on expectations that rising gaming taxes, regulatory tightening and a heavy debt load would cap revenue growth at 3.6% and limit margins to 3.4%.
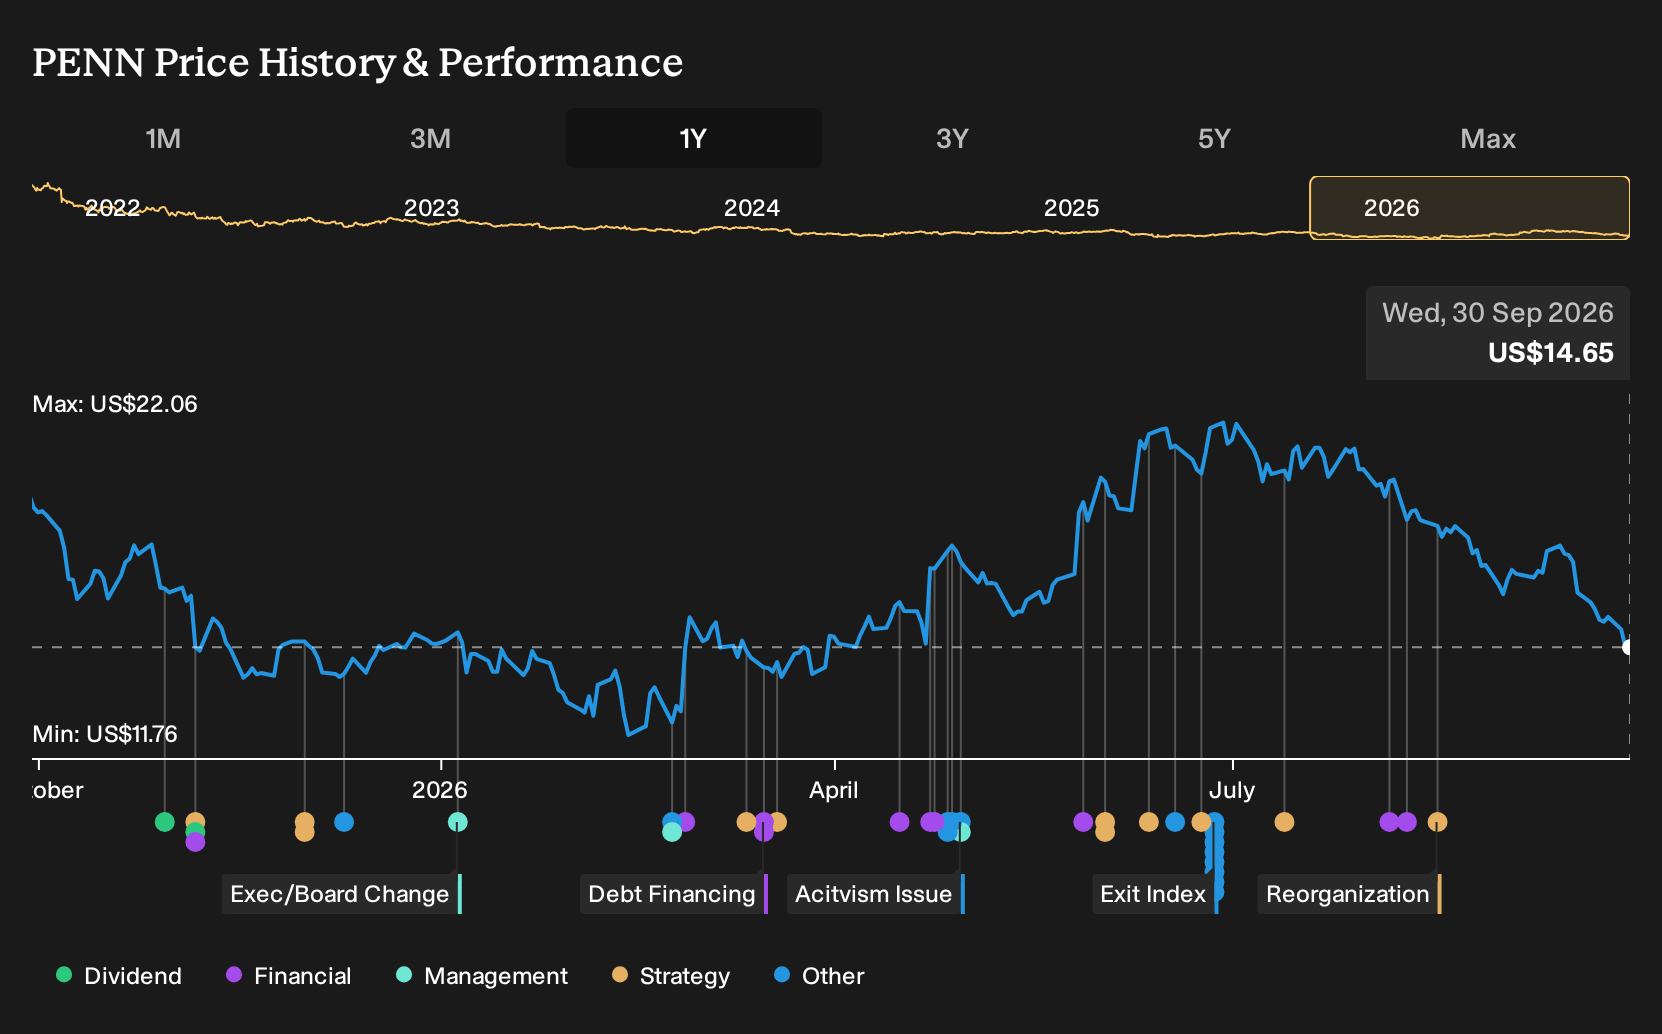
What The Results Changed For PENN Entertainment
PENN Entertainment’s Q2 2026 update showed total revenue at US$1,857.4 million and net income at US$33.1 million, compared with US$1,765 million revenue and a loss of US$17.4 million a year earlier. Net margin moved from a loss of 1.0% to a positive 1.8%, which supported parts of the optimistic case on profitability, although the ESPN driven user story was not directly tested.
The key lesson is about what to watch. For any omni channel or media tie up story, it is worth tracking segment level profit, reported net margin and concrete project milestones, rather than assuming headline partnerships automatically translate into durable earnings.
What PENN Entertainment’s Lower Price Is Asking You To Believe
PENN Entertainment trades at US$14.65 today, with this Narrative’s Fair Value set above that level based on its own assumptions rather than hard fact. The argument leans on ESPN integration, digital scaling and fresh bricks and mortar projects working together to reshape earnings power.
If you buy at today’s price, you would be relying on PENN Entertainment converting ESPN driven traffic and omni channel loyalty into meaningfully stronger digital economics and sustained property level returns.
"Key Takeaways: Deep ESPN integration and a scalable digital platform position PENN for accelerated user growth, digital leverage, and substantial share gains in online betting and iCasino markets. Omni-channel innovations and hospitality expansions drive greater loyalty, efficiency, and margin upside, with ongoing personalization efforts supporting industry-leading customer value and long-term earning power."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Where PENN’s Theme Might Echo
PENN leans on media, loyalty and habit. Your attention does not stop there.
When people plan trips or weekend getaways around sports, they also decide where to stay. One digital platform quietly matches those plans with places.
It earns money by connecting guests and hosts instead of owning rooms. That model keeps fixed assets lighter and shifts focus toward software and data.
Faster feature launches, new trip add ons and AI tools could change how that marketplace captures value from each booking.
For travelers and investors, the next upgrade might arrive inside the itinerary, not just on the screen.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 37% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com