


Global Growth Companies With High Insider Ownership For October 2026
As global markets navigate the complexities of inflation concerns and interest rate fluctuations, growth stocks have shown resilience, particularly in sectors like information technology and communication services. In this environment, companies with strong insider ownership can be appealing as they often reflect a high level of confidence from those who know the business best.
Top 10 Growth Companies With High Insider Ownership Globally
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 74.9% |
| Shanghai Biren Technology (SEHK:6082) | 10.4% | 119.7% |
| Meitu (SEHK:1357) | 23% | 26.7% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| JHT DesignLtd (SHSE:603061) | 23.1% | 48.6% |
| Guangdong Shenling Environmental Systems (SZSE:301018) | 36.7% | 65.4% |
| Great Microwave Technology (SHSE:688270) | 21.1% | 95.2% |
| Fulin Precision (SZSE:300432) | 11.2% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Let's uncover some gems from our specialized screener.
ABL Bio (KOSDAQ:A298380)
Simply Wall St Growth Rating: ★★★★★☆
Overview: ABL Bio Inc. is a biotech research company specializing in the development of therapeutic drugs for immuno-oncology and neurodegenerative diseases, with a market cap of ₩2.72 trillion.
Operations: Revenue segments for ABL Bio Inc. are not provided in the available text.
Insider Ownership: 25.8%
Revenue Growth Forecast: 29.8% p.a.
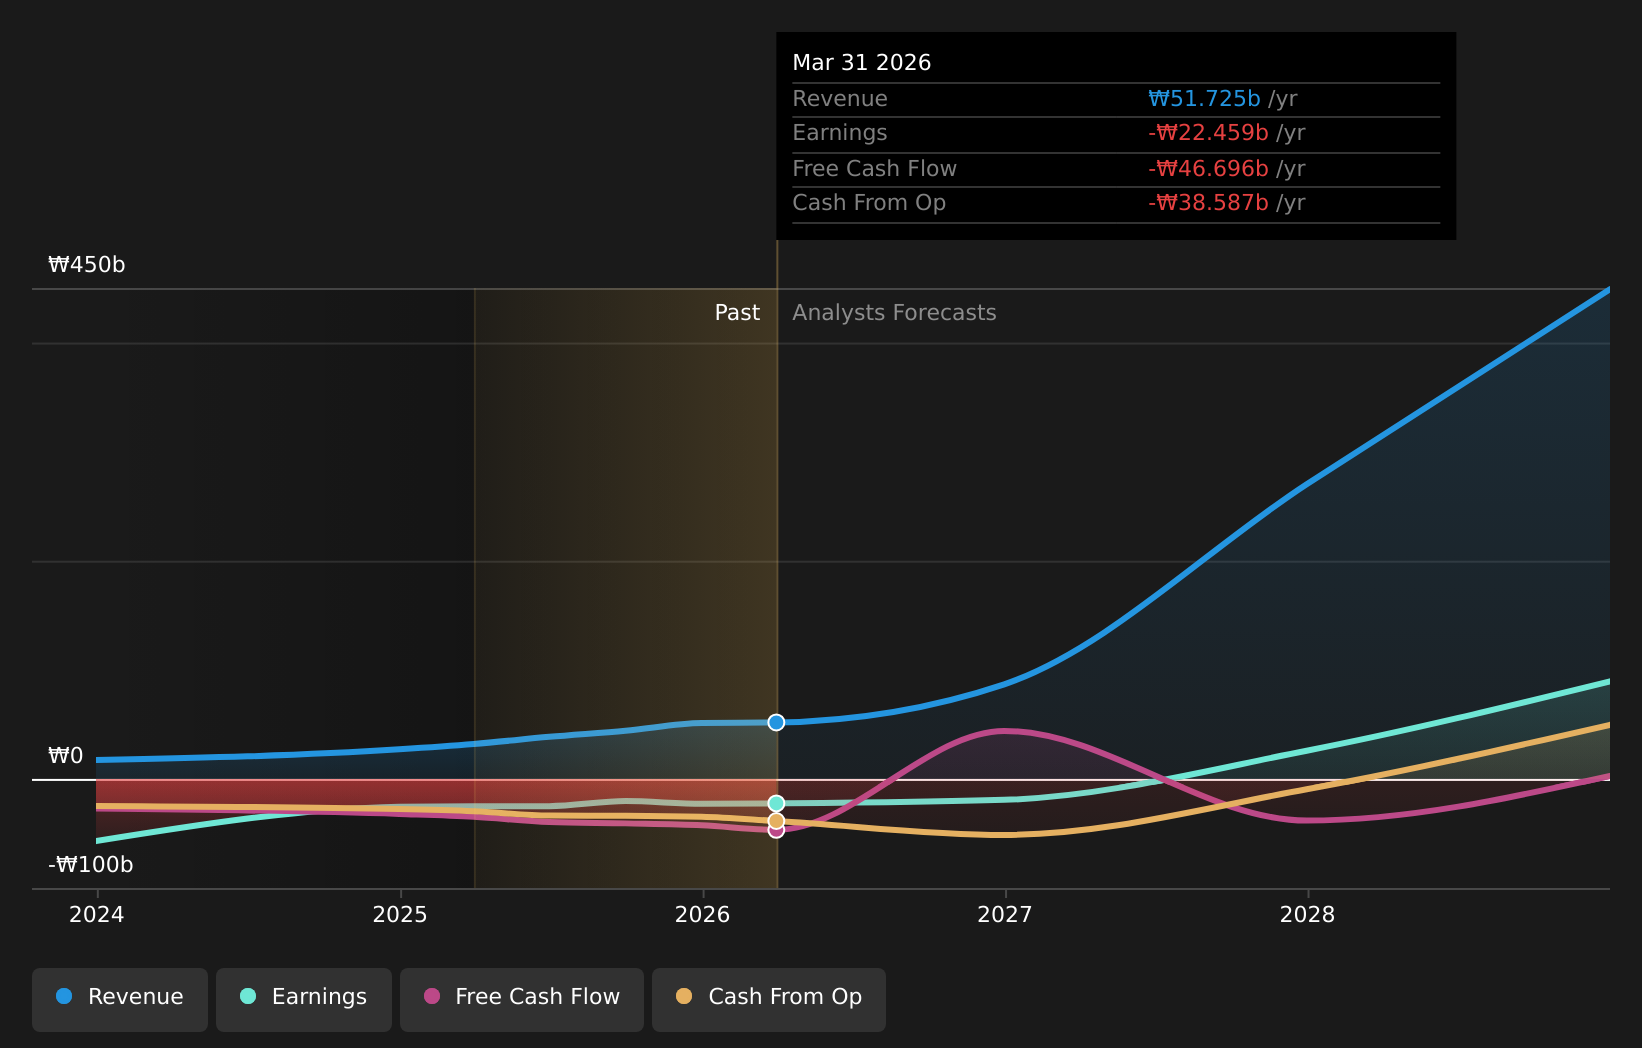
ABL Bio is expected to achieve profitability within three years, with earnings projected to grow 82.95% annually and revenue at 29.8% per year, outpacing the KR market's growth rate. Analysts predict a significant stock price increase of nearly 400%. Despite no recent insider trading activity, these forecasts suggest potential strong performance for investors interested in growth companies with substantial insider ownership.
- Click here and access our complete growth analysis report to understand the dynamics of ABL Bio.
- The analysis detailed in our ABL Bio valuation report hints at an inflated share price compared to its estimated value.
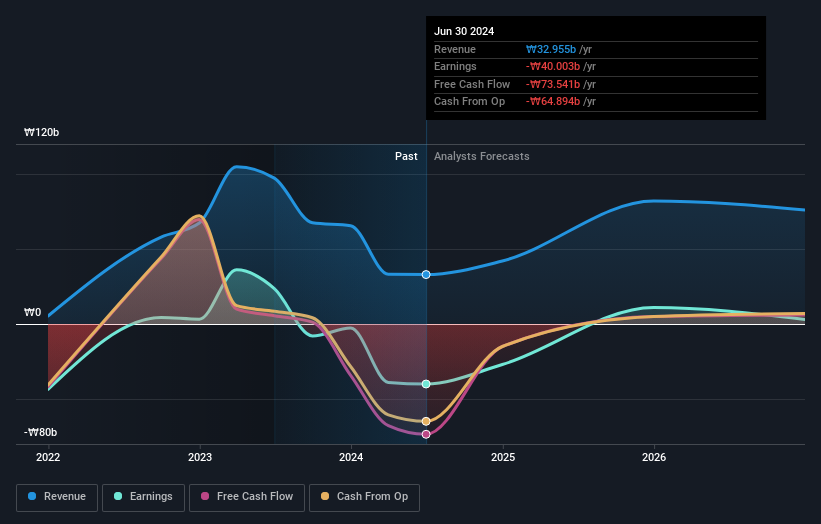
Livsmed (KOSDAQ:A491000)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Livsmed Inc. is a South Korean company involved in the research, development, manufacture, export, and import of electro-diagnostic and electro-therapeutic medical devices with a market cap of approximately ₩766.38 billion.
Operations: The company's revenue primarily stems from its activities in the research, development, manufacturing, exportation, and importation of electro-diagnostic and electro-therapeutic medical devices within South Korea.
Insider Ownership: 39%
Revenue Growth Forecast: 52.6% p.a.
Livsmed is forecast to experience substantial revenue growth of 52.6% annually, significantly outpacing the KR market's 13.6%. Earnings are projected to grow by 88.23% per year, with profitability expected within three years. Despite a highly volatile share price and low future Return on Equity at 7%, Livsmed remains an intriguing option due to its rapid growth potential, although it faces financial constraints with less than one year of cash runway.
- Delve into the full analysis future growth report here for a deeper understanding of Livsmed.
- Our comprehensive valuation report raises the possibility that Livsmed is priced higher than what may be justified by its financials.
Foosung (KOSE:A093370)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Foosung Co., Ltd. operates in South Korea, manufacturing and selling chemical products for the automotive, iron and steel, semiconductor, construction, and environmental industries with a market cap of ₩1.61 trillion.
Operations: Foosung Co., Ltd. generates revenue through the production and sale of chemical products catering to the automotive, iron and steel, semiconductor, construction, and environmental sectors in South Korea.
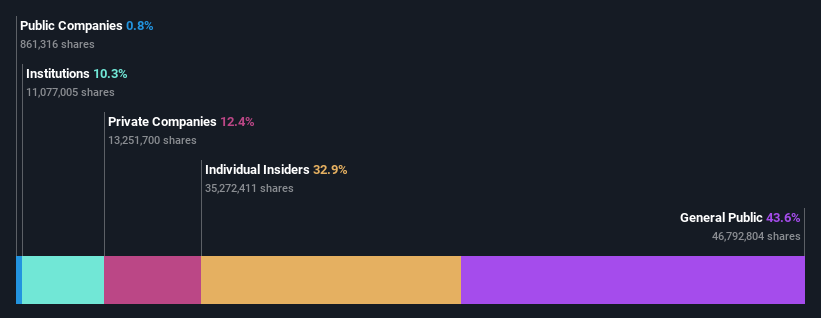
Insider Ownership: 32.9%
Revenue Growth Forecast: 16.5% p.a.
Foosung's earnings are forecast to grow significantly at 36.4% annually, surpassing the KR market's 28.3%. The company recently turned profitable, reporting a net income of KRW 21,412.59 million for Q2 2026 compared to a loss last year. However, revenue growth is slower at 16.5% per year and debt coverage by operating cash flow is weak. Despite high share price volatility and low future Return on Equity of 17.8%, Foosung exhibits promising earnings potential without recent insider trading activity.
- Unlock comprehensive insights into our analysis of Foosung stock in this growth report.
- According our valuation report, there's an indication that Foosung's share price might be on the expensive side.
Summing It All Up
- Reveal the 725 hidden gems among our Fast Growing Global Companies With High Insider Ownership screener with a single click here.
- Contemplating Other Strategies? This technology could replace computers: discover the 25 stocks are working to make quantum computing a reality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com