


Celsius Holdings (CELH) Could Be 42% Below Fair Value After Its Recent Pullback
Celsius Holdings (CELH) is back in focus after a sharp pullback, with the share price down about 11% over the past month as analysts cut earnings estimates and Zacks shifted its rating to Rank #5 Strong Sell.
Recent moves suggest momentum has been fading for Celsius Holdings, with the 30-day share price return down 10.97% and the year-to-date share price return down 42.72%. The 1-year total shareholder return has declined 53.57% as investors react to higher earnings risk and a premium P/E valuation.
Compare Celsius Holdings with a curated set of alternatives by scanning the recent pullbacks and potential rebounds across our 31 high quality undervalued stocks.
Celsius Holdings now trades well below recent highs while still carrying a premium P/E tag. Should investors put cash to work here now, or wait for the valuation to cool further before stepping in?
Most Popular Narrative: 42% Undervalued
The most followed narrative pegs Celsius Holdings at a fair value of $47.37 per share against the latest close of $27.35, which implies a wide gap that bulls see as mispricing.
I believe Celsius Holdings stock can reach a price of $47.00 per share (+42%) over the next two months, with potential to reach $71.00 per share within the next few years. This will be driven by continued earnings and revenue gains, international expansion, and the long-term integration of Alani Nu and Rockstar, which were both recent acquisitions.
See why 11 investors see Celsius Holdings as 42% undervalued.
The narrative, according to Bullish4YaMotha, leans heavily on Celsius Holdings using its Pepsi distribution partnership, broader brand portfolio and international reach to support that higher value over time. It treats the recent pullback as a temporary reset rather than a change in the longer term story.
Result: Fair Value of $47.37 (UNDERVALUED)
Still, Celsius Holdings faces real pressure if legal issues worsen or if Pepsi distribution underdelivers, as both could quickly challenge the bullish recovery story.
Find out about the key risks to this Celsius Holdings narrative.
Another View: Celsius Holdings Looks Expensive On Earnings
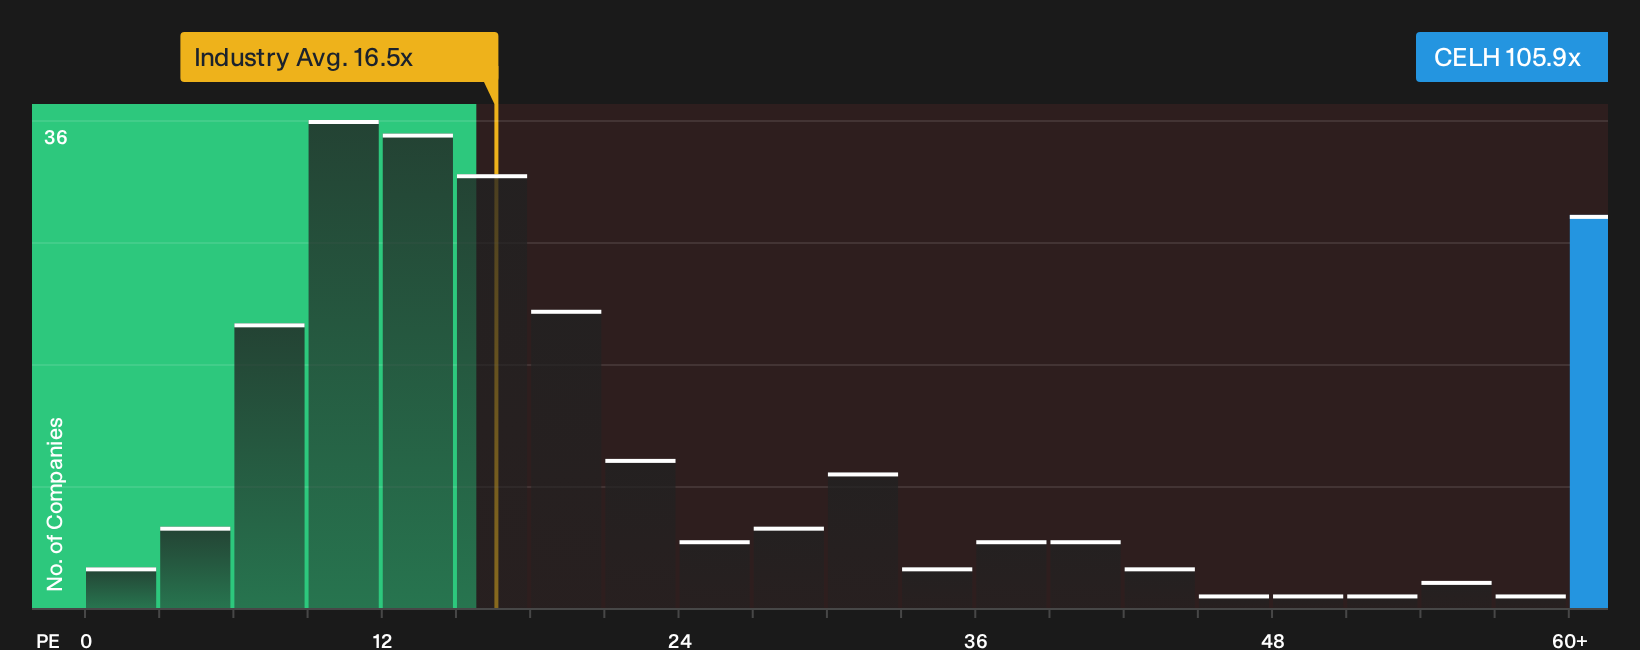
That user fair value of $47.37 leans on long term potential, but current market maths tell a tougher story. Celsius Holdings trades on a P/E of 105.9x against a global beverage average of 16.5x and a peer group near 32.8x, while the fair ratio sits at 28.6x. This gap points to meaningful valuation risk if sentiment or growth expectations cool from here. How comfortable are you paying that kind of premium for this story?
To see how this pricing compares with the underlying earnings profile in more detail, take a look at the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Celsius Holdings draws strong views on both sides, so do not wait for consensus to form before checking the data and stress testing it against your own expectations. Start by weighing the 2 key rewards and 2 important warning signs
Looking for more investment ideas beyond Celsius Holdings?
Do not stop your research with Celsius Holdings. Fresh opportunities often show up first in focused stock lists built around quality, value and resilience.
- Target potential upside by scanning a curated set of companies that appear mispriced on cash flows and fundamentals through the 31 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses in the 7 dividend fortresses that pair higher yields with disciplined payout histories and balance sheets.
- Protect your downside by zeroing in on companies in the 31 resilient stocks with low risk scores that show relatively sturdier finances and more stable price movements when markets become volatile.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com