


Buyback Expansion Could Be A Game Changer For Shimizu Stock (TSE:1803)
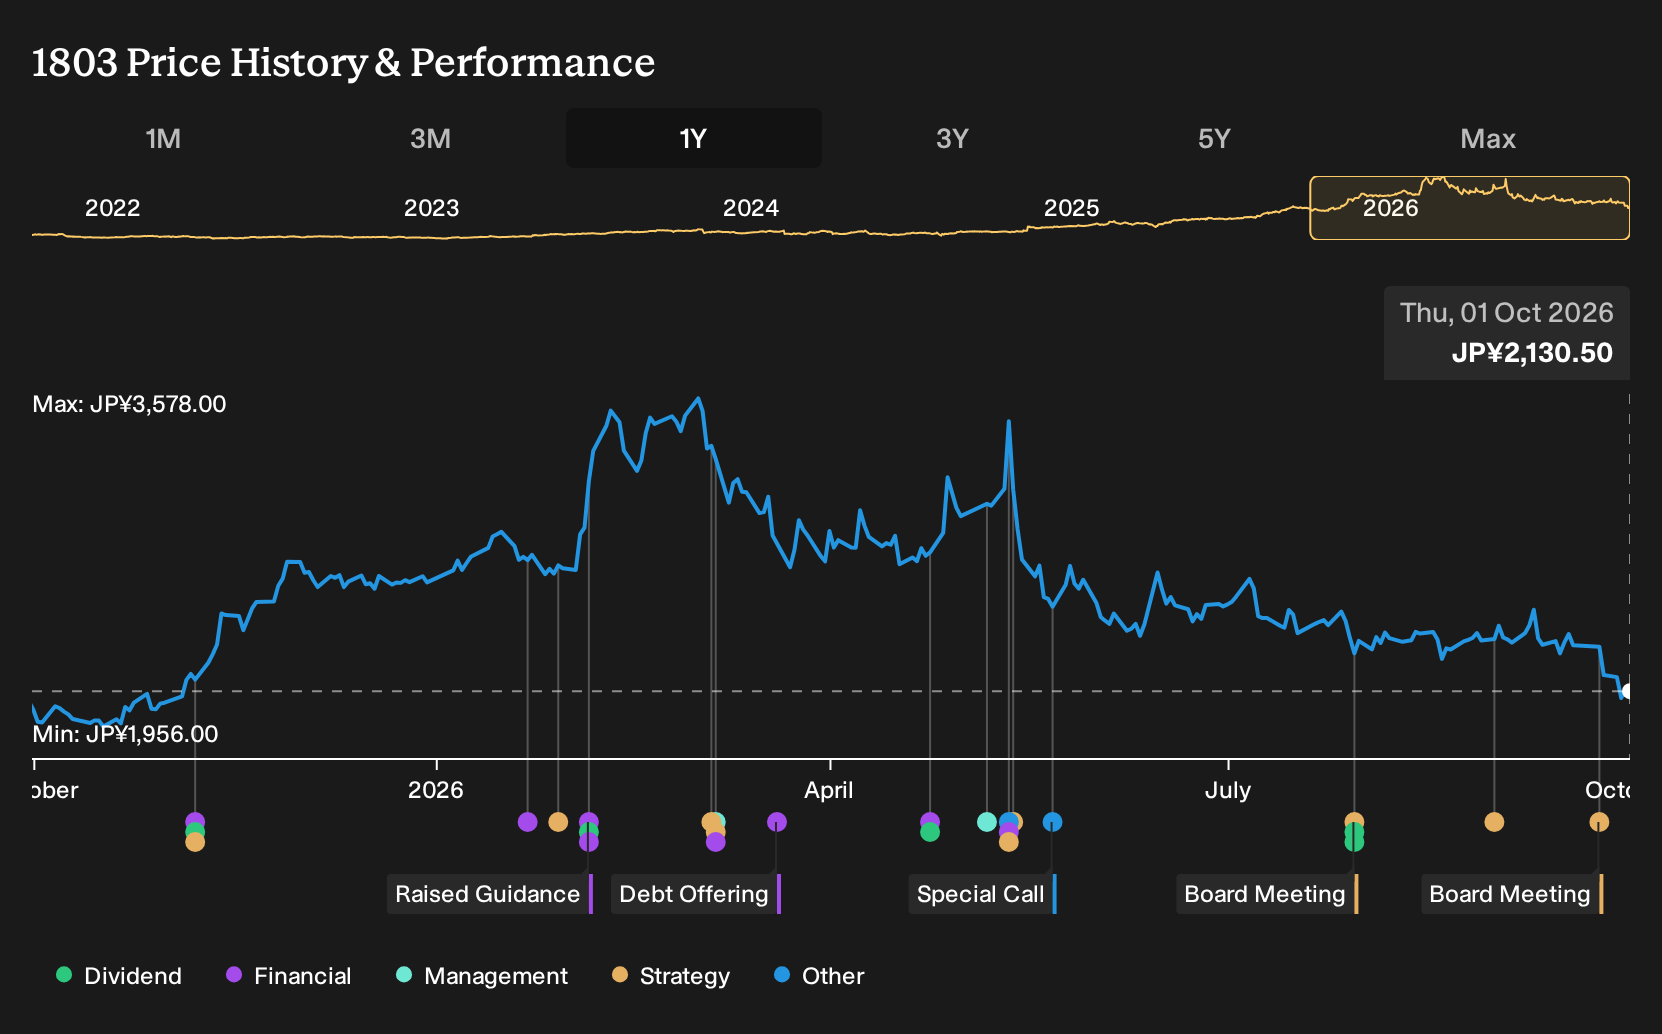
- Shimizu Corporation held a board meeting on 24 September 2026 to review a potential expansion of its share buyback limit, consider issuing zero coupon convertible bonds maturing in 2031 and 2033, and assess buybacks using the ToSTNeT-3 off auction repurchase framework.
- The combination of larger potential buybacks and new zero coupon convertible bonds points to an active rethink of Shimizu’s capital structure and future funding mix. This can influence how cash flows are allocated between investment in projects and returning funds to shareholders.
- We will now look at how Shimizu’s investment narrative could shift if larger buybacks reshape the balance between leverage and equity.
Compare Shimizu's capital return playbook with other companies actively reshaping their balance sheets using buybacks and fresh funding by scanning our hand picked list of solid balance sheet and fundamentals (23 results).
What Is Shimizu's Investment Narrative?
To own Shimizu, you need to believe this is a construction and engineering platform that can turn a deep project pipeline into consistent cash generation, even as earnings forecasts point to a 5.6% annual decline over the next three years. The business covers buildings, civil infrastructure, real estate and energy projects, which are all capital heavy and sensitive to execution quality and pricing discipline. Recent earnings growth of 128.5% and higher net margins at 8.1% versus 3.8% last year look strong, although a large ¥81.5b one off gain complicates the picture.
The September board meeting matters because it links that operating story to the balance sheet. Bigger buyback capacity and zero coupon convertible bonds would shift how Shimizu funds its project load and returns cash, in a context where the share price is down 21.4% year to date and trades on an 8.5x P/E. That can sharpen near term catalysts around capital returns, dividend sustainability at 3.59% and how much financial flexibility management reserves for slower forecast growth.
Yet before treating this capital return pivot as an uncomplicated plus, there is one structural pressure that still hangs over the equity story…
There's only one way to know the right time to buy, sell or hold Shimizu. Head to Simply Wall St's company report for the latest analysis of Shimizu's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community sit far apart, from about ¥2,236 up to roughly ¥60,795,194 per share. This shows how far opinions on Shimizu can spread. These views were formed before the September board meeting on new buybacks and zero coupon convertibles, so your own take may shift once that funding mix is clear.
Explore another Shimizu fair value estimate, including one that suggests as much as 2835497% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Shimizu research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Shimizu. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Shimizu's overall financial health at a glance.
Looking For More Shimizu-Style Investment Ideas?
If Shimizu has you thinking about balance sheets, cash generation and how capital gets recycled back to shareholders, it can help to scan a wider field of opportunities using the Simply Wall St Screener.
- For investors who want quality cash flows at a reduced entry price, consider scanning our hand picked 18 high quality undervalued stocks that combine fundamentals with attractive valuations.
- If resilience matters most to you, focus on businesses screened for financial strength by reviewing the curated 21 resilient stocks with low risk scores that aim to keep downside risk contained.
- To widen the opportunity set beyond well known tickers, check out a hand picked 76 high quality undiscovered gems that pair strong financial profiles with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com