


How Claims Fraud Tool Integration Will Impact Verisk Analytics Stock
- Truepic recently announced that its image and video authentication tools are now embedded in Verisk Analytics’ ClaimSearch platform. This allows insurers to request verified visual evidence after a fraud alert and run more than 50 fraud checks within existing claims workflows.
- This tighter link between fraud alerts and authenticated media supports Verisk Analytics’ push to deepen its role in claims decisioning, potentially improving client productivity and freeing specialist teams to focus on complex investigations.
- We will look at how Verisk Analytics’ investment narrative intersects with this new fraud focused ClaimSearch integration and evolving earnings expectations.
Scan for other insurance and data analytics players quietly tightening fraud controls and claims efficiency with the curated 31 resilient stocks with low risk scores that share a focus on resilience and disciplined risk management.
Verisk Analytics Investment Narrative Recap
To own Verisk Analytics, you need to believe insurers keep leaning on third party data, AI tools and workflow automation to squeeze more value from every premium dollar. The Truepic integration fits neatly into that story by tightening fraud controls inside existing claims systems, although the move looks incremental rather than a game changer for near term revenue or earnings.
The key near term swing factor remains how well Verisk converts AI driven products and Core Lines Reimagined content into steadier subscription growth while managing a high debt load. The biggest risk is a pullback in insurer tech budgets or weaker transaction volumes that would pressure margins just as investors look for cleaner execution.
The Truepic tie in looks most relevant when viewed alongside the appointment of Greg Alling as president of casualty solutions. That casualty unit is central to claims decisioning, compliance and automation, so leadership continuity there matters for how effectively tools like ClaimSearch, XactAI and Premium Audit AI are rolled out to frontline adjusters.
If Alling can sharpen product focus around fraud detection and workers’ compensation workflows, the casualty business could reinforce Verisk Analytics’ subscription and transaction catalysts that analysts already highlight, while also exposing operational risk. Any misstep in integrating new tools, or slower adoption by claims teams, would blunt the benefits investors hope to see from this cluster of product upgrades.
Verisk Analytics' current analyst narrative points to revenues of US$3.8b and earnings of US$1.3b by 2029, built on an assumed 6.6% yearly revenue growth rate and an earnings increase of about US$414.5m from US$885.5m today.
Uncover why Verisk Analytics' fair value indicates a 40% potential upside to its current price, which could narrow quickly.
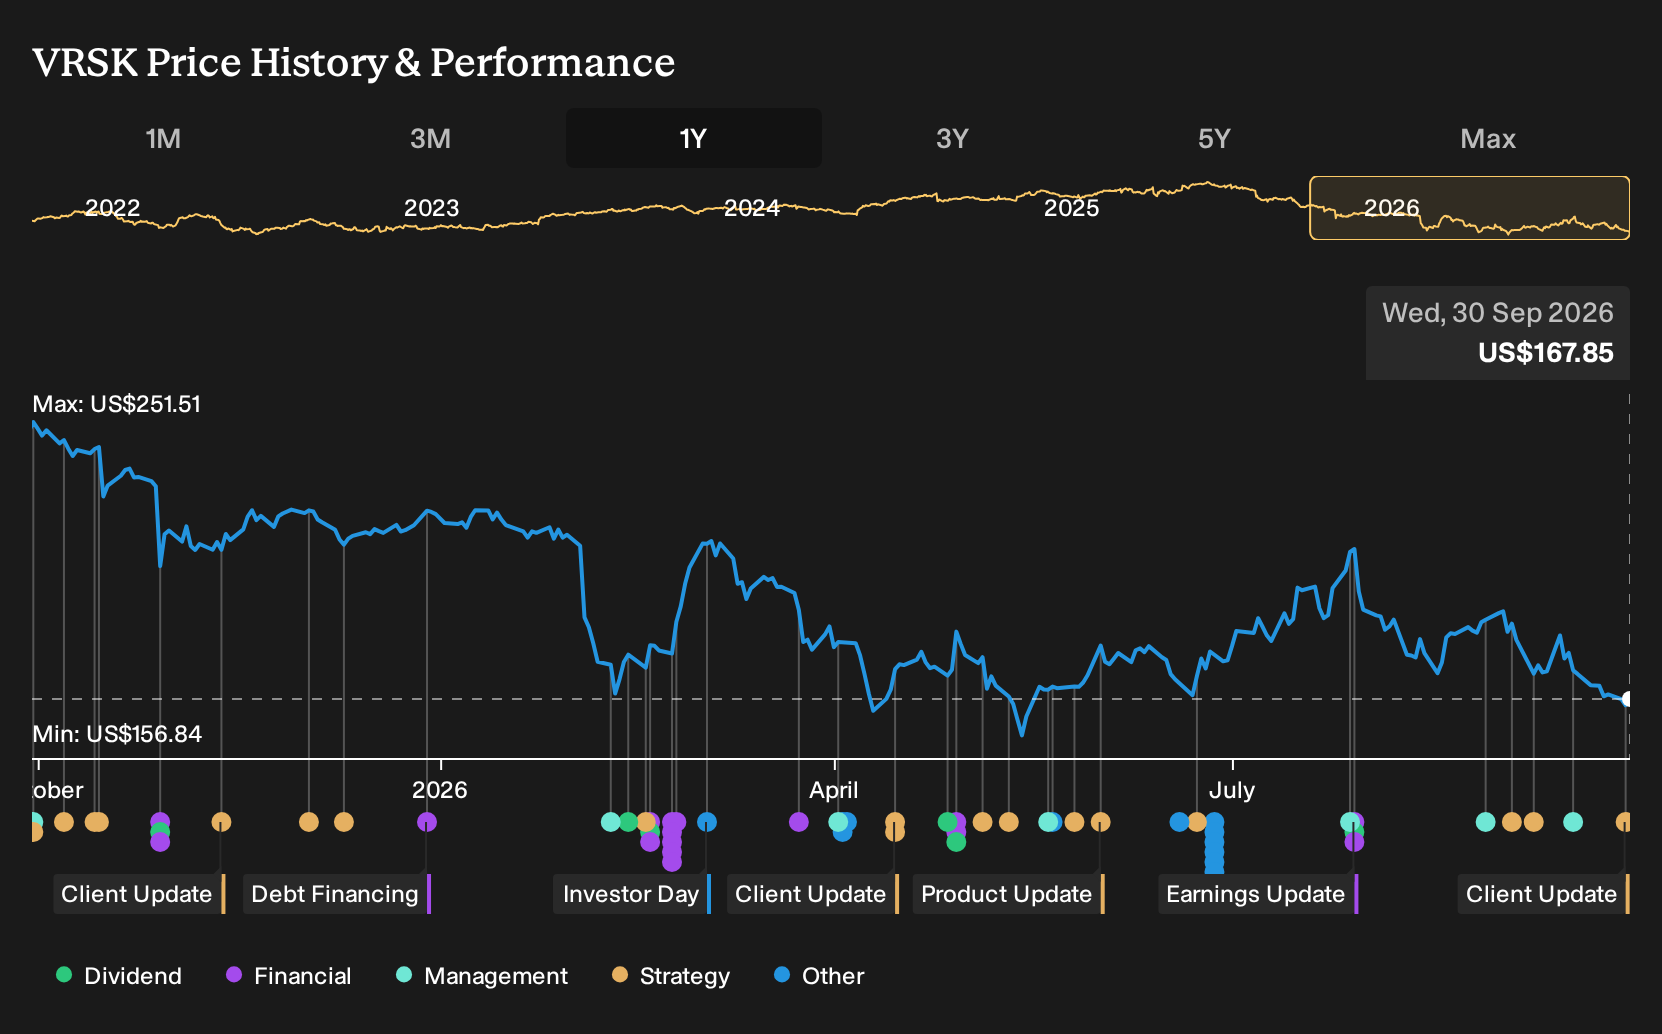
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community span roughly US$76.85 to US$291.30, so retail opinions on Verisk Analytics are already very far apart. When you set that against both the new Truepic integration and ongoing AI rollouts, plus the risk of tighter insurer tech budgets, you get a wide field of possible outcomes that you should compare by exploring several contrasting viewpoints.
Explore 4 other Verisk Analytics fair value estimates, including one that suggests as much as 54% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Verisk Analytics research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Verisk Analytics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Verisk Analytics' overall financial health at a glance.
Looking for more investment ideas beyond Verisk Analytics?
Once you have a view on Verisk Analytics, it can help to cross check that thesis against other businesses with different risk profiles and cash flow patterns using the Simply Wall St Screener.
- If capital preservation is high on your list, focus on resilient balance sheets and disciplined fundamentals using the list of solid balance sheet and fundamentals (25 results).
- For investors hunting for potential mispricing, scan through the 31 high quality undervalued stocks to see which companies currently screen as high quality yet priced cautiously by the market.
- Income focused portfolios can benefit from a shortlist of higher yielding ideas, starting with the 7 dividend fortresses that filters for payouts above 5% with an eye on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com