


Zee Fell 33% In A Year With Sales Rising And The Case Still Split
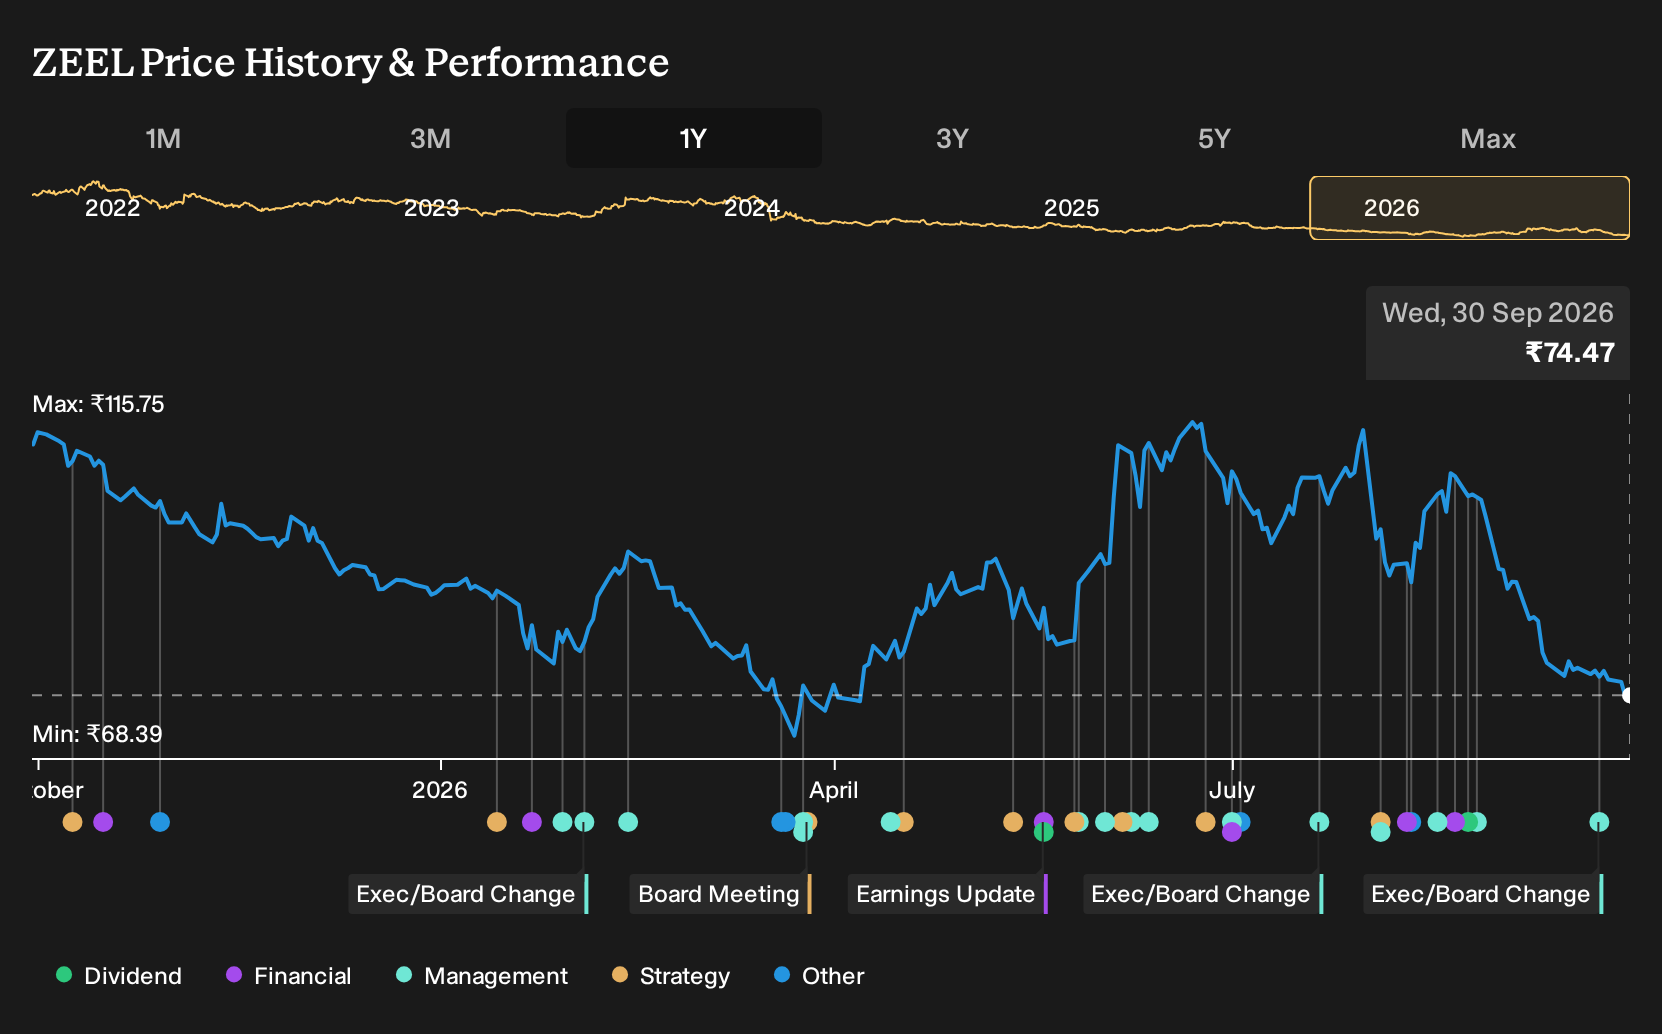
If you backed Zee Entertainment Enterprises for its digital pivot and regional content story, the past year has been bruising. Holding Zee Entertainment Enterprises over the past year would have meant a 33.2% loss, including dividends. If you had made that call on 30 September 2025, you would have been leaning on upbeat ZEE5 growth assumptions, margin improvement forecasts and expectations for industry consolidation. Which of those specific forecasts failed to allow for what actually unfolded in Zee’s earnings mix?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Zee Entertainment Enterprises has already moved. See which of 191 high quality undervalued stocks still trade below our estimates.
The Two Zee Entertainment Stories Investors Had To Choose Between
The shares cost ₹112 at the start of the period, and Zee Entertainment Enterprises sat between two sharply different stories about its future.
On the bullish side, the Fair Value was put at ₹148, based on expectations that ZEE5 would gain from language-focused subscription plans and micro-drama tie ups that were expected to lift digital revenue and support higher margins.
The bearish view put Fair Value at ₹98 and focused on structural pressure on linear TV, with digital migration and global streaming rivals seen as a risk to earnings and long term market share.
What The Results Changed For Zee Entertainment Enterprises
The clearest development for Zee Entertainment Enterprises was in the Q1 2027 earnings mix. Revenue reached ₹19,073m versus ₹18,248m a year earlier, which leaned toward the bullish digital and content growth story. Profit told a different tale. Net income fell from ₹1,437m to ₹763m and net margin slipped from 7.9% to 4.0%, which backed the cautious case. Overall, the evidence cut both ways.
The key lesson is simple. When a thesis leans on margin expansion, do not stop at headline sales. Track net income and net margin side by side each quarter to see whether growth is being bought with weaker profitability.
What Zee Entertainment’s Lower Price Now Asks You To Believe
Zee Entertainment Enterprises now trades at ₹74.47, well below where holders were a year ago. The selected Narrative’s Fair Value sits above the current price, framed around aggressive cost cuts, a digital reset and a push into sports and regional video.
The real question is simple. A buyer today would need to believe that Zee’s sports expansion and digital shift can turn cost reductions and new formats into sustained, higher margin earnings power.
"While analyst consensus expects gradual improvements in margins from cost discipline, the sharp 14% year-on-year reduction in operating costs and rapid digital losses reduction demonstrate that Zee is now positioned for a far steeper and faster expansion in EBITDA and net margins than modeled, setting the stage for significant earnings upside."
The price and this Narrative do not agree. → Uncover what this Narrative says Zee Entertainment Enterprises is actually worth
Another Way To Play Zee Entertainment’s Theme?
Zee Entertainment highlights how much now hinges on digital attention and video time. That naturally raises the question of where else that attention flows.
Streaming platforms need a steady supply of watchable clips, long shows and in-between formats. That demand supports businesses focused on search, video discovery and viewing behaviour.
One large player builds tools that connect viewers with content, then sells ads around those viewing moments. The same company also rents computing power that helps media clients train and run AI models.
If Zee Entertainment’s reset keeps you interested in digital viewing, that wider mix of search, cloud and video monetisation could be worth a closer look.
It is written up in full, assumptions and all. → Explore the Narrative that puts this company 26% above its price
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com