


Greatland Resources And 2 Australian Undervalued Stocks To Watch
Rising US Treasury yields have pushed up borrowing costs worldwide, which pressures highly leveraged businesses but often creates openings where steady cash flows are overlooked. Australian stocks with solid cash generation yet priced below fair value can look especially interesting when money is no longer cheap. This article highlights three such opportunities from our cash flow value screen, so you can see which ideas might deserve a closer look.
The three stocks covered next are only a sample from the wider idea, and the full screen surfaced 2 more companies with similarly strong cash flow stories that are not discussed in this article. To go straight to the complete list, analyze cash generation profiles, and identify which valuations look most compelling, head into the Undervalued Stocks Based On Cash Flows screener.
Greatland Resources (ASX:GGP)
Overview: Greatland Resources is a gold and copper miner whose Havieron project in Western Australia anchors its future cash flow potential.
Operations: The business currently generates about A$2.26b in revenue from the Telfer-Havieron segment, with sales spread across China, Australia and wider Asia.
Market Cap: A$7.04b
For investors focused on cash flow, Greatland Resources matters because Havieron is a single, high-impact project that can heavily influence future earnings, returns on capital and how long the current discount to estimated DCF value persists.
"The primary driver of Greatland’s future is the gold price. Transitioning from development to steady production is critical. Meeting capex targets, delivering forecast output, and controlling all-in sustaining costs will determine whether the company re-rates as a credible mid-tier producer rather than remaining a speculative play."
What happens when one unseen pressure tightens or releases will likely decide how much of that projected cash flow actually reaches margins.
When that pressure shifts, the full narrative for Greatland Resources shows how Greatland Resources’ cash flows could decouple from headline risk and what that might mean for long term value.
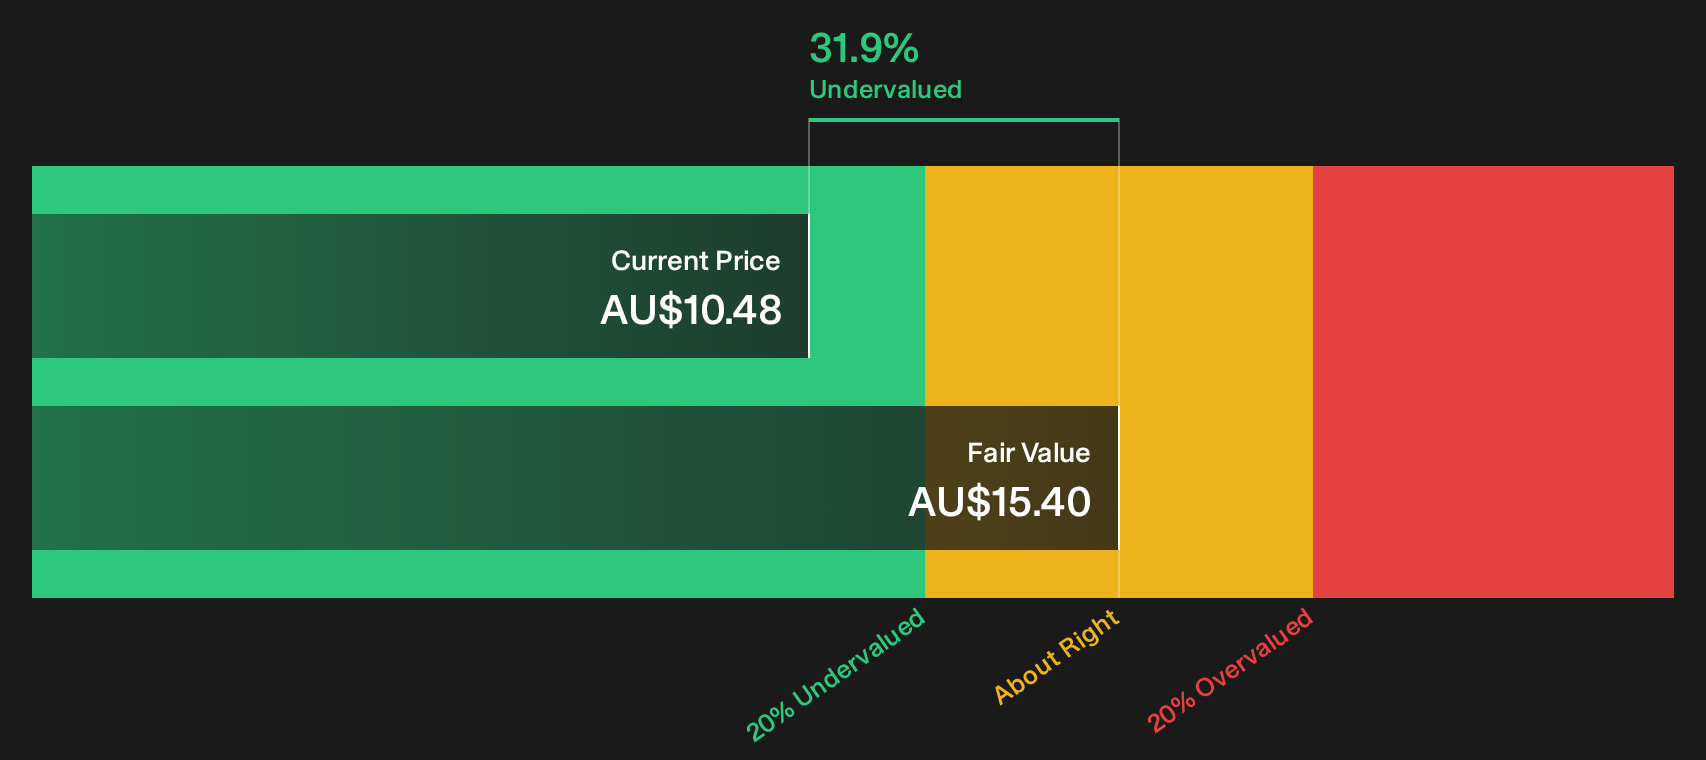
Woodside Energy Group (ASX:WDS)
Overview: Woodside Energy Group is a Perth based hydrocarbon producer that leans on LNG projects like Pluto and North West Shelf for major cash flows.
Operations: Woodside Energy Group generates about $7.29b from Australia, $4.62b from International operations, and $1.93b through its Marketing segment.
Market Cap: A$60.61b
Woodside Energy Group fits this cash flow focused screen because its established LNG hubs fund new projects while underpinning valuation models that rely on long term contracted volumes.
"The valuation also allows for Scarborough and Pluto Train 2 beginning production as planned, with the project 96% complete and targeting its first LNG cargo in the fourth quarter of 2026."
What happens if a single key assumption around future LNG pricing or project execution drifts even slightly away from current expectations?
If that shift is what worries you, the full narrative for Woodside Energy Group sets out how Woodside Energy Group’s cash flows could accelerate or stall under different LNG outcomes.
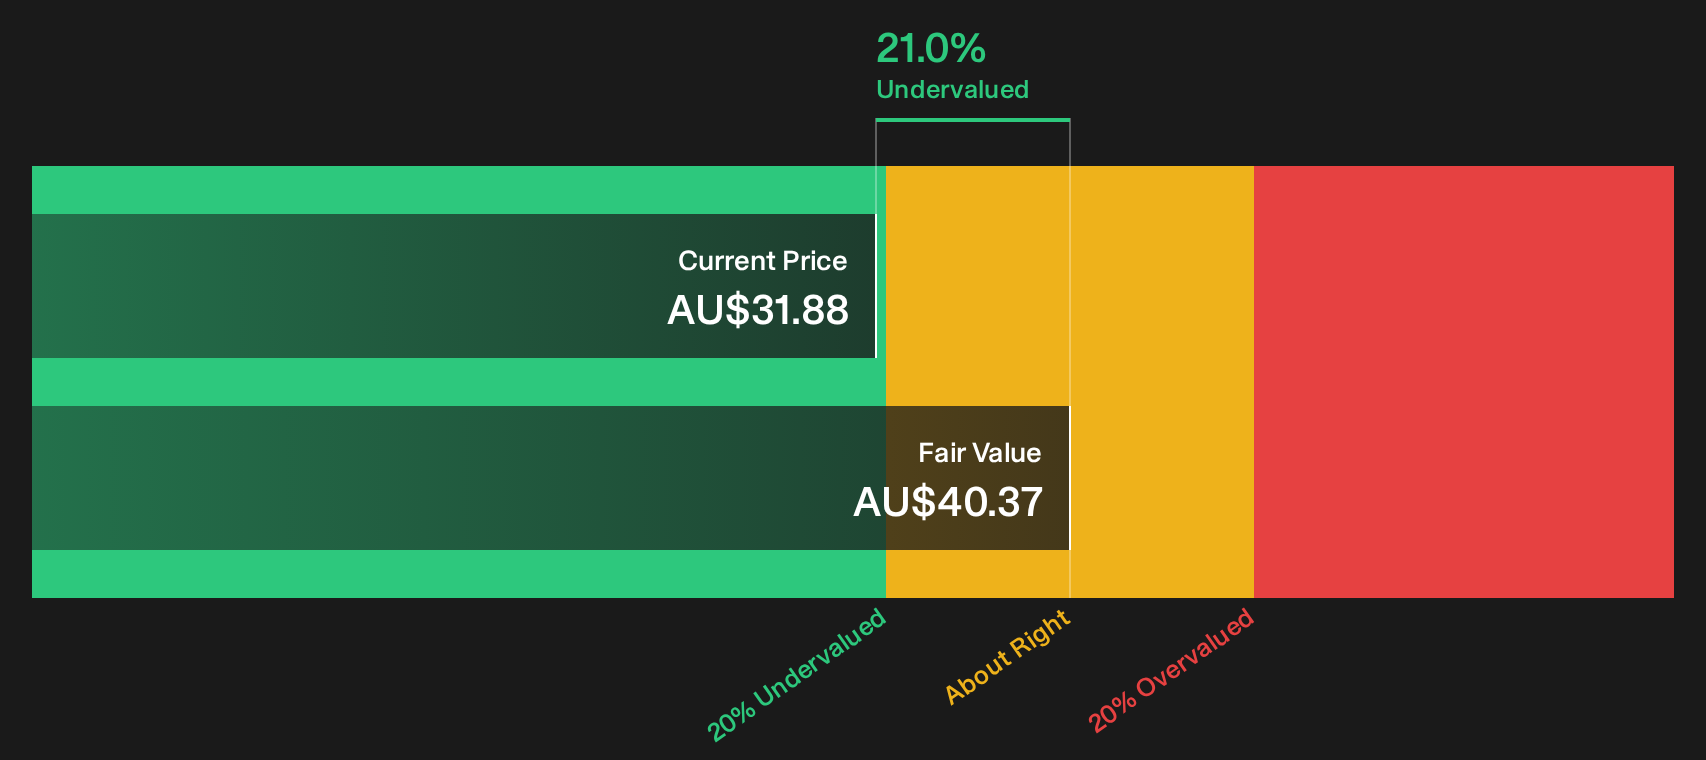
Westgold Resources (ASX:WGX)
Overview: Westgold Resources runs gold mines across the Murchison and Southern Goldfields in Western Australia, where operating projects underpin its cash flow story.
Operations: Westgold Resources generates about A$1.71b from Murchison and A$732 million from Southern Goldfields, all sourced within Australia.
Market Cap: A$5.02b
Westgold Resources matters for a cash flow focused screen because its producing Western Australian gold hubs are already generating earnings that support a discounted DCF valuation, with planned expansions aimed at extending that cash generation further.
"The integration of the Karora transaction has significantly increased Westgold's production scale and operational flexibility, positioning the company to respond to sustained global monetary instability and rising geopolitical tensions, with higher gold prices directly influencing revenue and earnings."
This raises the question of what could occur if a single key assumption about how efficiently new ore bodies translate into margins shifts away from today’s expectations.
If that question is front of mind, the full narrative for Westgold Resources shows how Westgold Resources’ enlarged footprint could turn efficiency swings into accelerating free cash flow potential.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first. Breakout stories gain momentum while they are still under the radar for now. Do not get caught watching prices dropping or flying. Consider acting based on your own research and judgment.
- Identify strong cash generators early and review the 5 high quality undervalued stocks while valuations still look reasonable and the stories are only just gaining momentum.
- Focus on potential long-term compounders and move through the list of solid balance sheet and fundamentals (12 results) before the crowd fully factors in their balance sheet resilience and steady fundamentals.
- Look for metals producers with meaningful operating leverage and review the 36 elite gold producer stocks while conditions still keep many of these miners under the radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com