


Should CHO K1 Media Launch Require Action From Thermo Fisher Scientific Stock Investors?
- Thermo Fisher Scientific recently launched the Gibco CHO-K1 Catalog Panel, a cGMP-ready suite of chemically defined, animal origin free basal and feed media in liquid and dry powder formats intended to support CHO-K1 cell growth, protein production, and smoother progression from process development through manufacturing.
- The product targets biologics and biosimilars developers that rely on CHO-K1 cell lines and offers multiple ready to use media and feed combinations that can shorten upstream process development while aligning with regulatory expectations for cGMP workflows.
- We will now look at how Thermo Fisher Scientific's investment narrative could be affected by this cGMP-ready CHO-K1 media portfolio launch.
Scan how Thermo Fisher Scientific fits into the broader bioprocessing theme by comparing it with a curated group of list of solid balance sheet and fundamentals (25 results) supporting long-term life sciences demand.
Thermo Fisher Scientific Investment Narrative Recap
To own Thermo Fisher Scientific, you need to believe that steady demand for pharma and biotech tools, services, and consumables can offset softer academic and government spending, China volatility, and tariff pressure. The nearest operational swing factor is how quickly biopharma capital spending and bioprocessing volumes translate into higher consumables pull through across its portfolio.
The new CHO K1 media launch nudges that near term catalyst in a supportive direction because it adds another cGMP ready consumable line tied directly to biologics workflows. The biggest risk does not change much. Prolonged funding uncertainty and policy pressure on instruments, combined with FX and China softness, could still cap margin progress.
Among recent updates, the Gibco CHO K1 Catalog Panel looks most relevant for the current story. It fits directly into Thermo Fisher Scientific’s push to build higher margin, recurring consumables around bioproduction, where customers value ready to use, regulatory aligned options that can run from small scale development through full manufacturing.
For you as an investor, the key question is execution. If management integrates this CHO K1 media range into broader bioprocessing accounts, it can support more stable consumable streams that matter when instruments face macro headwinds. If adoption is slower or biologics development cycles pause, that catalyst loses some punch while existing risks stay in focus.
Thermo Fisher Scientific's narrative projects US$54.8b revenue and US$10.0b earnings by 2029. This assumes 5.8% yearly revenue growth and an earnings increase of US$3.0b from US$7.0b today.
Uncover why Thermo Fisher Scientific's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
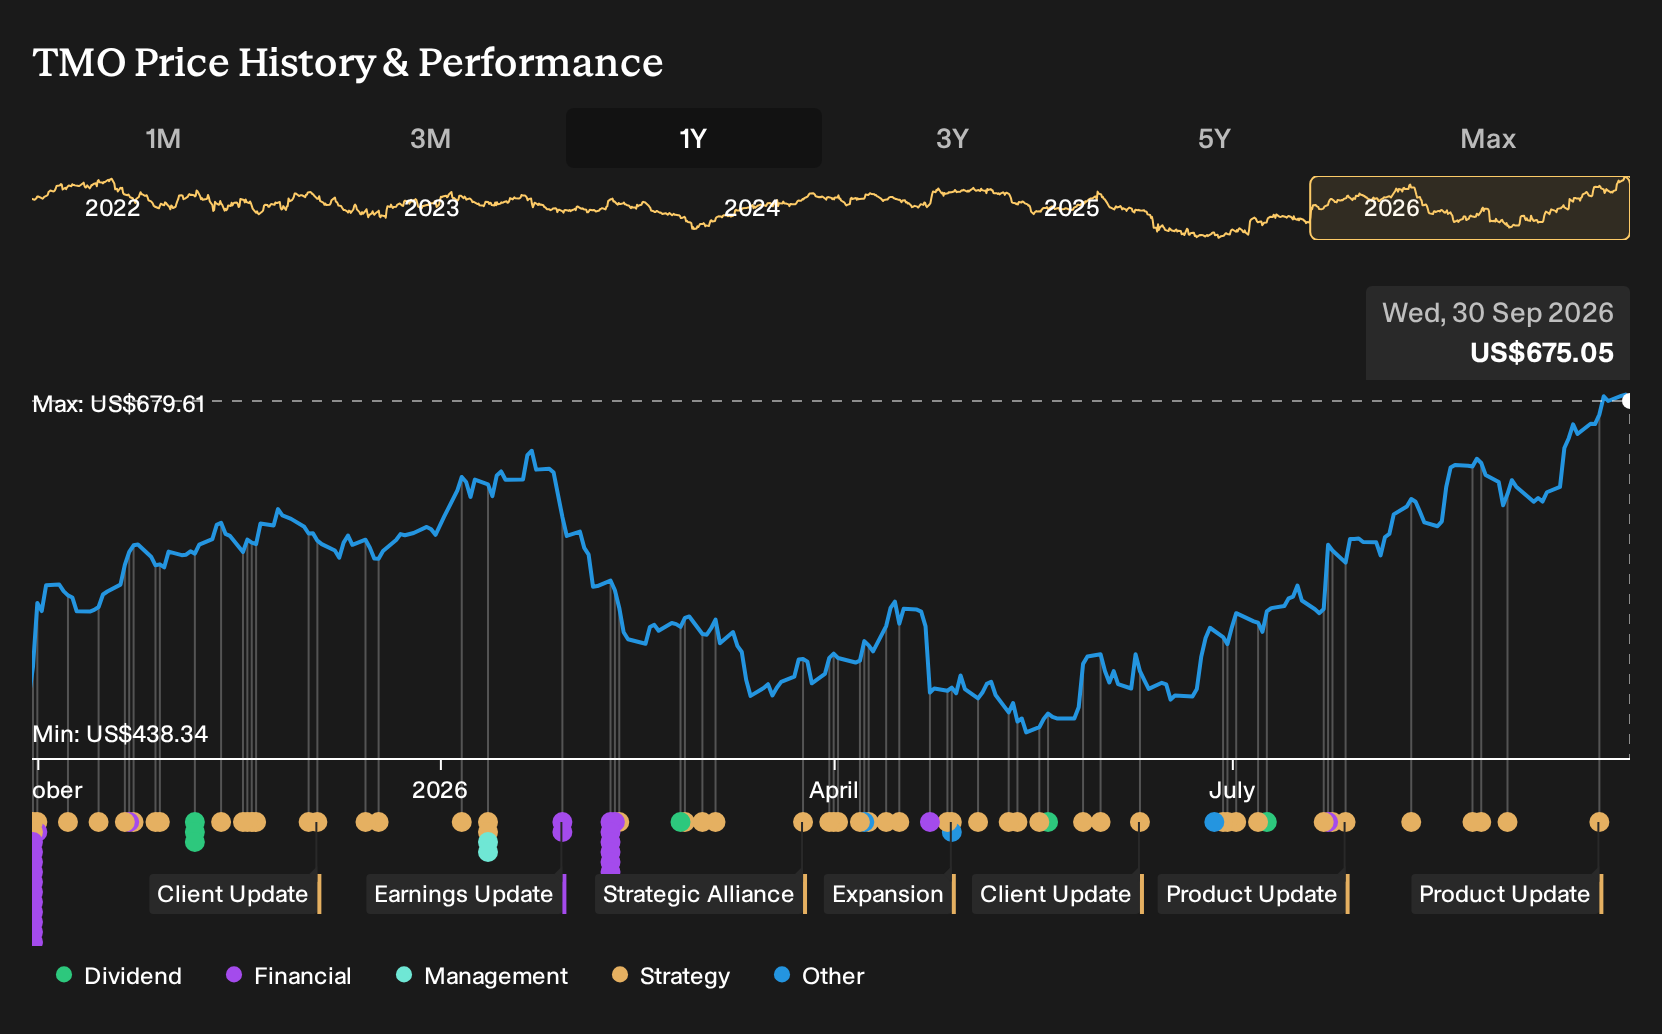
Exploring Other Perspectives
One alternate view focuses on geopolitical risk. From that perspective, Thermo Fisher Scientific faces challenges in offsetting trade friction and pricing pressure, with bearish analysts only penciling in about US$54.2b of revenue and US$8.7b of earnings by 2029. Those expectations sit below consensus, and this new CHO K1 media launch could eventually shift that debate.
Explore 3 other Thermo Fisher Scientific fair value estimates, including one that suggests up to 8% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Thermo Fisher Scientific research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Thermo Fisher Scientific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Thermo Fisher Scientific's overall financial health at a glance.
Looking For More Investment Ideas Beyond Thermo Fisher Scientific?
Thermo Fisher Scientific might sit at the center of your watchlist today, but you keep your edge by regularly scanning for other opportunities that match your risk profile and return goals. The Simply Wall St Screener helps you do that quickly by filtering for fundamentals that matter to you.
- If you want a focus on quality at a reasonable price, scan a curated set of opportunities through 31 high quality undervalued stocks that combine stronger fundamentals with more modest expectations baked into their prices.
- For investors who care most about resilience, start with 31 resilient stocks with low risk scores and narrow in on companies that score better on balance sheet strength and risk factors.
- If income is your priority, use 7 dividend fortresses to zero in on payers offering higher yields that are still backed by underlying business performance.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com