


3 European Growth Companies With High Insider Ownership
The European market has recently experienced a tug-of-war between optimism surrounding artificial intelligence and concerns about inflationary pressures, with the pan-European STOXX Europe 600 Index managing to edge up by 0.50% in local currency terms. In this climate of cautious economic growth and potential monetary policy tightening, identifying growth companies with high insider ownership can offer insights into stocks where those closest to the business have significant confidence in its future prospects.
Top 10 Growth Companies With High Insider Ownership In Europe
| Name | Insider Ownership | Earnings Growth |
| Pharma Mar (BME:PHM) | 12.1% | 39.8% |
| MilDef Group (OM:MILDEF) | 10.3% | 32.5% |
| Kuros Biosciences (SWX:KURN) | 25.9% | 60.3% |
| KebNi (OM:KEBNI B) | 16.3% | 103.8% |
| Gold Road International (OB:GOLDR) | 35.9% | 89.8% |
| Clavister Holding AB (publ.) (OM:CLAV) | 20.5% | 41.1% |
| CD Projekt Red (WSE:CDR) | 35.2% | 53.9% |
| Bonesupport Holding (OM:BONEX) | 10.6% | 32.2% |
| Bergen Carbon Solutions (OB:BCS) | 11.9% | 52% |
| 2G Energy (XTRA:2GB) | 13.4% | 30.2% |
Below we spotlight a couple of our favorites from our exclusive screener.
SpareBank 1 Nord-Norge (OB:NONG)
Simply Wall St Growth Rating: ★★★★☆☆
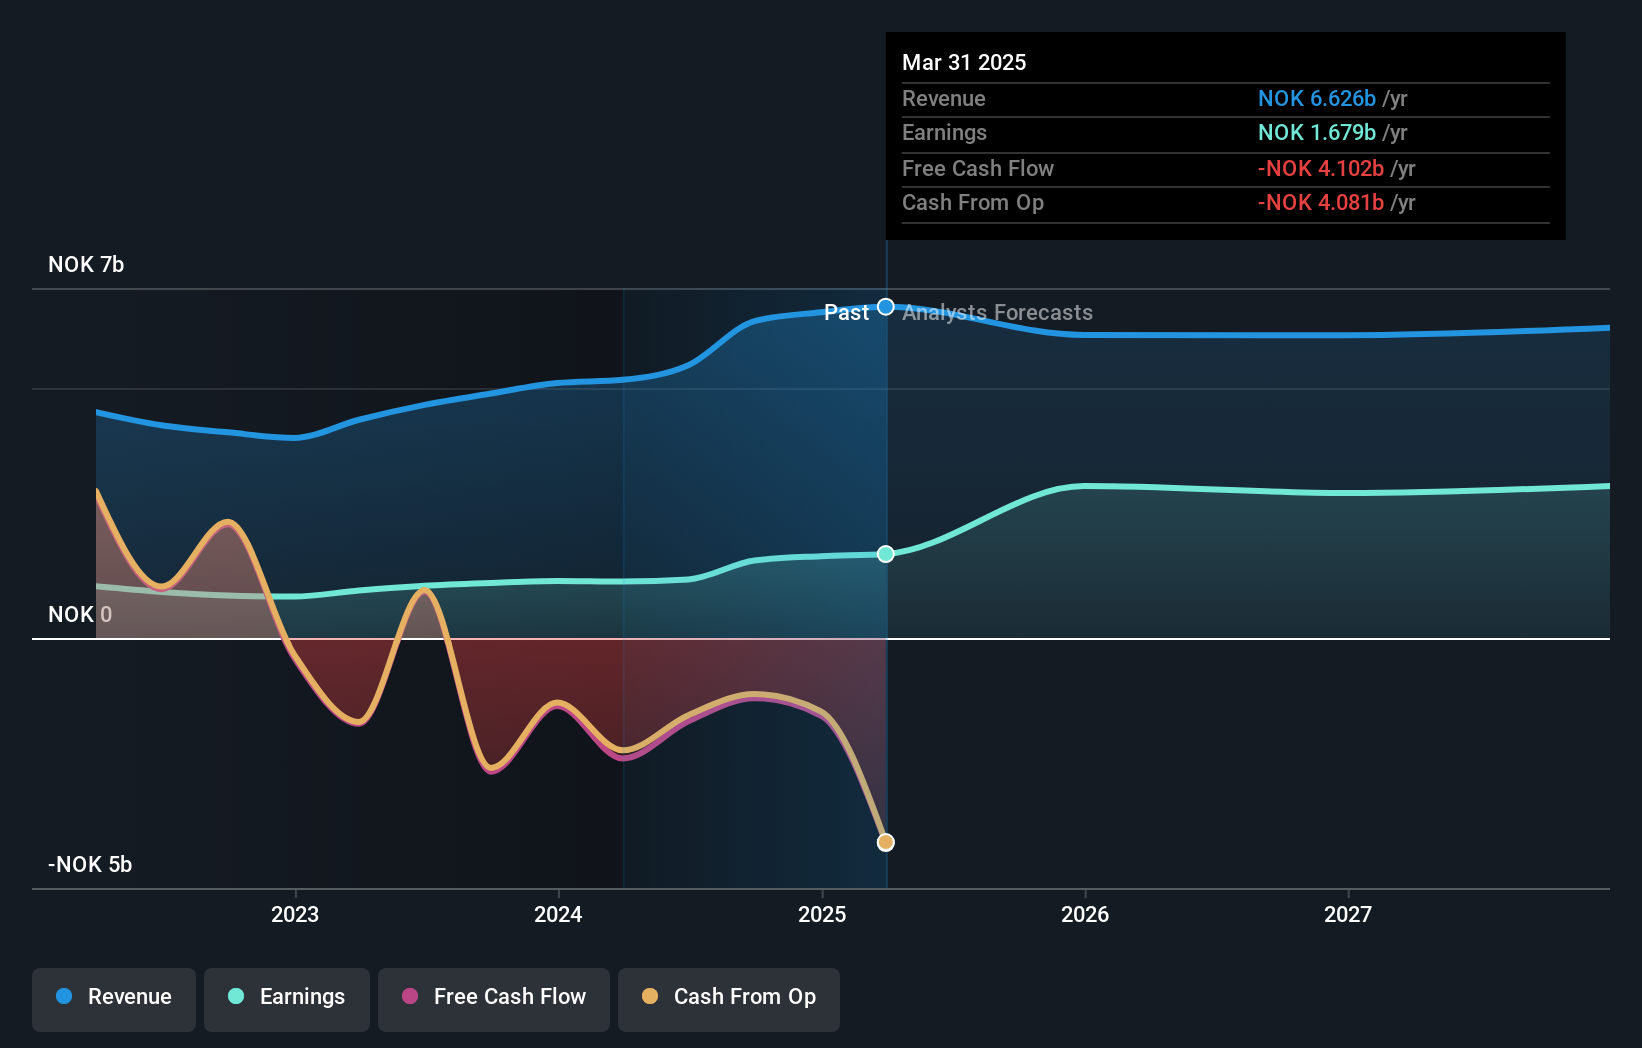
Overview: SpareBank 1 Nord-Norge offers banking services in Northern Norway and has a market cap of NOK17.54 billion.
Operations: The company's revenue segments include NOK2.49 billion from the Retail Market, NOK1.72 billion from Segment Adjustment, NOK259 million from Eiendoms-Megler 1 Nord-Norge, NOK387 million from Sparebank 1 Finans Nord-Norge, and NOK330 million from Sparebank 1 Regnskaps-Huset Nord-Norge.
Insider Ownership: 10.4%
Earnings Growth Forecast: 23.4% p.a.
SpareBank 1 Nord-Norge, with significant insider ownership, is poised for robust earnings growth of 23.42% annually over the next three years, outpacing the Norwegian market's average. Recent fixed-income offerings totaling nearly €10 million and SEK 500 million bolster its financial position. Despite a decrease in net income to NOK 834 million in Q2 2026 from NOK 938 million a year ago, it trades at a substantial discount to fair value while maintaining a reliable dividend yield of 4.87%.
- Delve into the full analysis future growth report here for a deeper understanding of SpareBank 1 Nord-Norge.
- The analysis detailed in our SpareBank 1 Nord-Norge valuation report hints at an deflated share price compared to its estimated value.
RaySearch Laboratories (OM:RAY B)
Simply Wall St Growth Rating: ★★★★★☆
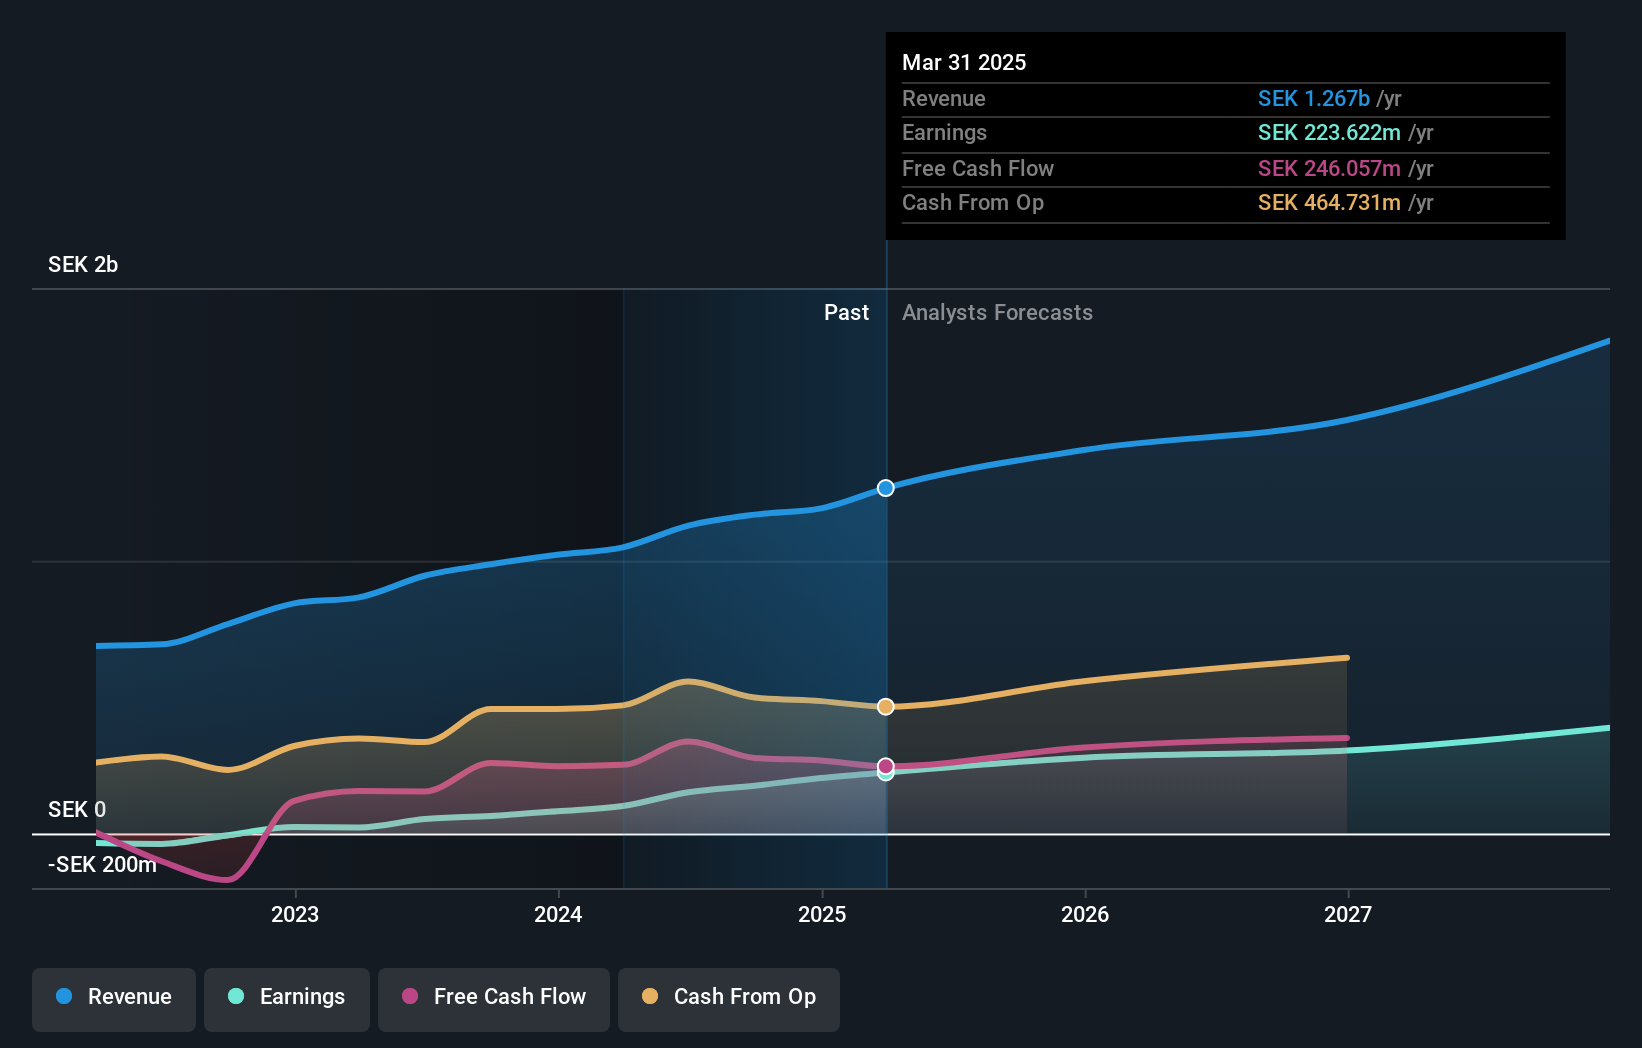
Overview: RaySearch Laboratories AB (publ) is a medical technology company that offers software solutions for cancer treatment globally, with a market cap of SEK 6.29 billion.
Operations: The company generates revenue from its healthcare software segment, amounting to SEK 1.27 billion.
Insider Ownership: 18.5%
Earnings Growth Forecast: 25.9% p.a.
RaySearch Laboratories, with significant insider ownership, is expected to achieve annual earnings growth of 25.9%, surpassing the Swedish market average. Despite recent sales and net income declines in Q2 2026, the company remains undervalued at 45.7% below fair value estimates. Strategic collaborations and product advancements, such as RayCare v2026 and partnerships with Accuray, enhance its oncology software offerings and support efficient workflows in radiation therapy clinics globally.
- Unlock comprehensive insights into our analysis of RaySearch Laboratories stock in this growth report.
- Insights from our recent valuation report point to the potential undervaluation of RaySearch Laboratories shares in the market.
Truecaller (OM:TRUE B)
Simply Wall St Growth Rating: ★★★★★☆
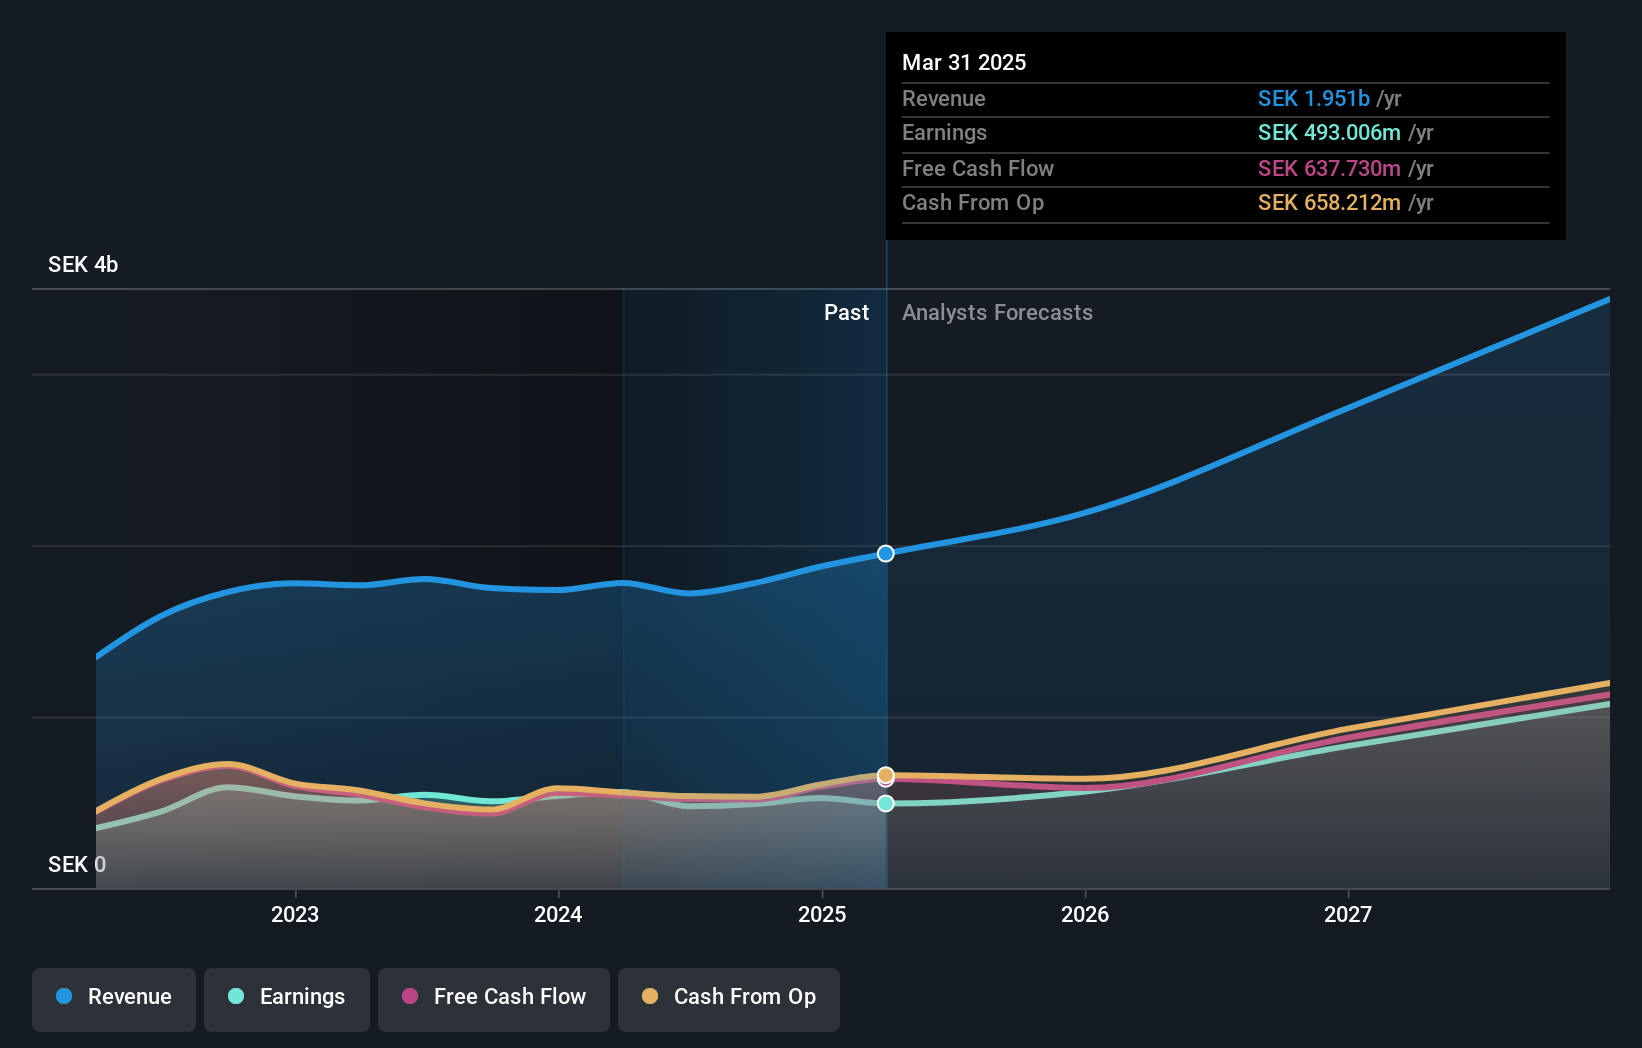
Overview: Truecaller AB (publ) develops and publishes mobile caller ID applications for individuals and businesses in India, the Middle East, Africa, and internationally with a market cap of approximately SEK7.03 billion.
Operations: The company's revenue primarily comes from its communications software segment, which generated approximately SEK1.71 billion.
Insider Ownership: 17.4%
Earnings Growth Forecast: 25.3% p.a.
Truecaller, with substantial insider ownership, is poised for significant earnings growth of 25.3% annually over the next three years, outpacing the Swedish market. Despite a decline in profit margins and net income in Q2 2026, it trades at 37.2% below its estimated fair value. Recent strategic moves include a partnership with LinkedIn to enhance professional identity features and the launch of Post-Call Actions to streamline business communications, reinforcing its growth trajectory.
- Click here to discover the nuances of Truecaller with our detailed analytical future growth report.
- According our valuation report, there's an indication that Truecaller's share price might be on the cheaper side.
Where To Now?
- Click through to start exploring the rest of the 211 Fast Growing European Companies With High Insider Ownership now.
- Contemplating Other Strategies? Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com