


Madison Square Garden Sports (MSGS) Could Be 16% Undervalued Following Split And Glaze Deal
Madison Square Garden Sports (MSGS) has become more event driven than usual after management announced a planned split into two independent public companies and unveiled a fresh commercial partnership with Glaze Teriyaki.
Recent trading reflects that shift in focus. Madison Square Garden Sports shares have pulled back 2.09% on a 1-day basis to US$405.21, although the 30-day share price return of 5.32% and year-to-date gain of 56.54% show that momentum has been building around the upcoming split and fresh commercial deals. The 76.34% 1-year total shareholder return and 132.75% 3-year total shareholder return highlight how strongly long-term holders have been rewarded through this period of restructuring and new partnerships.
Scan how other sports and entertainment plays are positioning around restructurings and commercial deals by reviewing our curated list of 19 high quality undiscovered gems that may still be off most investors' radar.
The split, the Glaze Teriyaki deal and a stock that has already run hard put Madison Square Garden Sports in a tight spot. Does the payoff still justify fresh risk at around US$405 a share?
Most Popular Narrative: 16% Undervalued
At a last close of $405.21 versus a narrative fair value of about $480.67, Madison Square Garden Sports screens as materially cheaper than that widely followed view, which leans heavily on the value of its Knicks and Rangers assets.
The upcoming ramp-up in high-value national media rights fees for the NBA (beginning in fiscal '26) will offset the recent step-down in local media rights, positioning MSG Sports for an overall increase in recurring media revenue and supporting both revenue growth and higher net margins over the next several years. Expanded international partnerships and marketing deals, such as with Abu Dhabi's Department of Culture and Tourism, signal rising global interest in the Knicks and Rangers franchises, enhancing sponsorship income and merchandise opportunities, which are likely to boost top-line revenue.
See why 6 investors see Madison Square Garden Sports as 16% undervalued.
Result: Fair Value of $480.67 (UNDERVALUED)
Still, the narrative around Madison Square Garden Sports can crack if reduced local media rights fees keep biting into a key revenue line or if rising player costs squeeze already thin net income.
Find out about the key risks to this Madison Square Garden Sports narrative.
Another View On Madison Square Garden Sports Valuation
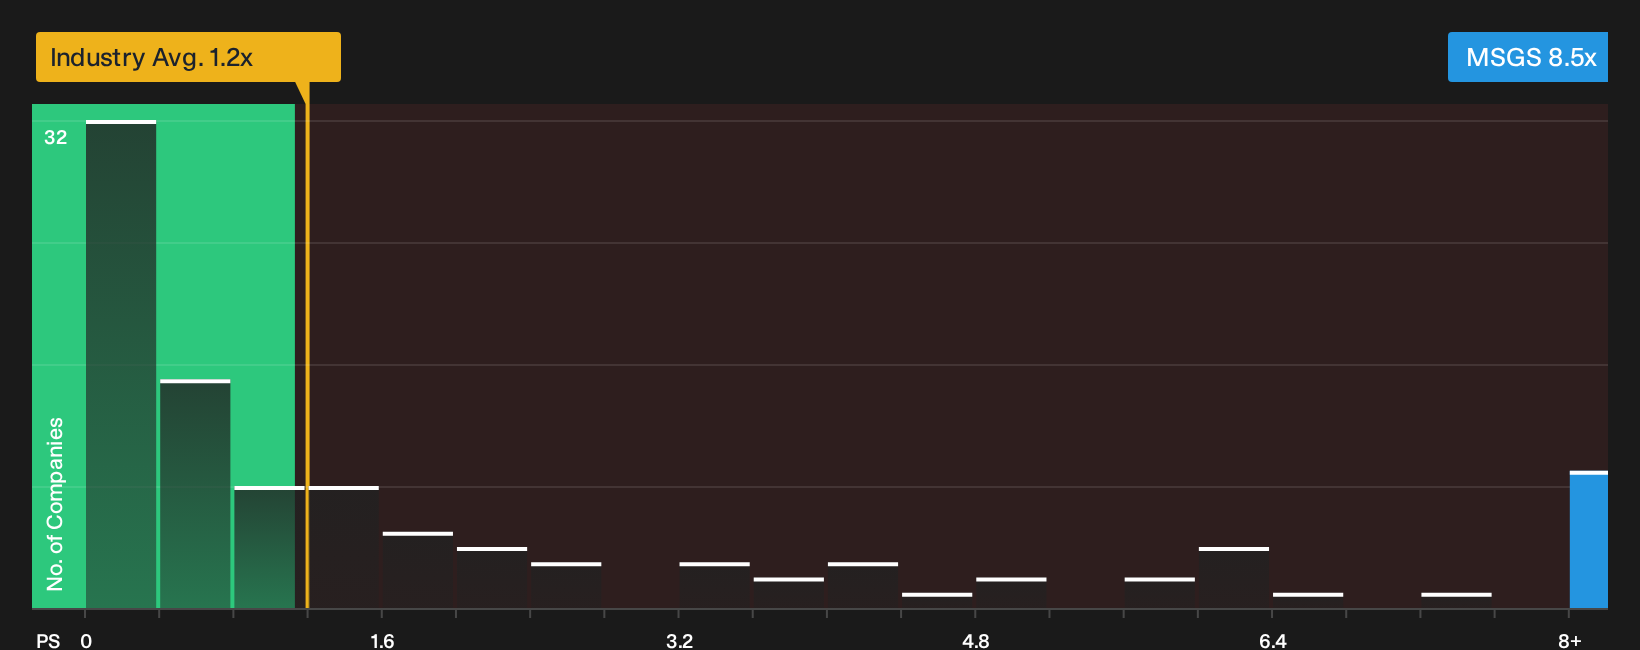
On the other side of that analyst fair value sits a much harsher read from simple sales multiples. Madison Square Garden Sports trades on a P/S of 8.5x against a US Entertainment average of 1.2x, peers at 2.4x and a fair ratio of 1.1x, which implies heavy valuation risk if sentiment cools.
That spread raises a basic question. Are investors comfortable paying several turns above sector norms for assets that still carry earnings volatility and restructuring risk, or is this where you start demanding a wider margin of safety?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Madison Square Garden Sports valuation and risk make this a decision point. Move quickly, review the data yourself, and weigh the 1 key reward and 3 important warning signs.
Looking for more Madison Square Garden Sports style ideas?
If Madison Square Garden Sports has your attention, do not stop here. Use powerful stock screeners to surface fresh ideas that fit your risk and return preferences.
- Target quality at a discount by scanning a curated pool of undervalued opportunities through the 32 high quality undervalued stocks.
- Prioritise durability by focusing on companies with resilient finances using the list of solid balance sheet and fundamentals (25 results).
- Seek stability with income by reviewing a focused set of higher yielding opportunities via the 7 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com