


Has Home Depot (HD) Fallen Far Enough for Its Cash Flow?
Home Depot shares have come under pressure over the past year, and that pullback is pushing investors to ask a simple question. Is the current price still in line with the cash that this retailer is expected to generate over time, or has the market moved ahead of the underlying flows?
- The stock has fallen 26.3% over the past year, which puts the focus squarely on whether the recent slide has brought the valuation closer to what its cash flows can support.
- Management has flagged a prolonged freeze in US housing turnover, which can weigh on large renovation projects and may influence how quickly Home Depot converts sales into free cash flow.
- If you'd rather focus on earnings, this one's for you. See why Home Depot's 20.0x P/E tells a different valuation story.
For investors, the debate is whether Home Depot's current share price is adequately backed by the cash flows implied by a Discounted Cash Flow (DCF) view of the business.
If you want to test the same cash flow question that hangs over Home Depot across a broader watchlist, scan through 33 high quality undervalued stocks.
Is Home Depot Fairly Priced on Cash Flow?
The Discounted Cash Flow (DCF) model here uses a 2 Stage Free Cash Flow to Equity approach to value Home Depot on the cash it could return to shareholders over time. Latest twelve month free cash flow sits at about $15.2b, and the projections build in a path where that cash generation is growing from this base rather than shrinking.
Those cash flow estimates assume Home Depot remains a high cash generator yet do not rely on extreme expansion, which fits a mature retailer with an established store network. Because Home Depot has already reached scale, the gap between the DCF estimate and the current share price of $284.49 comes out broadly in line rather than pointing to a clear bargain or an obvious excess. The warning from management about a prolonged freeze in US housing turnover helps explain why the market is not assigning a richer value to those projected cash flows. Find out what Home Depot could be worth using our Discounted Cash Flow (DCF) estimate.
The Home Depot Narrative: What Would Justify Today's Price?
Home Depot Narratives on Simply Wall St pick up where the cash flow puzzle leaves off by spelling out which assumptions on growth, profits and earnings would need to hold for the stock to be worth meaningfully more or less than today. Each Narrative on the Community page sets out Home Depot's implied fair value as a thesis that can be tracked over time, so you can see how the story holds up as new information arrives.
One of the top community narratives on Home Depot: 25% undervalued
Home Depot's deployment of AI powered tools such as Magic Apron and internal pricing engines is intended to deliver several billion dollars of productivity...
Discover why this Narrative puts Home Depot at 25% undervalued.
One more piece of the Home Depot puzzle that investors often overlook
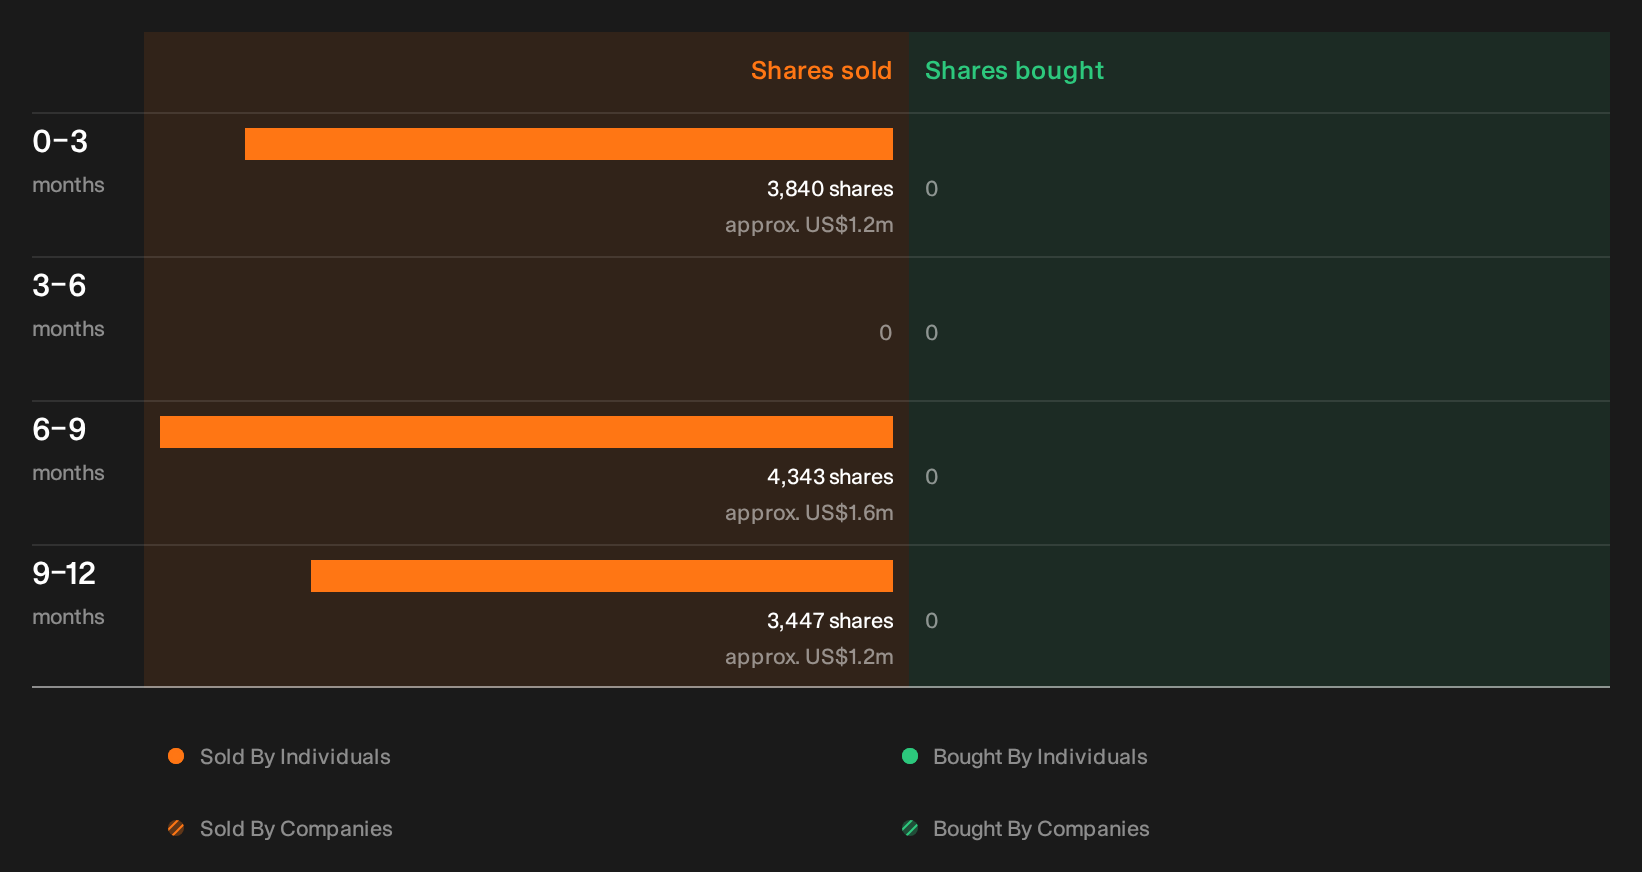
There is one area the numbers above do not touch. Recent insider share sales have been flagged by our checks, and the specific people, volumes and potential meaning are left for you to review. See the recent insider selling flagged for Home Depot.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com