


MP Materials (MP) Could Be 37% Undervalued As Magnet Milestones Draw Fresh Attention
MP Materials (MP) has been back in the spotlight after a mix of company milestones in rare earth magnet production and broader sector headlines pulled fresh attention to the stock’s mine-to-magnet build out.
Recent trading has been choppy for MP Materials, with the share price down about 14% year to date and the 1 year total shareholder return declining roughly 30%, even though the 3 year total shareholder return is still very large. Short term moves have swung around news on magnet shipments to General Motors, progress at the Fort Worth facility and sector wide spikes linked to the Greenland deal headlines, which have pulled more speculative money into rare earth equities before sentiment cooled again.
Spot opportunities beyond MP Materials by scanning a hand picked group of rare earth peers and adjacent miners in our 35 best rare earth metal stocks.For MP Materials, a 30% 1 year decline set against a very large 3 year gain leaves a straightforward choice. Are you looking at a still early mine to magnet rerating, or a story that has already delivered most of its upside potential?
Most Popular Narrative: 37% Undervalued
On the most followed view of MP Materials, a fair value of $75.28 sits well above the recent $47.29 close. This puts the whole rerating debate on how much of its mine to magnet plan investors think will actually translate into cash flows.
The company is expanding its vertically integrated processing and magnet manufacturing capacity with the "10X" plant and a modular recycling facility. Together with significant CapEx support from Apple and the DoD, this is expected to capture more value-added margins and potentially improve net profit and operating leverage as they ramp downstream operations.
Structural global shifts that prioritize domestic and allied supply chains for critical materials, underpinned by national security and electrification policies, have resulted in government funding, ownership stakes, and market protections for MP. These dynamics support U.S.-produced rare earths and may influence margins.
See why 197 investors see MP Materials as 37% undervalued.
Result: Fair Value of $75.28 (UNDERVALUED)
Still, the bullish MP Materials narrative can crack if expansion projects like the 10X plant encounter cost overruns or if key partners such as Apple or the DoD rethink orders.
Find out about the key risks to this MP Materials narrative.
Another View on MP Materials Valuation
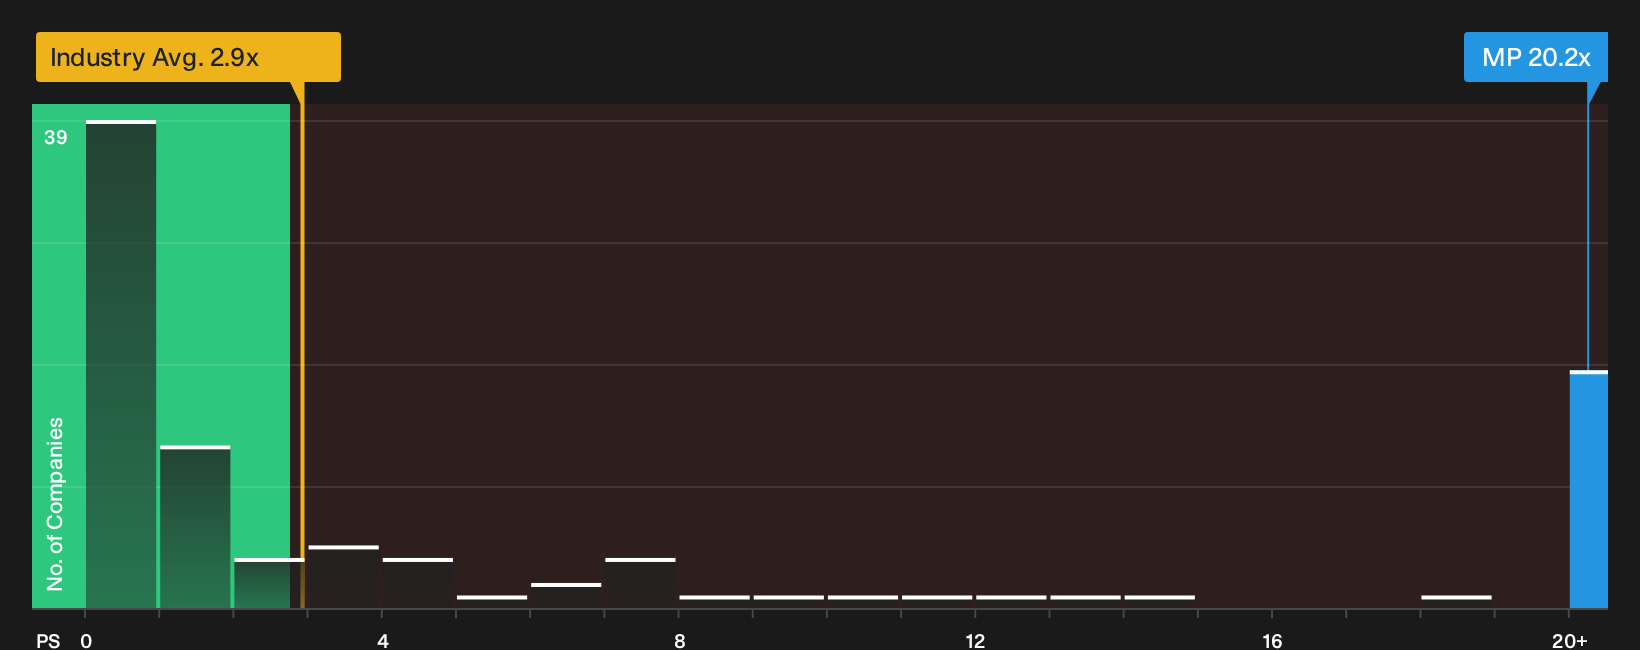
The bullish fair value of $75.28 for MP Materials leans heavily on future cash flows and optimistic analyst assumptions. A quick reality check comes from the current P/S ratio of 20.2x, which is far higher than both the US Metals and Mining industry at 2.9x and the fair ratio of 6.9x. That kind of gap raises a simple question: Is this a rare opportunity, or is too much future success already embedded in the price?
To see what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Feeling unsure whether the mood around MP Materials is too optimistic or too cautious right now is normal, so move quickly, pull up the full data set, and pressure test every assumption using the 3 key rewards.
Looking for more investment ideas beyond MP Materials?
You have seen how wide the debate is around MP Materials. Now broaden your opportunity set by lining up other potential candidates side by side.
- Target potential mispriced opportunities early by scanning a curated set of 18 high quality undiscovered gems that combine strong fundamentals with room for more attention.
- Focus on resilience first by filtering for companies in our 31 resilient stocks with low risk scores that score well on balance sheet strength and earnings stability.
- Zero in on value and quality together by reviewing our 32 high quality undervalued stocks, which highlights companies with solid cash flows and supportive financial profiles.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com