


How to Play LOW Stock as Lowe’s Launches Drone Delivery Test
Lowe’s Companies (LOW) is testing a new delivery method that could reshape the way customers receive last-minute home improvement supplies. Recently, the retailer launched a drone delivery pilot at its Matthews, North Carolina, store, making Lowe’s the first home improvement retailer in the U.S. to offer drone delivery. The service, operated in partnership with DoorDash (DASH) and Alphabet's (GOOG) (GOOGL) Wing Aviation subsidiary, allows eligible DIY and professional customers to receive select items in as little as 20 minutes.
The pilot initially covers more than 100 products, including hand tools, paint supplies, tape, and other household essentials, with Wing drones carrying orders of approximately 2.5 pounds per flight. While the program remains limited in scope, it adds another layer to Lowe’s growing technology and fulfillment strategy, alongside same-day delivery, curbside pickup, and its AI-powered Mylow tools.
The faster, technology-driven fulfillment could improve customer convenience and strengthen Lowe’s competitive position over time. So, is the stock a buy, sell, or hold now?
About Lowe’s Stock
Lowe’s Companies is one of the largest home improvement retailers in the U.S., serving both do-it-yourself customers and professional contractors through its extensive store network and digital platforms. Headquartered in Mooresville, North Carolina, the company continues to invest in technology and faster fulfillment to strengthen its customer proposition. Lowe’s boasts a market cap of $105.3 billion.
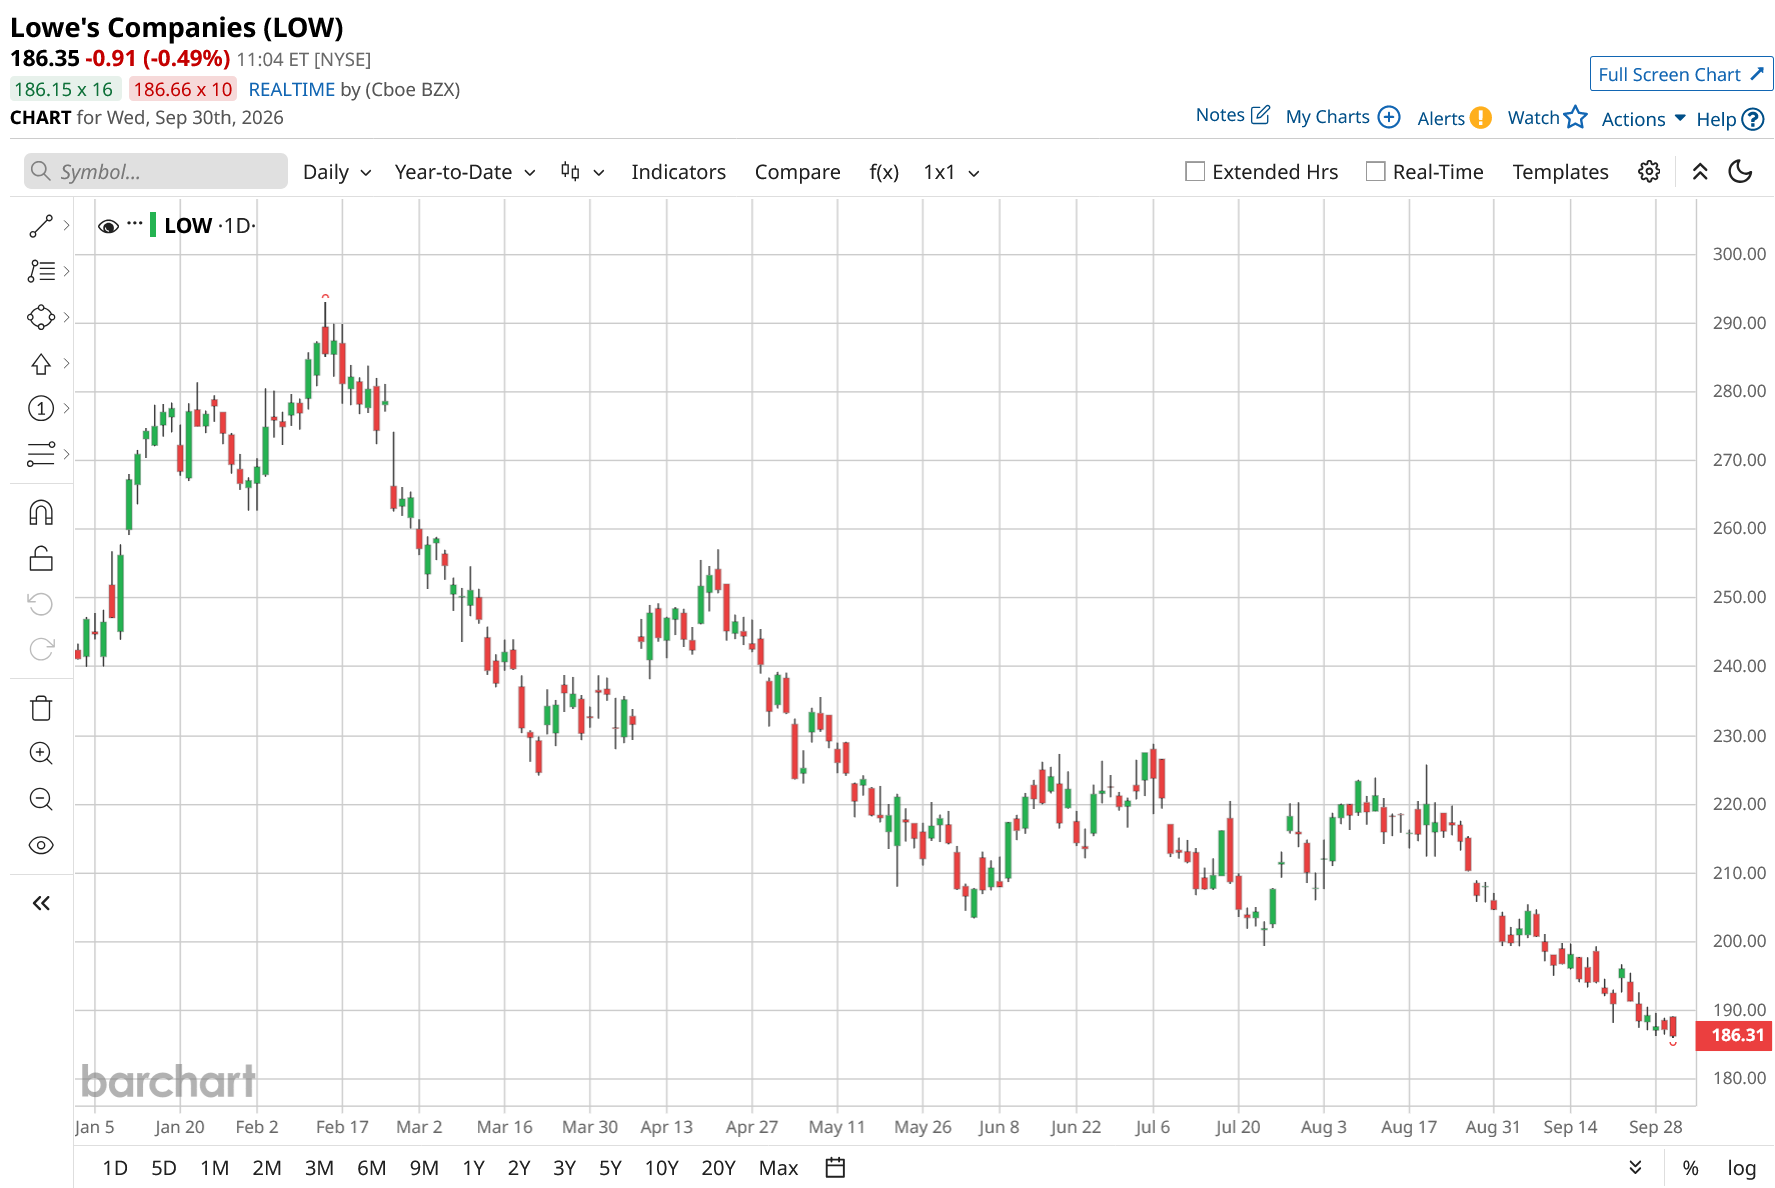
Lowe’s stock has come under significant pressure in 2026, reflecting a challenging backdrop for home-improvement spending and continued weakness in discretionary DIY demand. Shares are down 26% over the past 52 weeks and 22% year-to-date (YTD), while LOW stock has fallen 10% over the past month. The shares closed at $187.26 on Sept. 29, well below the 52-week high of $293.06 reached in February.
The weakness has come as Lowe’s contends with a softer consumer environment, particularly in discretionary DIY spending.
Against this backdrop, Lowe’s Sept. 24 announcement that it is testing drone delivery represents a technology and customer-convenience catalyst. However, the initial market reaction was muted as LOW shares fell 1.5% on Sept. 24, the day the drone-delivery announcement was made, and rose only slightly in the next session. Investors seem to remain focused on Lowe’s broader demand environment and outlook, making the pilot more of a potential longer-term fulfillment catalyst than an immediate stock-price driver.
The stock is trading at a modest premium compared to industry peers at 15.37 times forward earnings.
Soft Recent Quarterly Performance
Lowe’s reported its second-quarter fiscal 2026 (ended July 31) results on Aug. 19. Revenue increased 8.3% year-over-year (YoY) to $26 billion. Lowe’s comparable sales increased just 0.2% YoY in Q2 fiscal 2026, reflecting a still-cautious home-improvement spending environment. The modest gain came as a 2.3% increase in comparable average ticket was largely offset by a 2.1% decline in comparable customer transactions.
Lowe’s said persistent pressure on discretionary DIY spending, challenging weather conditions, elevated fuel prices, and broader economic uncertainty weighed on demand, with customers prioritizing repair, maintenance, and smaller projects.
Nevertheless, online sales were a notable bright spot, rising 15.7% YoY, while Pro and home-services sales also posted strong growth.
Profitability was more subdued. Gross profit came in at $8.6 billion compared to $8.1 billion a year ago. At the bottom line, adjusted EPS increased to $4.40 from $4.33.
Coming to its full fiscal year outlook, Lowe’s lowered and narrowed its guidance. It now expects sales of $92 billion, compared with the previous range of $92.0 billion to $94.0 billion, and flat comparable sales, versus its prior expectation of flat to 2% growth.
The company reduced its expected adjusted operating margin to 11.6% from 11.6%-11.8%. Its adjusted EPS guidance was reduced to approximately $12.25 from $12.25-$12.75. Lowe’s maintained its capital-expenditure outlook at up to $2.5 billion.
Analysts predict EPS to be around $12.26 for fiscal 2026, down marginally YoY, but surge by 6.4% annually to $13.04 in fiscal 2027.
What Do Analysts Expect for LOW Stock?
This month, Stifel has reiterated its “Hold” rating on LOW stock with a $220 price target, reflecting concerns about the near-term home-improvement demand environment.
However, Guggenheim reiterated its “Buy” rating on Lowe’s, while maintaining its $275 price target.
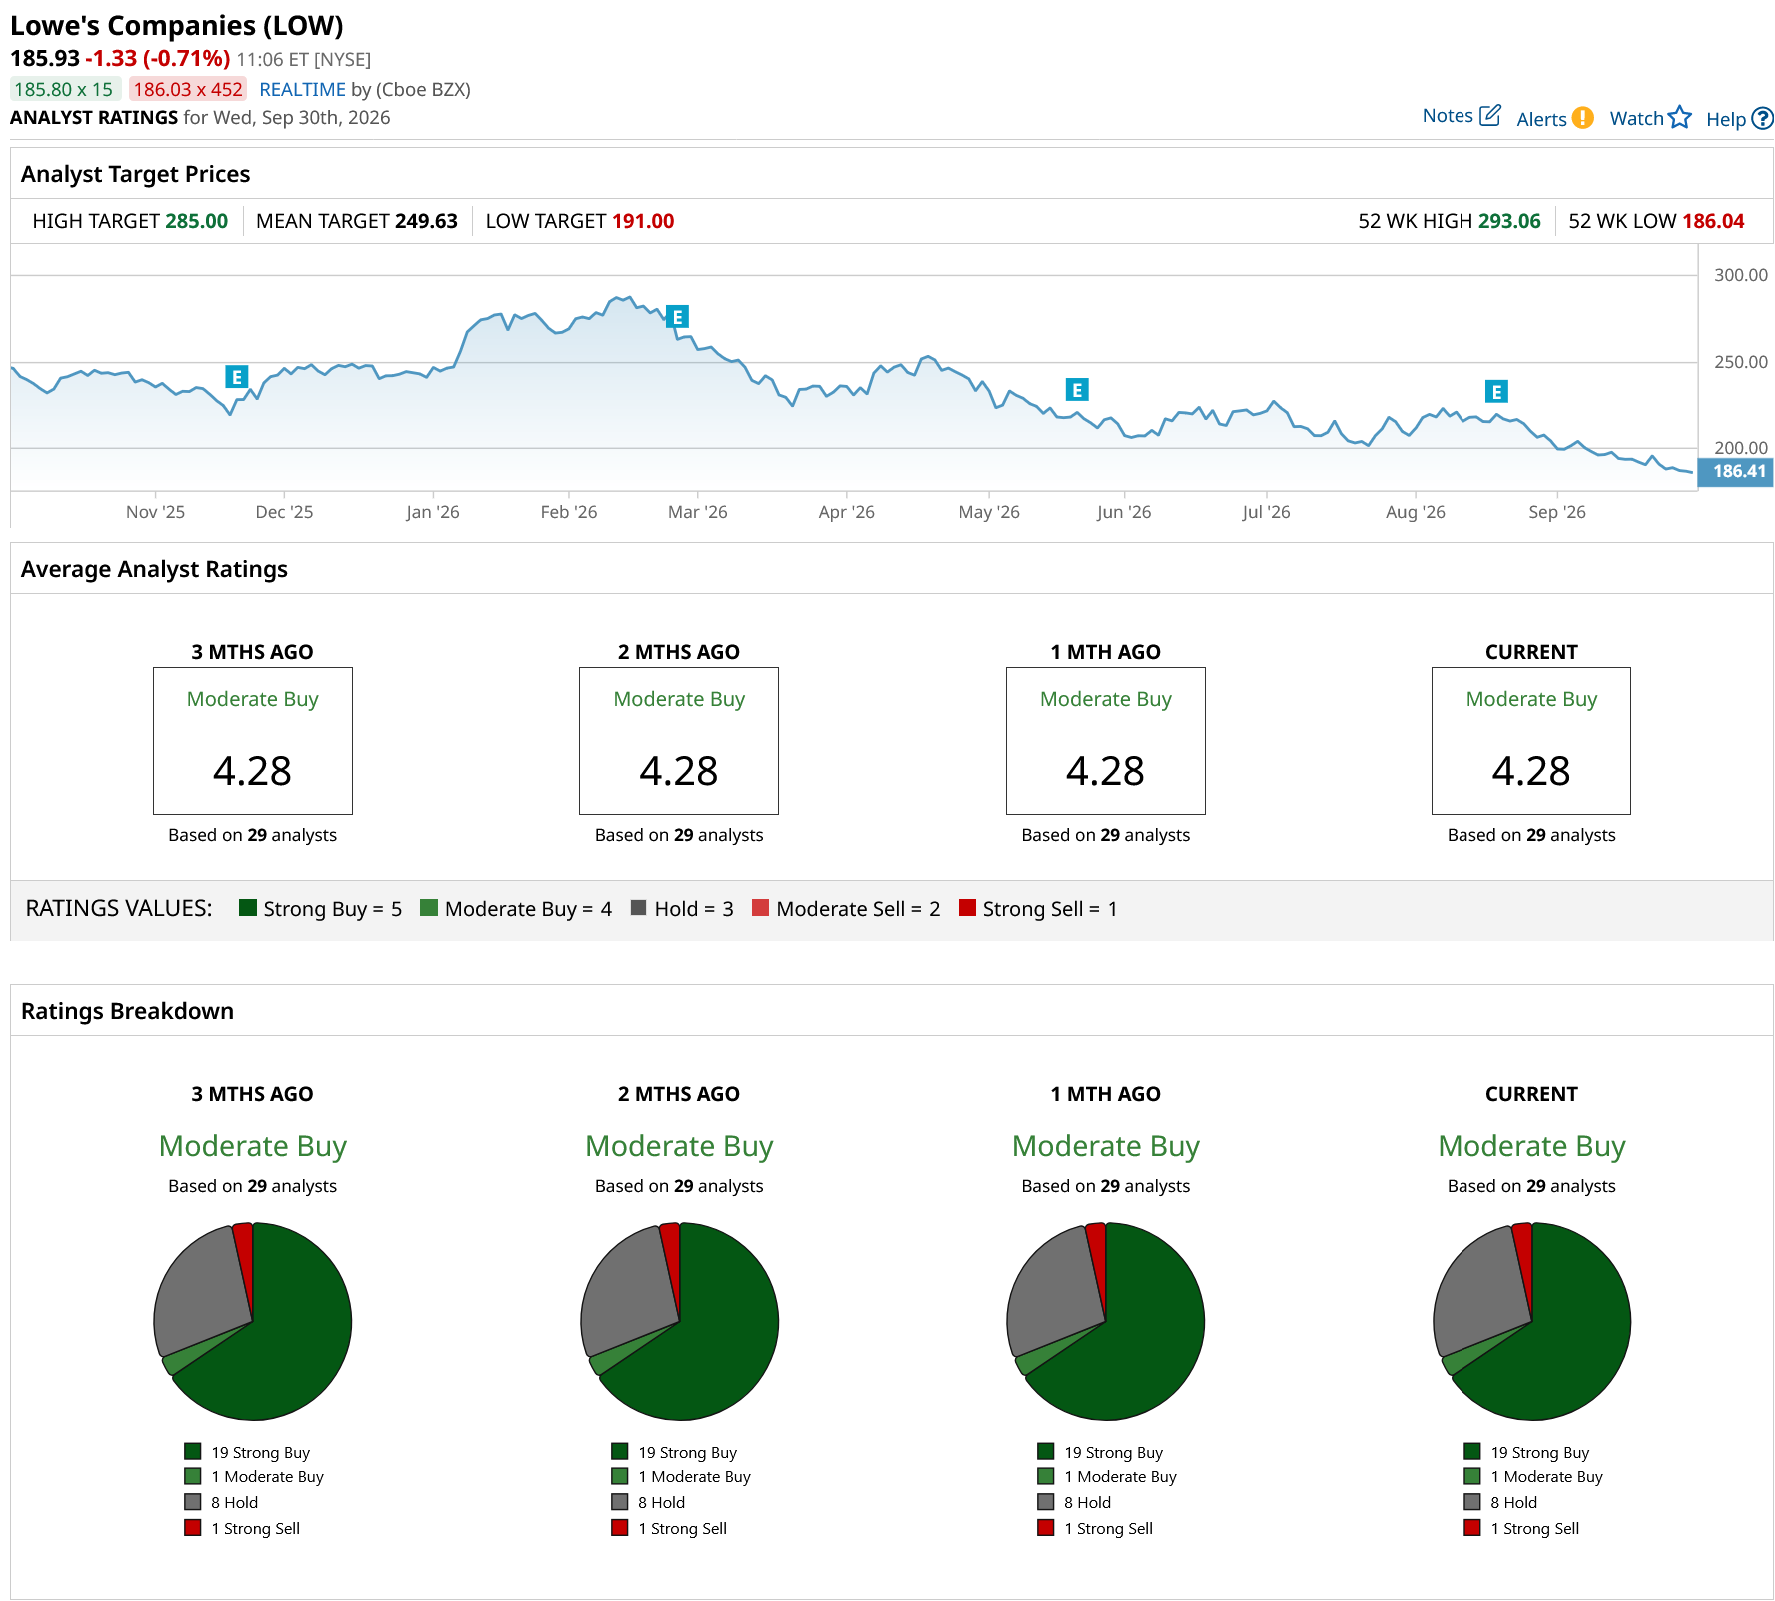
Wall Street is cautiously bullish on Lowe’s prospects. Overall, LOW stock has a consensus “Moderate Buy” rating. Of the 29 analysts covering the stock, 19 advise a “Strong Buy,” one suggests a “Moderate Buy,” eight analysts are on the sidelines, giving it a “Hold” rating, and one recommends a “Strong Sell.”
LOW’s average analyst price target of $249.63 signals an upside potential of 34%. The Street-high target price of $285 suggests that the stock could rally as much as 53%.
On the date of publication, Subhasree Kar did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.