


Credit Portfolio Growth Might Change The Case For Investing In MercadoLibre Stock (MELI)
- MercadoLibre reported that its credit portfolio reached US$16.4b in Q2 2026, reflecting 75% year-over-year expansion supported by stronger credit card issuance and deeper use of Mercado Pago, while non-performing loans remained close to historical lows.
- The business highlighted that users active across both Marketplace and Mercado Pago increased 37% year over year, and that credit card holders are materially more likely to stay engaged across the ecosystem, underscoring how payments and lending can reinforce long-term platform stickiness.
- We will look at how this surge in cross-platform users, especially credit card customers, reshapes MercadoLibre's broader investment narrative.
Scan beyond MercadoLibre and track other ecosystem-driven platforms gaining traction with a curated list of 17 high quality undiscovered gems.
MercadoLibre Investment Narrative Recap
To own MercadoLibre, you need to believe its commerce and fintech ecosystem can keep deepening engagement while heavy spending and an expanding loan book eventually translate into healthier earnings. The latest quarter fits that story. A US$16.4b credit portfolio with near historical low non performing loans and strong cross platform usage reinforces the idea that payments, lending and marketplace activity can feed each other.
The flip side is clear. Rapid credit expansion and longer loan terms keep the risk of higher losses alive, especially with already compressed margins and a high debt load. This update does not erase that concern. It simply shows the short term catalyst remains execution on credit quality and unit economics, while any setback on provisions or funding costs still looks like the biggest operational threat.
Among recent context, the focus on MercadoLibre’s credit portfolio and Mercado Pago growth matters most here. Analysts point to a US$16.4b book with near historical low short term non performing loans and improving net interest margin after losses. That is exactly the area investors are watching, because the lending arm now sits at the intersection of growth, risk and funding needs.
If that portfolio keeps scaling while asset quality and collections stay disciplined, it can support the broader catalyst of better margins once investment intensity levels out. If losses or provisions accelerate instead, the same engine that feeds engagement could weigh on net income and constrain reinvestment. The recent Q2 data does not settle that debate. It provides fresher evidence to weigh those credit driven outcomes.
MercadoLibre's narrative projects US$75.8b revenue and US$5.2b earnings by 2029. That path reflects analysts assuming 29.1% yearly revenue growth and an earnings increase of about 2.7x from US$1.9b today.
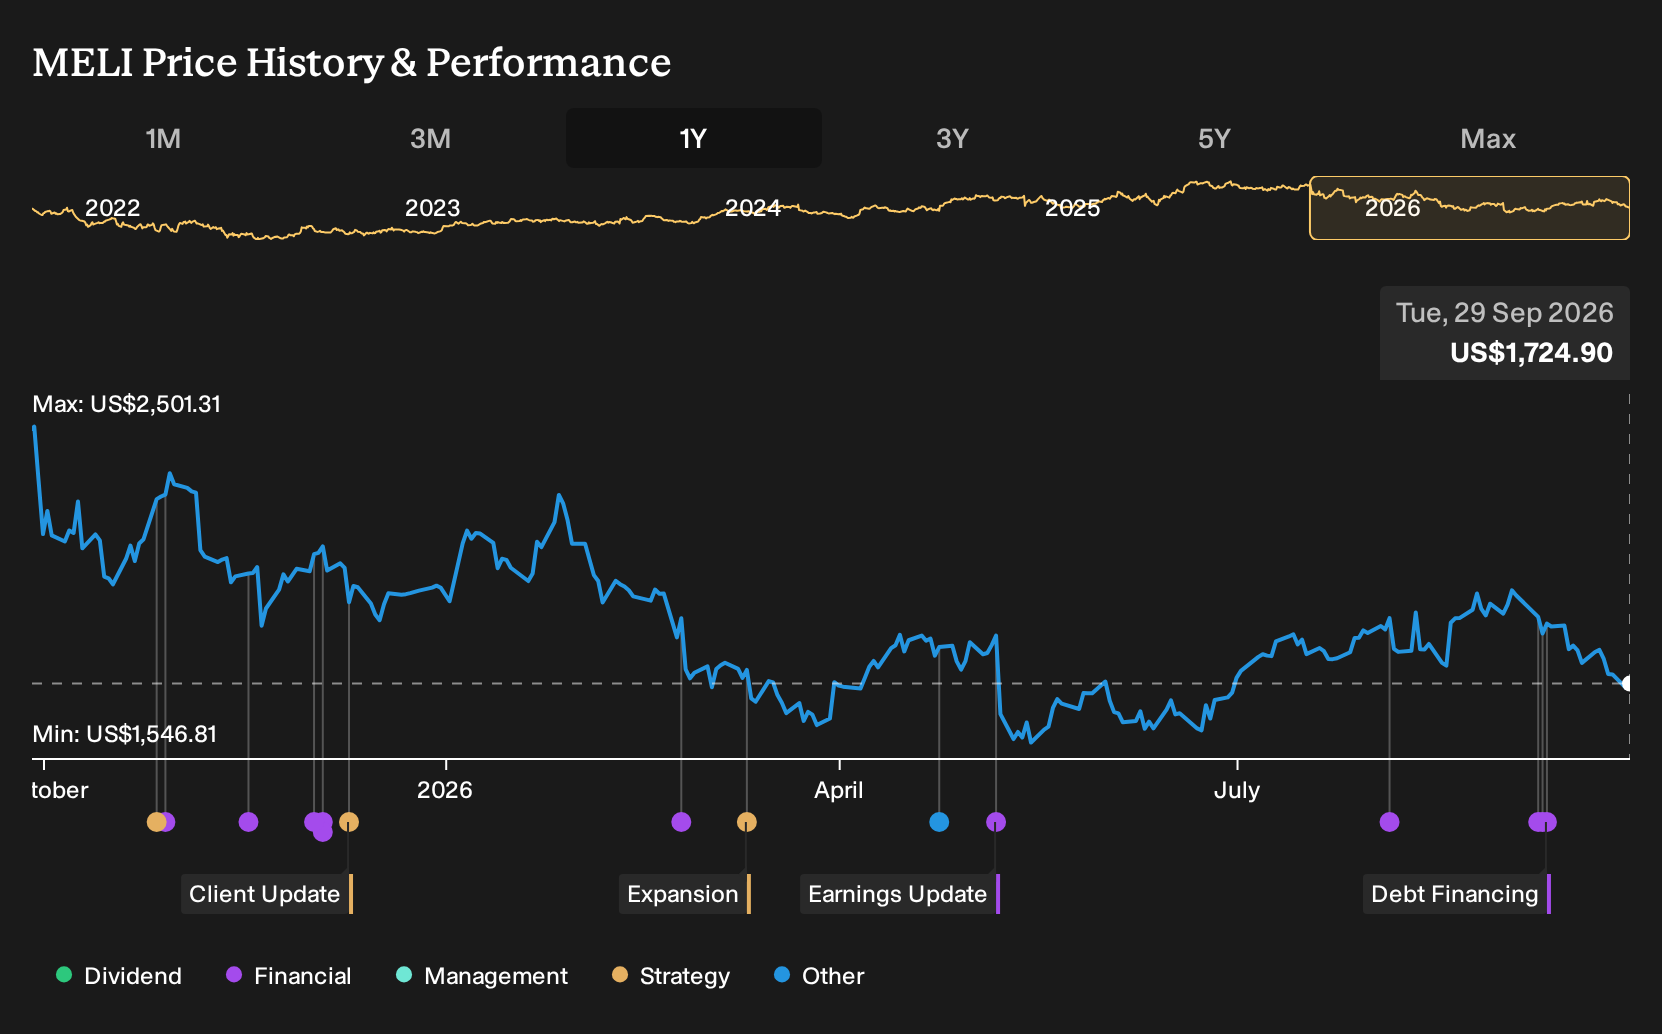
Uncover why MercadoLibre's fair value indicates a 31% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest MercadoLibre forecasts lean hard into competitive pressure. Those analysts saw slower revenue growth of about 23.4% a year and earnings of roughly US$3.6b by 2029, well below consensus. This fresh credit and cross platform data could challenge that view, so treat it as one of several angles to compare.
Explore 21 other MercadoLibre fair value estimates, including one that suggests it could be worth just $1750.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own instincts instead.
- A great starting point for your MercadoLibre research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for MercadoLibre. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MercadoLibre's overall financial health at a glance.
Looking For More Ideas Beyond MercadoLibre?
If the MercadoLibre story has you thinking about where ecosystem effects and solid fundamentals might show up next, it can help to scan a wider field of companies that fit different risk and return profiles.
- For investors who want potential upside but still care about financial strength, start with a list of solid balance sheet and fundamentals (25 results) that already screens for resilient fundamentals.
- If capital preservation and smoother rides matter more to you than chasing every rally, focus on a 32 resilient stocks with low risk scores that filters for historically steadier performers.
- Those looking for opportunities the market may not be fully focused on yet can review a 17 high quality undiscovered gems that already highlights companies with stronger underlying metrics than their visibility suggests.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com