


Nvidia Just Spent Nearly $13 Billion on Something Other Than GPUs. Here’s How It Helps NVDA.
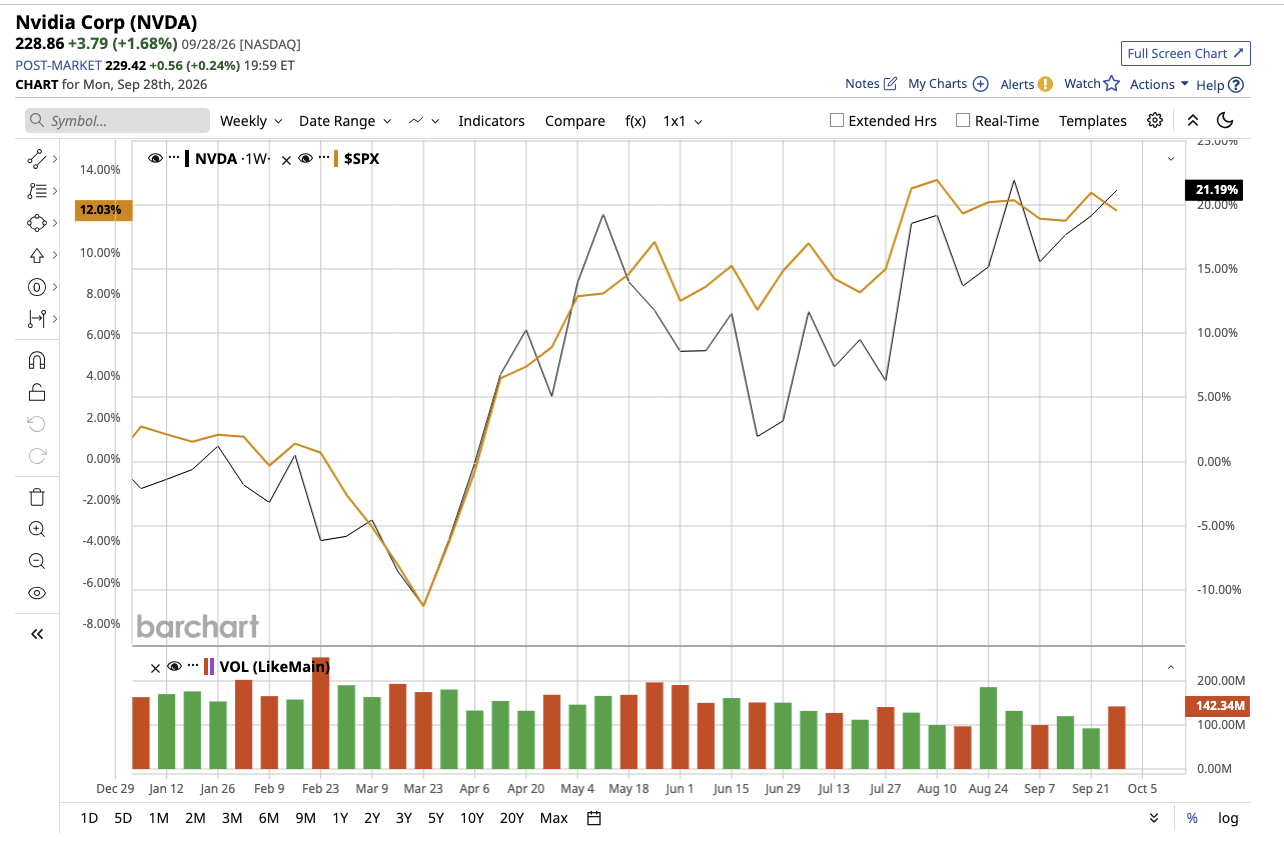
Nvidia (NVDA) has become a multi-trillion-dollar company by supplying much of the hardware behind the artificial intelligence (AI) industry's rapid expansion. The stock has climbed close to 1,000% over the past five years. And now it has agreed to spend nearly $13 billion on something that isn't another GPU or piece of computing infrastructure.
The deal may look unusual for a company whose explosive growth has been driven by GPUs. But what Nvidia is buying may say a lot about where the AI business is heading next.
Nvidia Is Buying the Layer Above the Chips
On Sept. 2, Nvidia entered into a definitive agreement to acquire Hugging Face, the open AI development platform, for $12.93 billion. The deal is expected to close by the first half of 2027 once it receives all the regulatory approvals. According to the terms of the agreement, $11.9 billion will go to Hugging Face shareholders, while up to roughly $1 billion is earmarked for an equity-based employee retention program.
While the acquisition is large and its second-largest deal overall, Nvidia has the financial muscle to make this bet. The company’s revenue grew 106% year over year to $96 billion in the second quarter of fiscal 2027, with adjusted earnings up 120% to $2.22 per share. At the end of the quarter, Nvidia had $22.4 billion in cash and cash equivalents and another $34.1 billion in marketable debt securities. It also held $42.7 billion of marketable equity securities.
Hugging Face is not a chipmaker. It is a platform that gives developers a place to build, share, and put AI models, datasets, and applications to work. Nvidia says over “18 million developers, researchers, and creators use Hugging Face to share more than 3 million models, 500,000 datasets, and 1 million applications.” The company added that more than 200,000 companies use it for various AI-related work. Nvidia has built its billion-dollar business selling the hardware AI applications run on. But this acquisition will move it closer to the developers building those AI applications or the people deciding which models get built, tested, customized, and deployed.
The acquisition price may look enormous compared to Hugging Face’s revenue. According to Reuters, Hugging Face had been generating roughly $150 million in annualized revenue around the time Nvidia agreed to the deal. However, the strategic payoff from this acquisition may not happen immediately but from what the platform enables Nvidia to do over the next few years.
Essentially, the biggest opportunity from this acquisition is influence. If Hugging Face continues to attract millions of developers, thousands of companies, and an expanding universe of open models and applications, Nvidia will be in a much stronger position at the start of the AI development process. As a result, Nvidia can identify emerging workloads, deepen software adoption, and potentially create more demand for the accelerated computing infrastructure it provides.
What It Could Ultimately Mean for NVDA
Nvidia is already running a powerful engine with close to $90 billion in data center revenue. The Hugging Face deal is basically a bet that Nvidia can build an even larger ecosystem around that engine. Nvidia’s goal is to remain at the center of AI, even as the industry becomes less reliant on a single type of chip.
At 24x forward earnings, Nvidia stock isn’t expensive even as analysts expect its earnings to grow at extraordinary rates. Analysts forecast fiscal 2027 revenue rising 90.6% to $411.5 billion and EPS climbing 95.1% to $9.31. Additionally, by fiscal 2028, revenue is expected to reach $682.73 billion and EPS to reach $15.68. Despite its enormous growth and high expectations, Nvidia stock is still a reasonable buy now.
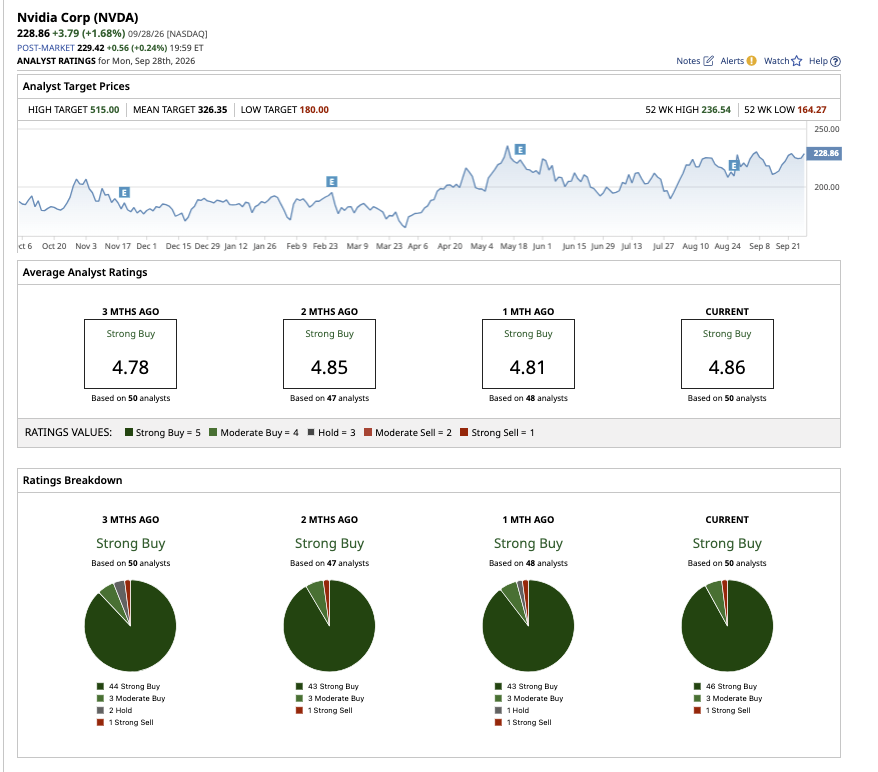
On Wall Street, NVDA stock holds a consensus “Strong Buy” rating. Out of the 50 analysts covering the stock, 46 have a “Strong Buy” recommendation, three rate it a “Moderate Buy,” and one analyst has a “Strong Sell” rating. Wall Street’s mean target price of $326.35 for NVDA implies a potential upside of 42.6% from current levels. Plus, the high price estimate of $515 implies a potential upside of 125% over the next 12 months.
On the date of publication, Sushree Mohanty did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.