


3 TSX Growth Stocks With Insider Ownership Up To 27%
In the face of fluctuating interest rates and geopolitical tensions, Canada's equity markets have shown resilience, though the landscape has shifted with large-cap stocks outperforming their smaller counterparts. In this environment, growth companies with high insider ownership may offer unique insights and potential stability, as insiders' vested interests can align closely with shareholder value in times of economic uncertainty.
Top 10 Growth Companies With High Insider Ownership In Canada
| Name | Insider Ownership | Earnings Growth |
| ROK Resources (TSXV:ROK) | 16.9% | 130% |
| Propel Holdings (TSX:PRL) | 25.7% | 39.7% |
| Hammond Power Solutions (TSX:HPS.A) | 27.1% | 32% |
| Firan Technology Group (TSX:FTG) | 12.6% | 22% |
| Electrovaya (TSX:ELVA) | 34.9% | 47.9% |
| Cizzle Brands (NEOE:CZZL) | 13.2% | 90.4% |
| CEMATRIX (TSX:CEMX) | 10.7% | 28.9% |
| Cambria Gold Mines (TSXV:CAMB) | 12% | 85.3% |
| Aritzia (TSX:ATZ) | 16.2% | 20.3% |
| Allied Gold (TSX:AAUC) | 15.4% | 39.4% |
Here's a peek at a few of the choices from the screener.
goeasy (TSX:GSY)
Simply Wall St Growth Rating: ★★★★★☆
Overview: goeasy Ltd. offers non-prime leasing and lending services through its easyhome, easyfinancial, and LendCare brands to consumers in Canada, with a market cap of CA$683.06 million.
Operations: The company's revenue segments consist of CA$145.02 million from Easyhome and CA$1.36 billion from Easyfinancial.
Insider Ownership: 19.5%
goeasy faces challenges with recent earnings declines and dividend suspension, yet forecasts suggest robust revenue growth of 38.8% annually, outpacing the Canadian market. Despite significant insider selling recently, no substantial buying occurred in the past three months. The appointment of Mark Snyder as Chief Credit Risk & Data Officer aims to enhance risk management and support disciplined growth. However, debt coverage by operating cash flow remains a concern amidst these developments.
- Click here to discover the nuances of goeasy with our detailed analytical future growth report.
- According our valuation report, there's an indication that goeasy's share price might be on the expensive side.
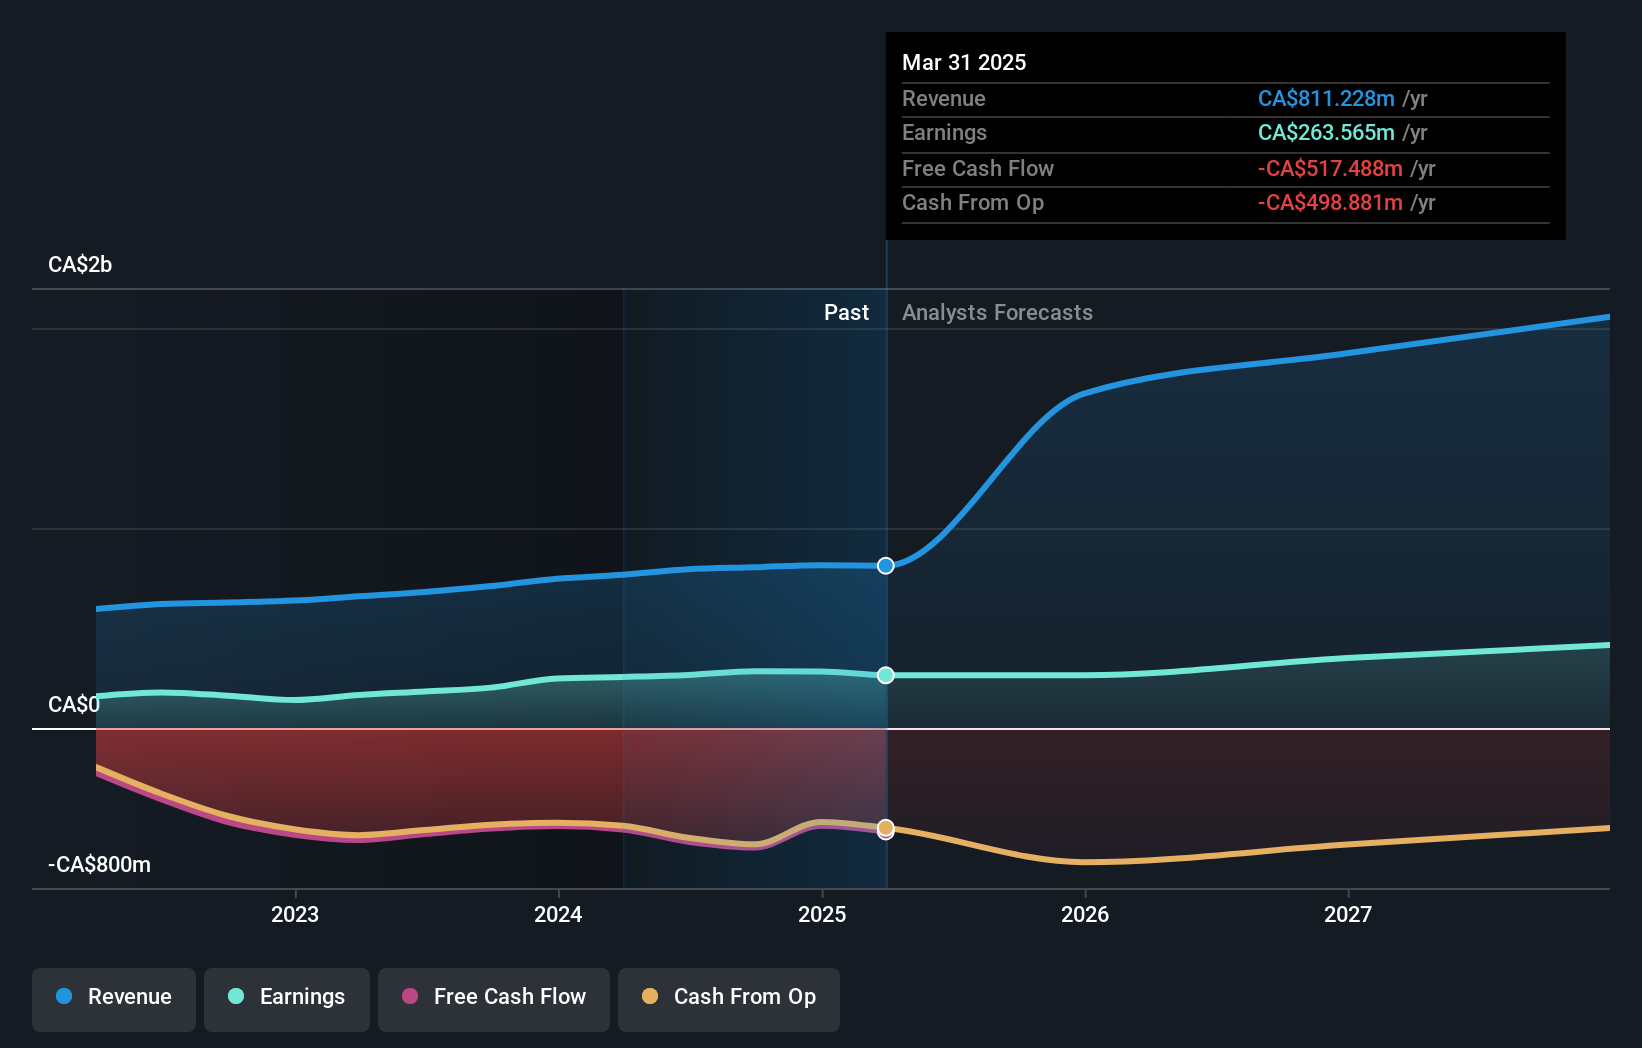
Hammond Power Solutions (TSX:HPS.A)
Simply Wall St Growth Rating: ★★★★★★
Overview: Hammond Power Solutions Inc., along with its subsidiaries, designs, manufactures, and sells various transformers across Canada, the United States, Mexico, and India with a market cap of CA$3.34 billion.
Operations: The company generates CA$1.06 billion from its manufacture and sale of transformers across its operating regions.
Insider Ownership: 27.1%
Hammond Power Solutions Inc. is expanding its U.S. operations with a new facility in Fort Worth, Texas, expected to significantly boost manufacturing capacity by CAD 250M initially. Despite recent earnings declines and profit margin contraction from 9.6% to 5.8%, revenue growth is forecasted at 21.8% annually, outpacing the Canadian market's growth rate of 4.3%. Insider activity shows more shares sold than bought recently, though no substantial insider buying occurred in the past three months.
- Unlock comprehensive insights into our analysis of Hammond Power Solutions stock in this growth report.
- The analysis detailed in our Hammond Power Solutions valuation report hints at an deflated share price compared to its estimated value.
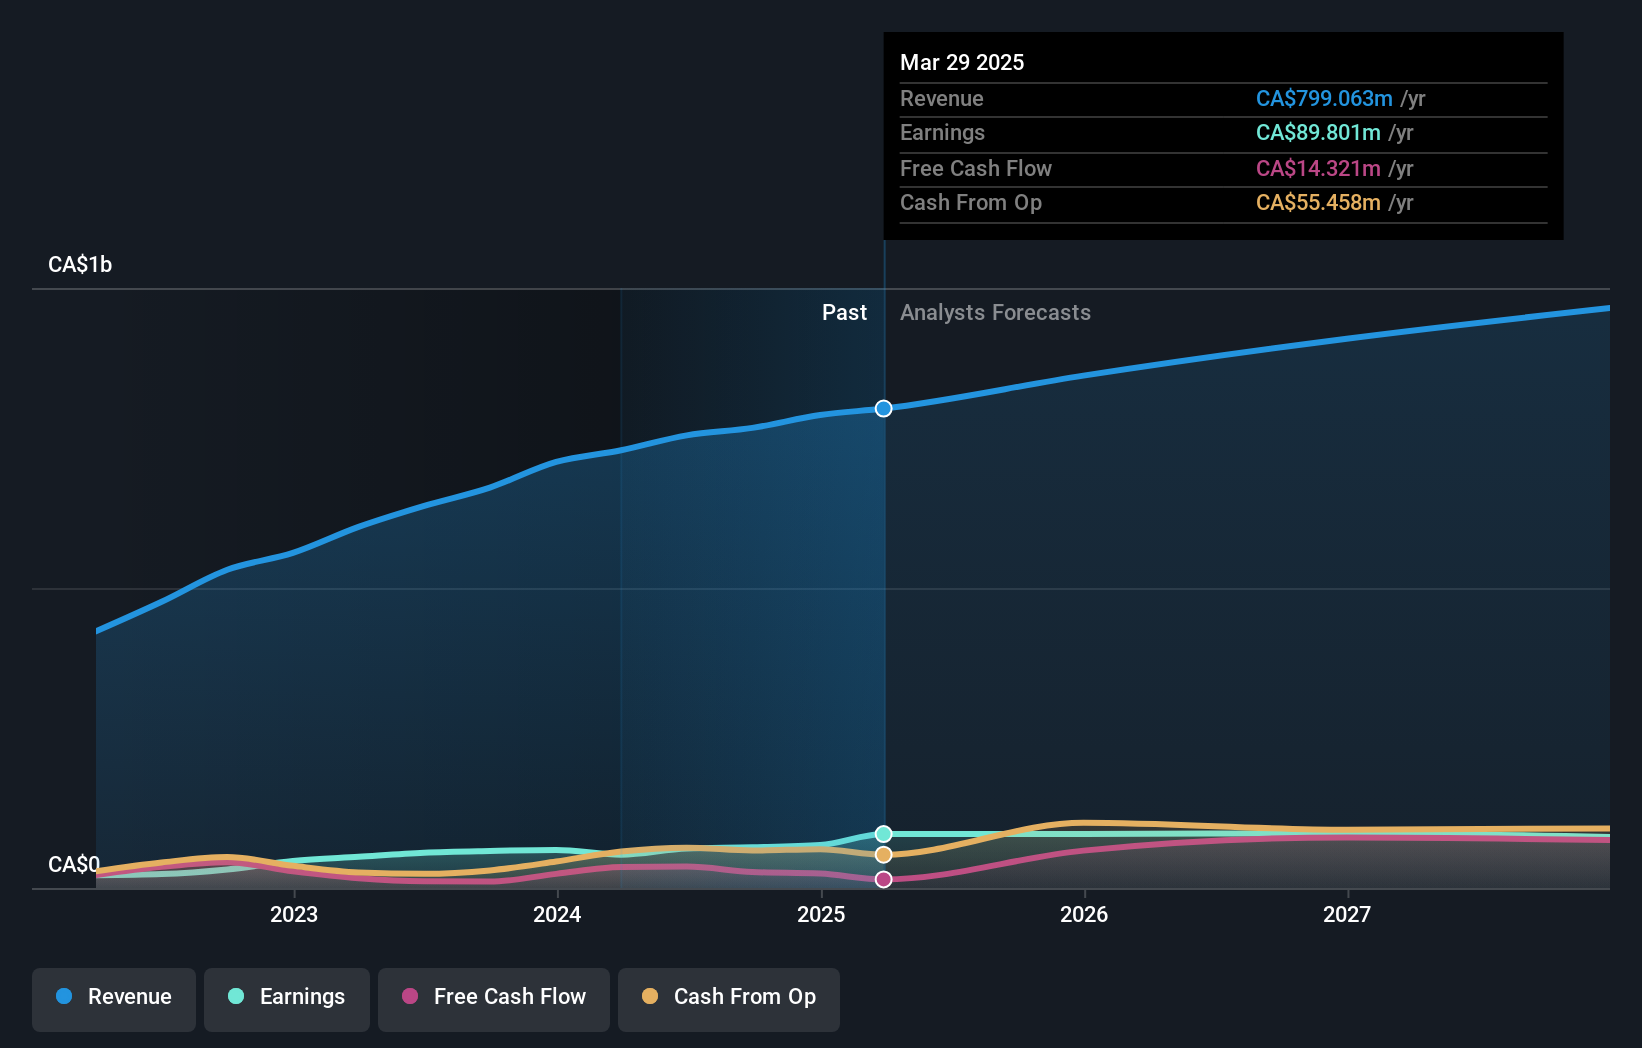
Lightspeed Commerce (TSX:LSPD)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Lightspeed Commerce Inc. provides cloud-based software subscriptions and payment solutions for various businesses, including retailers, restaurants, and golf course operators, with a market cap of CA$1.78 billion.
Operations: The company's revenue is primarily derived from its cloud-based software and programming segment, which generates $1.24 billion.
Insider Ownership: 10.9%
Lightspeed Commerce, a Canadian growth company with significant insider ownership, is enhancing its platform with strategic partnerships and product innovations. Recent initiatives include the "On Deck" feature for golf courses and integration with ShipStation for streamlined retail operations. Despite limited insider buying recently, insiders have sold fewer shares than purchased over the past three months. While revenue growth is projected at 8.3% annually, slower than some high-growth peers, profitability prospects remain above market average expectations within three years.
- Click here and access our complete growth analysis report to understand the dynamics of Lightspeed Commerce.
- In light of our recent valuation report, it seems possible that Lightspeed Commerce is trading behind its estimated value.
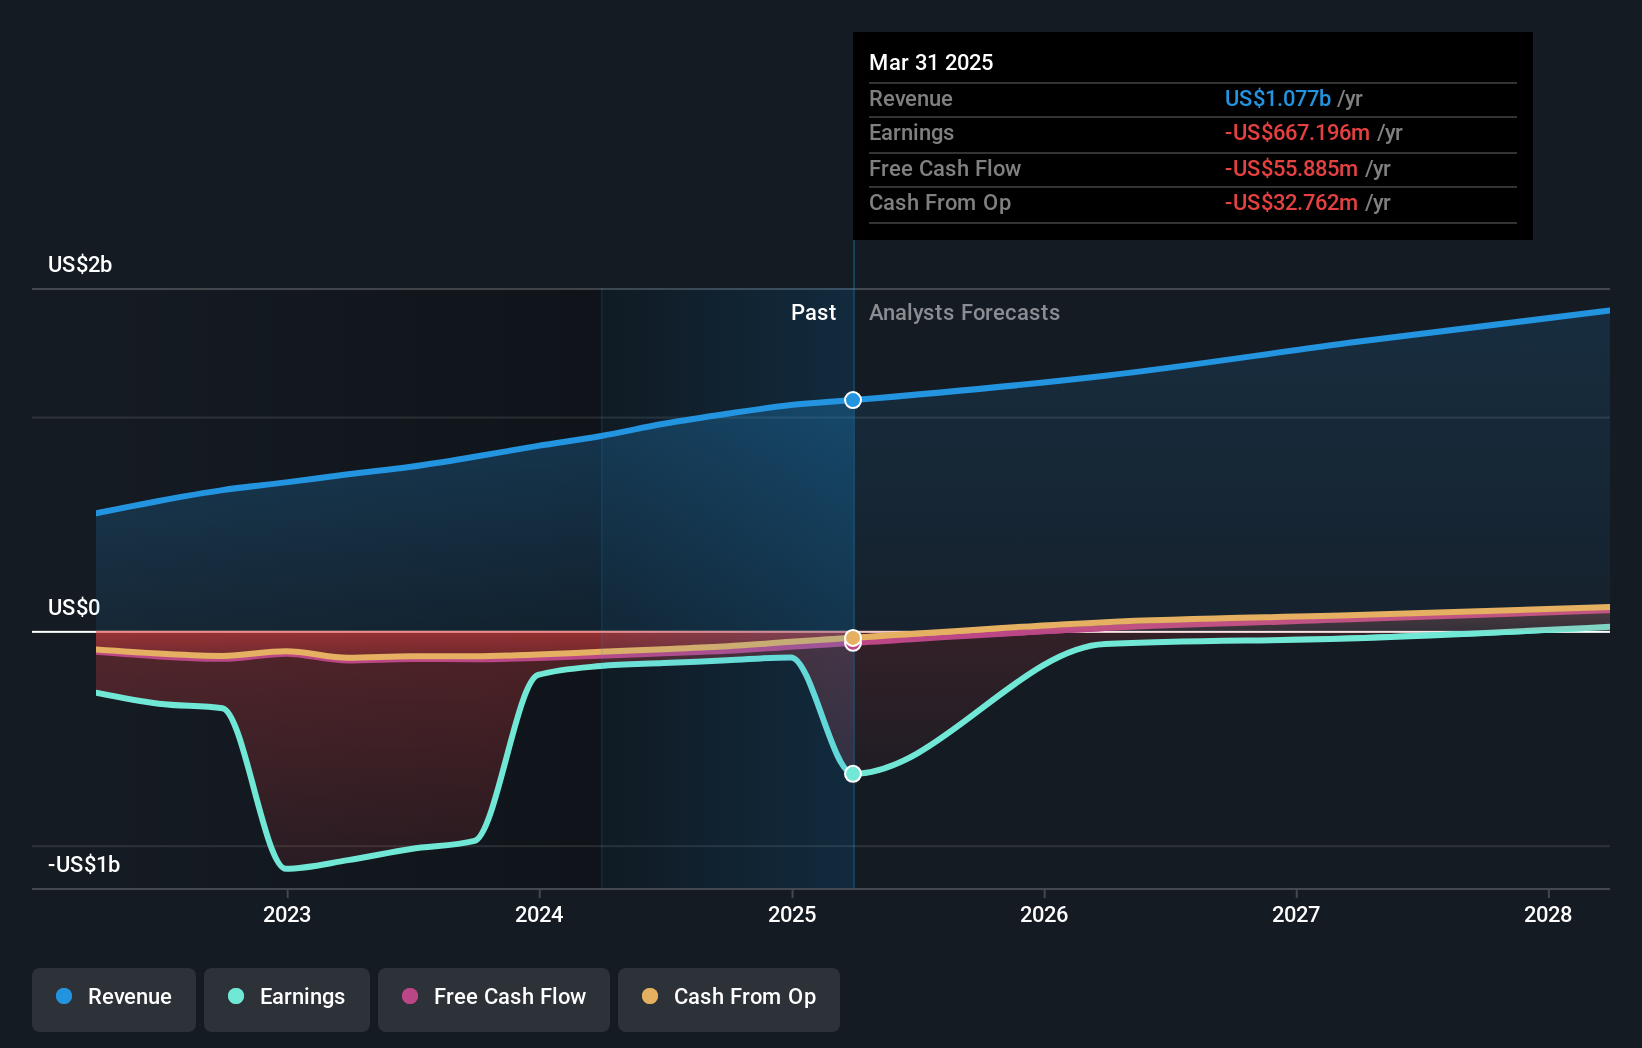
Key Takeaways
- Delve into our full catalog of 49 Fast Growing TSX Companies With High Insider Ownership here.
- Contemplating Other Strategies? Rare earth metals are an input to most high-tech devices, military and defence systems and electric vehicles. The global race is on to secure supply of these critical minerals. Beat the pack to uncover the 35 best rare earth metal stocks of the very few that mine this essential strategic resource.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com