


Exploring 3 Undervalued Small Caps With Insider Activity Across Regions
Over the past 7 days, the United States market has experienced a slight decline of 1.5%, although it has shown a robust increase of 12% over the last year, with earnings projected to grow by 18% annually. In this environment, identifying stocks that are potentially undervalued and exhibit insider activity can be an effective strategy for investors looking to capitalize on growth opportunities within the small-cap sector.
Top 10 Undervalued Small Caps With Insider Buying In The United States
| Name | PE | PS | Discount to Fair Value | Value Rating |
|---|---|---|---|---|
| Regional Management | 6.0x | 0.4x | 38.25% | ★★★★★☆ |
| Shore Bancshares | 11.3x | 3.3x | 38.35% | ★★★★★☆ |
| Financial Institutions | 9.5x | 3.2x | 24.32% | ★★★★★☆ |
| Cardinal Infrastructure Group | NA | 0.8x | 42.85% | ★★★★★☆ |
| Surgery Partners | NA | 0.6x | 25.44% | ★★★★★☆ |
| Bank of Marin Bancorp | NA | 7.2x | 32.65% | ★★★★☆☆ |
| Union Bankshares | 9.4x | 2.0x | 47.01% | ★★★★☆☆ |
| German American Bancorp | 12.9x | 4.8x | 28.82% | ★★★☆☆☆ |
| Five Star Bancorp | 14.4x | 6.2x | 47.78% | ★★★☆☆☆ |
| Orion Group Holdings | 94.5x | 0.4x | 48.76% | ★★★☆☆☆ |
Let's uncover some gems from our specialized screener.
Franklin Financial Services (FRAF)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Franklin Financial Services operates primarily in community banking and wealth management, with a market capitalization of approximately $0.14 billion.
Operations: Franklin Financial Services generates revenue primarily from its Community Banking and Wealth segments, with Community Banking being the larger contributor at $73.08 million. The company's operating expenses are driven mainly by General & Administrative costs, which reached $49.89 million in the latest period. Despite fluctuations, Franklin's net income margin has shown varied performance over time, standing at 26.98% most recently.
PE: 11.4x
Franklin Financial Services, a smaller player in the U.S. market, shows potential through steady financial growth and insider confidence. Their earnings for Q2 2026 increased with net income at US$6.61 million from US$5.91 million last year, and earnings per share rising to US$1.47 from US$1.32. The company repurchased 10,950 shares for US$0.63 million between April and June 2026, indicating management's belief in its value proposition amidst a forecasted annual earnings growth of 12%.
- Dive into the specifics of Franklin Financial Services here with our thorough valuation report.
Learn about Franklin Financial Services' historical performance.

River City Bank (RCBC)
Simply Wall St Value Rating: ★★★★☆☆
Overview: River City Bank operates in the banking sector, providing financial services with a focus on traditional banking operations, and has a market cap of $1.25 billion.
Operations: River City Bank generates its revenue primarily from banking activities, with recent figures showing $154.93 million in revenue. The company consistently reports a gross profit margin of 100%, reflecting that it incurs no cost of goods sold. Operating expenses are mainly driven by general and administrative costs, which amounted to $36.53 million in the latest period. The net income margin has shown an upward trend, reaching 50.51% recently, indicating efficient management of expenses relative to revenue growth over time.
PE: 9.2x
River City Bank, recently added to the S&P TMI and NASDAQ Composite Indexes, completed a $121.5 million IPO in August 2026. Their second-quarter earnings showed net income rising to US$19.62 million from US$15.41 million year-over-year, with basic earnings per share increasing to US$1.37 from US$1.05. Despite these gains, future earnings are expected to decline by 4.9% annually over three years, posing challenges for growth prospects in the banking sector's competitive landscape.
- Delve into the full analysis valuation report here for a deeper understanding of River City Bank.
Gain insights into River City Bank's past trends and performance with our Past report.
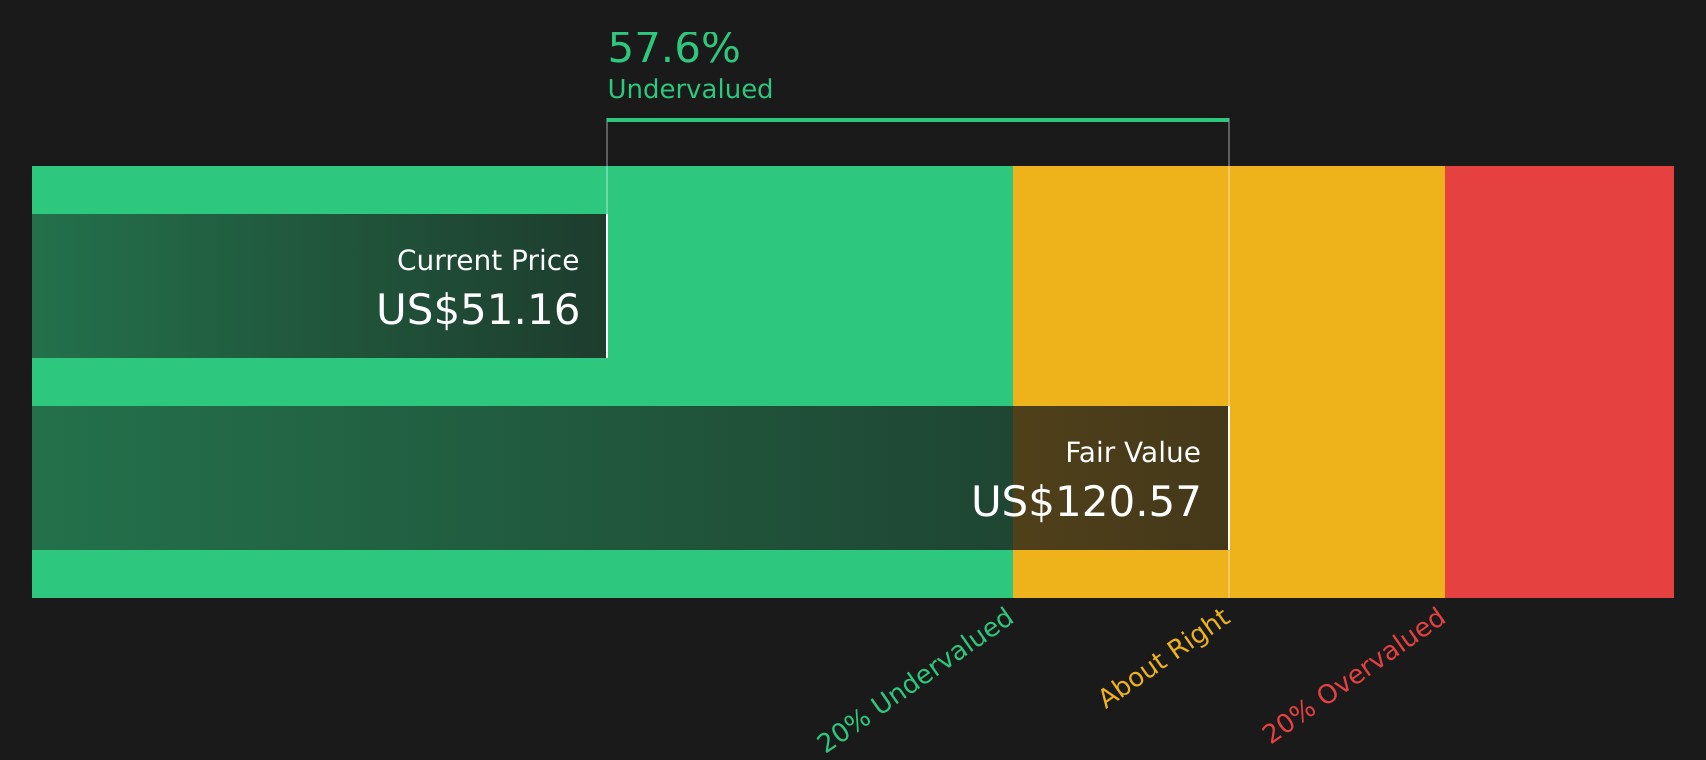
Capital Southwest (CSWC)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Capital Southwest is a business development company that provides financing solutions to middle-market businesses, with a market cap of approximately $0.64 billion.
Operations: The company's revenue primarily stems from its investment activities, with recent figures reaching $237.21 million. Operating expenses are a significant cost component, totaling $28.51 million in the latest period. The gross profit margin has consistently been 100%, indicating that all reported revenue translates directly into gross profit without any deduction for costs of goods sold (COGS).
PE: 13.6x
Capital Southwest, a player in the lower middle market investment space, recently saw insider confidence with share purchases over the past year. The U.S. Small Business Administration's approval to boost its leverage commitment from $175 million to $250 million strengthens its capital deployment capabilities through SBIC II. Despite being dropped from the NASDAQ Composite Index in August 2026, Capital Southwest continues to demonstrate resilience with solid revenue growth and a strategic focus on fixed-income offerings and dividend payments.
- Get an in-depth perspective on Capital Southwest's performance by reading our valuation report here.
Explore historical data to track Capital Southwest's performance over time in our Past section.
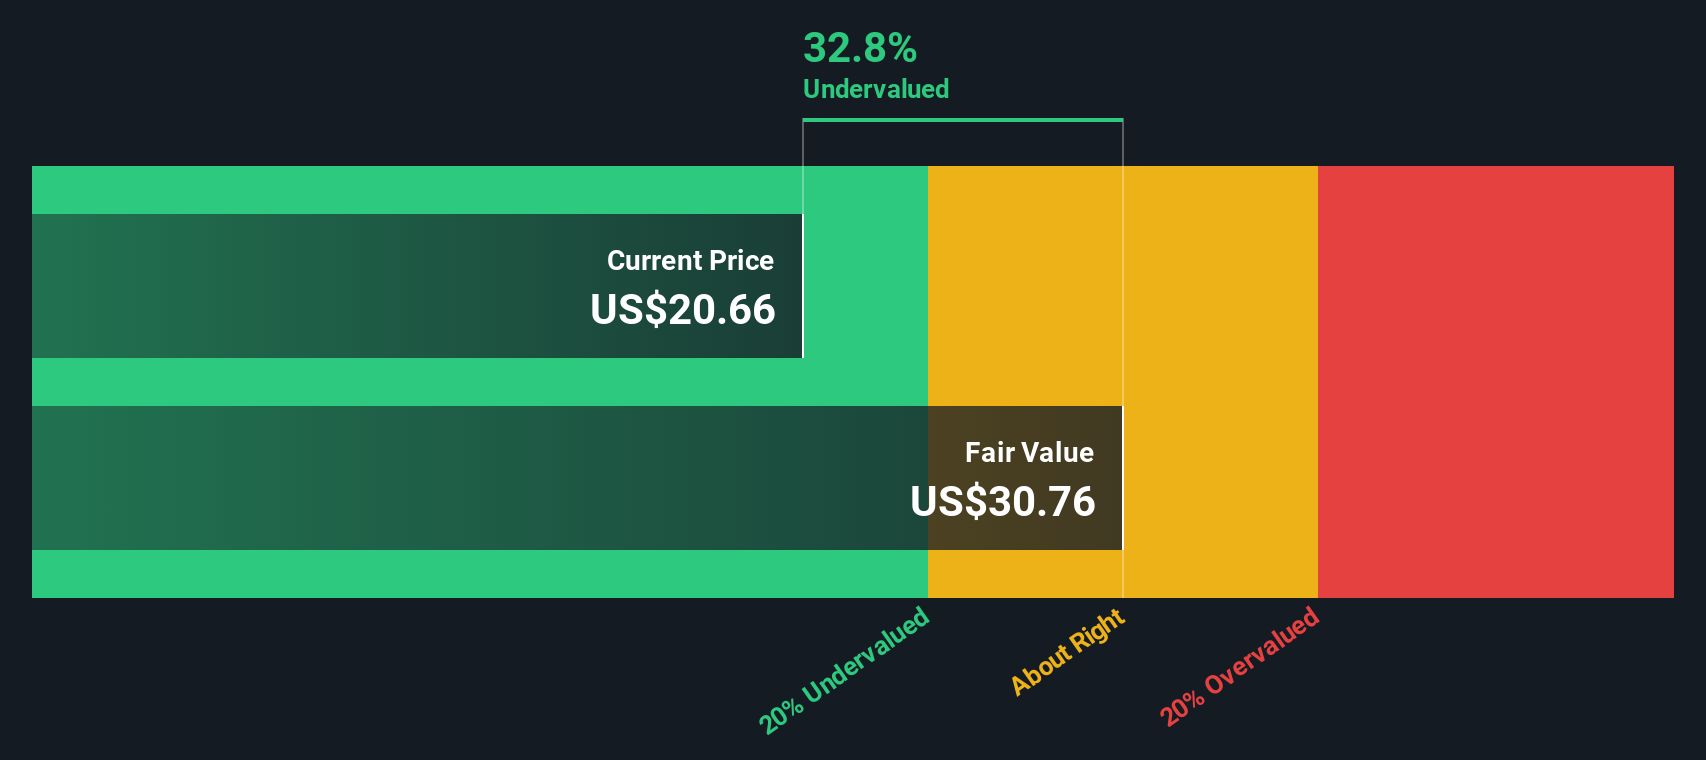
Where To Now?
- Unlock our comprehensive list of 68 Undervalued US Small Caps With Insider Buying by clicking here.
- Have a stake in these businesses? Integrate your holdings into Simply Wall St's portfolio for notifications and detailed stock reports.
- Join a community of smart investors by using Simply Wall St. It's free and delivers expert-level analysis on worldwide markets.
Looking For Alternative Opportunities?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com