


3 Australian Biotech Stocks With Up To 77% Fair Value Upside
Australia’s inflation rate sitting at 4% and interest rates at a 15 year high of 4.6% are squeezing many growth stories. Yet that pressure also pushes investors toward companies with solid balance sheets and clear funding runways. That matters for Australian biotechnology stocks, where capital access can make or break a breakthrough. This article highlights three listed biotech opportunities screened for financial resilience and reasonable value.
The three biotech stocks covered below are a small sample of what screens well on balance sheet strength and valuation for this theme, with the full filter surfacing 5 more listed players with similarly interesting stories that are not covered in this article.
If you want to identify and analyze a wider field of potential biotech winners with healthier funding profiles, head straight to the Biotech Stocks screener.
Vita Life Sciences (ASX:VLS)
Overview: Vita Life Sciences sells branded vitamins, minerals, herbal supplements and superfood products, linking everyday wellness with nutraceutical focused biotech themes.
Operations: Vita Life Sciences generates about A$43 million from Australia and A$46 million from Malaysia and Singapore, plus A$6 million from China and Vietnam.
Market Cap: A$148 million
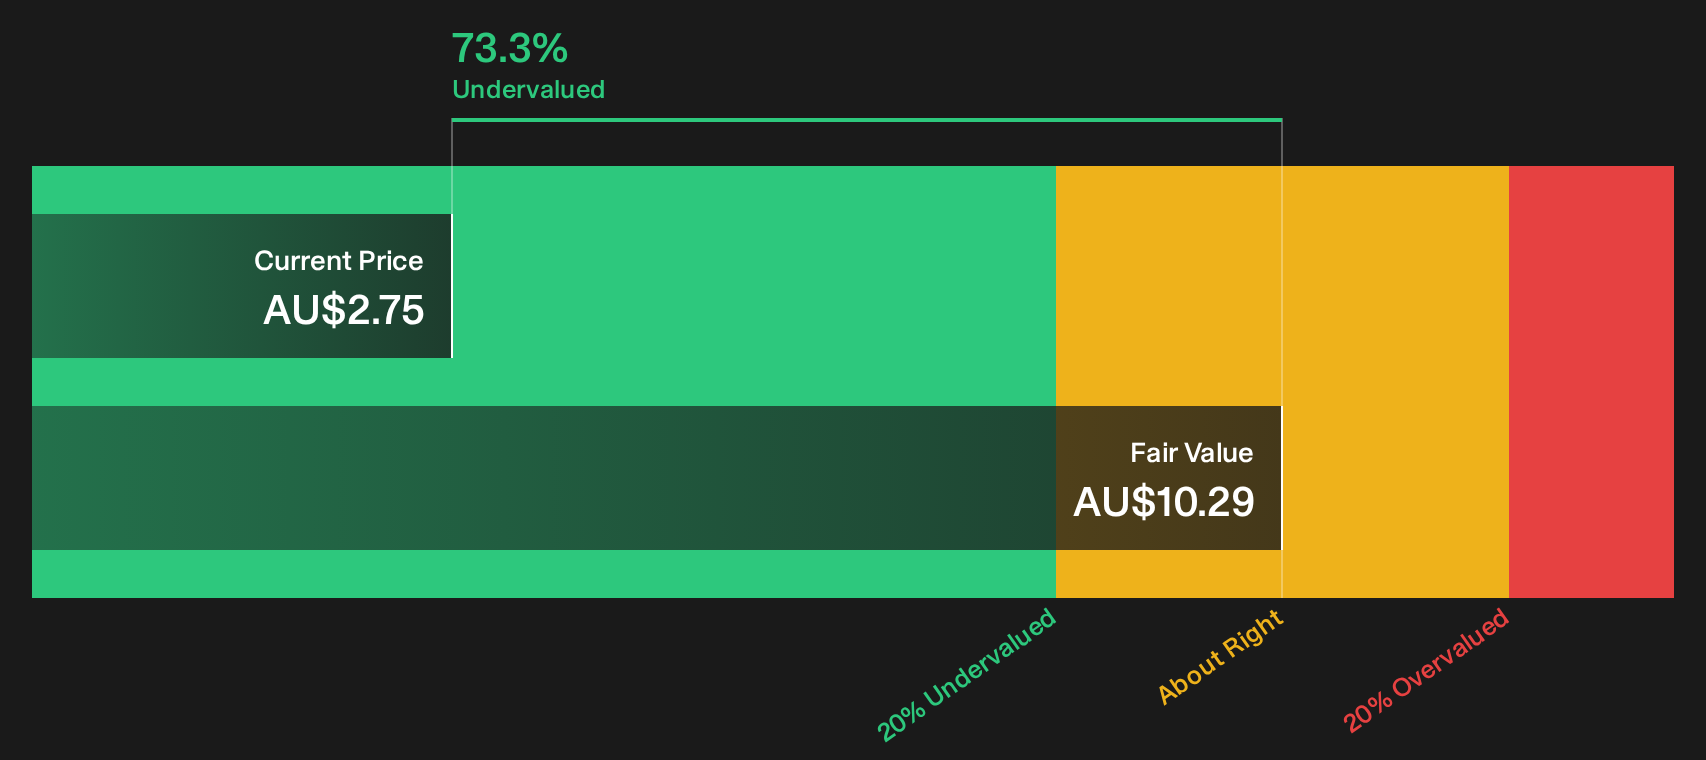
Vita Life Sciences ties biotech style nutraceutical formulation to everyday health products, supported by a 20% ROE, 11.6% net margins and a 5.09% dividend yield. The stock trades on a 13.3x P/E and at a large discount to one fair value estimate. This makes the improving profitability in its latest half year result, and the potential impact if that trend reverses, particularly important.
To see how that valuation tension could resolve, review the DCF valuation analysis for Vita Life Sciences and consider how future execution might influence the outcome.
Clinuvel Pharmaceuticals (ASX:CUV)
Overview: Clinuvel Pharmaceuticals develops melanocortin based biopharmaceutical treatments like SCENESSE for rare phototoxic and pigmentary disorders, alongside smaller photocosmetic products.
Operations: Clinuvel Pharmaceuticals generates about A$94 million from its biopharmaceutical segment, with A$53 million from Ireland and A$41 million from the United States.
Market Cap: A$423 million
Clinuvel Pharmaceuticals fits the Biotech Stocks theme through its focus on SCENESSE for erythropoietic protoporphyria and related melanocortin drug programs. Progress in late stage studies and new delivery platforms could materially reshape the long term balance between risk and reward for patient outcomes and investors alike.
"Heavy dependence on SCENESSE as a single core revenue product exposes Clinuvel to substantial concentration risk. Any future regulatory setbacks, new competing therapies, or pricing pressure in this market could lead to sharp revenue volatility and declining earnings."
What happens to Clinuvel’s margins and growth will hinge on how quietly building competitive pressure in its niche ultimately plays out.
That kind of pressure can cut both ways for Clinuvel, so read the full narrative for Clinuvel Pharmaceuticals to see how concentration risk, new indications and capital allocation could be decoupling beneath the surface.

Mayne Pharma Group (ASX:MYX)
Overview: Mayne Pharma Group is a specialty pharmaceutical business focused on women’s health and dermatology drugs, plus CDMO services for other biotech groups.
Operations: Mayne Pharma Group generates A$174 million from Women’s Health, A$139 million from Dermatology and A$71 million from International markets.
Market Cap: A$230 million
For investors hunting biotech linked opportunities with real commercial products, Mayne Pharma Group offers exposure to prescription driven women’s health and dermatology treatments alongside a CDMO arm that helps other drug developers get therapies to patients.
"Expansion in Women's Health, including NEXTSTELLIS, IMVEXXY, BIJUVA and ANNOVERA, is supported by rising awareness of hormone replacement therapy and contraceptive options, which can support higher prescription volumes and revenue over time."
What happens when one less visible cost and funding pressure finally eases or bites harder could reshape how reliable those improving earnings really are.
If that pressure on costs and funding is what worries you, read the full narrative for Mayne Pharma Group to see how Mayne Pharma Group’s earnings story could be quietly accelerating.

Seeking Fresh Alternatives Before They Fly
Fresh ideas often move first. Slow reactions can end up chasing momentum when prices are already rising rapidly. Scan for opportunities that are still under the radar, before the wider crowd, and consider acting while they are less noticed.
- Identify cash rich contenders early by running the list of solid balance sheet and fundamentals (12 results) to focus on companies with funding strength while it may still be a differentiating factor.
- Look for income-focused opportunities by scanning the 3 dividend fortresses and filtering for yield focused businesses before prices and payouts adjust.
- Explore potential early stage breakthroughs by checking the 15 high quality undiscovered gems while they are still releasing research updates with relatively limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com